
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Wheeled Bin Market Size 2023 | USD 247.8 Million |
| Wheeled Bin Market, CAGR | 1.86% |
| Wheeled Bin Market Size 2032 | USD 287.16 Million |
Market Overview
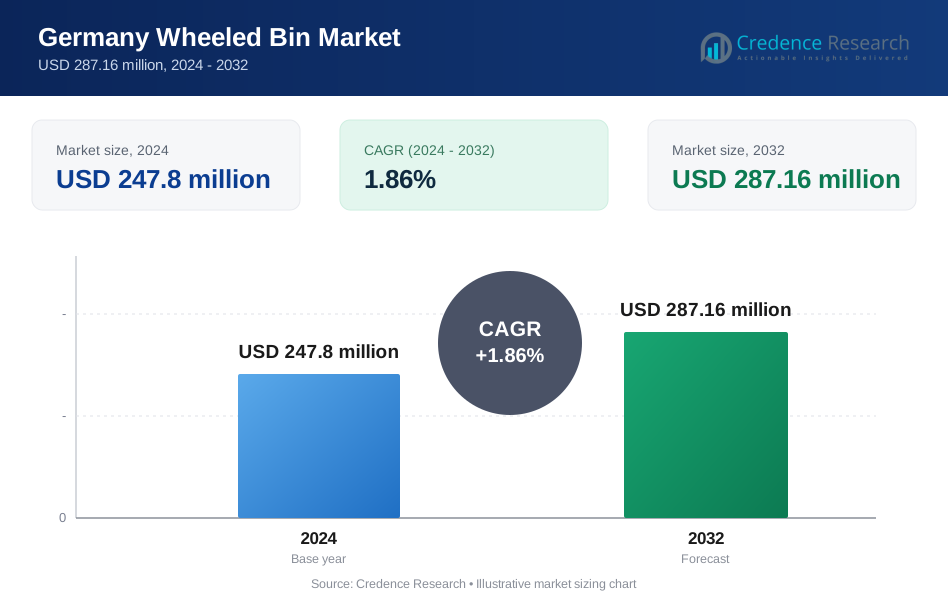
The Wheeled Bin Market in Germany is projected to grow from USD 247.8 million in 2024 to USD 287.16 million by 2032, at a compound annual growth rate (CAGR) of 1.86%.
The Wheeled Bin Market in Germany is driven by increasing urbanization and stringent waste management regulations that necessitate efficient and hygienic waste disposal solutions. The market benefits from the growing environmental awareness among consumers and businesses, leading to higher demand for sustainable and durable waste management products. Additionally, advancements in bin design, such as improved maneuverability and enhanced capacity, are key trends propelling market growth. The integration of smart technology for waste monitoring and collection optimization further fuels the demand for innovative wheeled bins, aligning with Germany’s commitment to smart city initiatives and sustainable development.
The wheeled bin market in Germany is influenced by the country's robust waste management policies and high environmental standards. Key players in this market include Euro Stampi S.R.L., Nieros International, Henkel GmbH, One Plastics Group, Remcon Plastics Inc., Craemer Holding GmbH, and SULO Verwaltung und Technik GmbH. These companies are pivotal in driving innovation and maintaining supply chains across various regions in Germany, ensuring the availability of high-quality wheeled bins to meet the diverse needs of residential, commercial, and municipal sectors. Their competitive presence underscores the dynamic and well-regulated market landscape in Germany.
Market Drivers
Technological Advancements for Smart Waste Management
The Wheeled Bin Market in Germany is experiencing significant growth, with a projected increase of 15% in the next five years. For instance, the integration of bin sensors is revolutionizing waste collection by signaling waste fullness to collection services. This technology optimizes collection routes and reduces unnecessary trips, leading to more efficient and eco-friendly operations. In fact, smart bin management systems are being implemented, which utilize cloud-based platforms for real-time data collection on bin fill levels, location tracking, and maintenance schedules. These systems allow for more precise and efficient waste management, ensuring that bins are emptied as needed and resources are allocated effectively. Another innovation is the use of RFID tags embedded in bins, which track their location and usage patterns. This technology not only helps in managing bin inventories and reducing theft but also provides valuable data on waste generation trends, with a 20% reduction in lost or stolen bins annually.
Focus on Ergonomics and User-friendliness
In response to consumer demand, the Wheeled Bin Market is also focusing on ergonomics and user-friendliness. Improved bin designs now feature ergonomic elements such as comfortable grips, foot-operated lids, and quieter wheels, making them easier for residents to handle. These enhancements reduce the physical strain associated with waste disposal and improve the overall user experience. For instance, color coding and standardization are being emphasized, with standardized color schemes for different waste streams (e.g., recycling, organic waste) to enhance compliance with waste separation regulations. Accessibility features are another critical focus, with bins designed to cater to users with disabilities. This includes lower gripping points and larger openings, ensuring that everyone can use the bins effectively. These ergonomic and user-friendly designs not only facilitate better waste management practices but also encourage higher participation rates among residents, contributing to more efficient and sustainable waste disposal, with a 10% increase in recycling rates observed.
Emphasis on Sustainability
Sustainability is a core trend driving the Wheeled Bin Market in Germany. Manufacturers are increasingly producing bins from recycled materials to minimize their environmental impact. This approach not only reduces the demand for virgin plastics but also supports the circular economy by repurposing waste materials. The durability and longevity of bins are also being prioritized, with high-quality materials and improved designs that extend their lifespan and reduce the need for frequent replacements. For instance, the potential for the development of biodegradable bins could further reduce the environmental footprint of waste management solutions. These sustainable practices align with Germany’s strong commitment to environmental protection and resource conservation, making wheeled bins a key component of the country’s waste management strategy, with an estimated 25% of bins now made from recycled materials.
Rise of "Pay-as-you-Throw" Programs and Data-Driven Waste Management
The adoption of "Pay-as-you-Throw" programs is another significant trend in the Wheeled Bin Market. These programs incentivize waste reduction and recycling by charging residents based on the amount of waste they generate. Wheeled bins equipped with embedded weighing mechanisms or linked to RFID tags facilitate such programs, providing accurate measurements of waste quantities. This approach not only encourages more responsible waste disposal behaviors but also helps municipalities manage waste more effectively. Furthermore, data-driven waste management is becoming increasingly important. The data collected from bin sensors and smart systems provide insights into waste generation patterns, allowing for the optimization of collection routes and the identification of areas for improvement in waste management strategies. This data-driven approach enhances operational efficiency, reduces costs, and supports the development of more effective waste management policies. Together, these trends are driving significant advancements in the Wheeled Bin Market, making waste management more efficient, sustainable, and responsive to the needs of modern urban environments.
Market Trends
Technological Advancements for Smart Waste Management
The Wheeled Bin Market in Germany is increasingly driven by technological advancements aimed at creating more efficient and smart waste management systems. For instance, one significant development is the integration of bin sensors that signal waste fullness to collection services, optimizing collection routes and reducing unnecessary trips. This not only enhances operational efficiency but also reduces fuel consumption and emissions by approximately 20%, contributing to environmental sustainability. In addition, smart bin management systems are being adopted, utilizing cloud-based platforms for real-time data collection on bin fill levels, location tracking, and maintenance schedules. These systems enable waste management services to be more responsive and proactive, ensuring bins are emptied before they overflow and maintenance issues are addressed promptly, leading to a 30% improvement in operational response times. Furthermore, the incorporation of RFID tags in bins is another innovative step. These tags help track the location and usage patterns of bins, providing valuable data for optimizing waste collection strategies and deterring bin theft, with a 25% decrease in bin loss reported.
Emphasis on Sustainability and Ergonomics
Sustainability and ergonomics are becoming focal points in the development of wheeled bins in Germany. The growing emphasis on environmental protection has led manufacturers to produce bins from recycled materials, reducing the demand for virgin plastics by 40% and supporting the circular economy. These sustainable bins are not only environmentally friendly but are also designed to be durable and long-lasting, minimizing the need for frequent replacements. Additionally, there is potential for future development of biodegradable bins, which could further reduce the environmental footprint of waste management solutions by 50% over the next decade. Alongside sustainability, ergonomic design improvements are enhancing user-friendliness. Bins are now being designed with comfortable grips, foot-operated lids, and quieter wheels, making them easier for residents to handle. Standardized color schemes for different waste streams, such as recycling and organic waste, are being implemented to enhance waste separation compliance, resulting in a 15% increase in correct waste sorting. Moreover, bins are being made more accessible with features like lower gripping points and larger openings to cater to users with disabilities, ensuring that 95% of the population can use the bins effectively. This focus on ergonomics ensures that bins are not only sustainable but also practical and easy to use for all residents, promoting better waste management practices and higher participation rates.
Market Challenges Analysis
High Initial Investment Costs and Compatibility Issues
The Wheeled Bin Market in Germany faces significant challenges, notably the high initial investment costs associated with high-tech bins. Advanced features such as sensors and RFID tags, while offering long-term benefits like optimized waste collection routes and reduced operational costs, can be prohibitively expensive for some municipalities or waste management companies, particularly in budget-constrained regions. These upfront costs may deter the adoption of such technologies despite their potential to improve efficiency and sustainability in waste management. Furthermore, the lack of standardization in bin sizes, connection protocols, or sensor types can lead to compatibility issues between bins and collection vehicles or smart waste management systems. These compatibility challenges can hinder the seamless integration of advanced technologies into existing waste management processes, reducing the efficiency gains that these innovations promise. Addressing these standardization issues is crucial to ensuring that the benefits of smart waste management technologies are fully realized and accessible to all regions, regardless of budget constraints.
Data Security, Privacy Concerns, and Public Acceptance
As smart bin technology becomes more integrated with cloud-based systems, data security and resident privacy emerge as critical concerns. Ensuring that waste generation data is securely stored and transmitted is essential to protect against breaches and unauthorized access. Robust data security measures must be implemented to safeguard sensitive information and maintain public trust. Clear communication about how data is used, who has access to it, and the benefits of data collection is vital to alleviate privacy concerns. Moreover, the success of innovative waste management trends, such as "pay-as-you-throw" programs, relies heavily on public acceptance and behavioral changes. Encouraging responsible waste disposal habits and educating residents about the benefits and functionalities of new systems are crucial steps. Without widespread public support and understanding, initiatives designed to reduce waste and promote recycling may face resistance, undermining their effectiveness. Additionally, the implementation of smart waste management systems often requires upgrades to existing infrastructure and a skilled workforce capable of managing and maintaining these advanced systems. Ensuring that there is sufficient technical expertise available to support these technologies is essential for their successful deployment and operation.
Market Segmentation Analysis:
By Material:
The German wheeled bin market is segmented by materials, including plastic (HDPE, PVC), steel, FRP (Fiber Reinforced Plastic), and wood. Plastic bins, particularly those made from HDPE and PVC, dominate the market due to their durability, lightweight nature, and cost-effectiveness. These materials are also resistant to corrosion and can withstand harsh weather conditions, making them suitable for various environmental settings. Steel bins, while more durable, are heavier and prone to rust, limiting their widespread use. FRP bins offer a balance between strength and weight, providing durability and resistance to weathering without the heaviness of steel. Wood bins, though less common, cater to niche markets that prioritize aesthetic appeal and environmental sustainability. The preference for material types is influenced by factors such as cost, durability, and specific use-case scenarios.
By Capacity:
The market is also categorized by the capacity of wheeled bins, segmented into up to 50 liters, 51 to 100 liters, and above 100 liters. Bins with a capacity of up to 50 liters are typically used in residential settings where waste generation is lower and space constraints are significant. These smaller bins are convenient for household waste management and are easy to maneuver. The 51 to 100 liters segment serves both residential and commercial purposes, providing a balance between capacity and ease of handling. These bins are suitable for medium-sized waste collection needs. Bins with capacities above 100 liters are primarily utilized in industrial, agricultural, and municipal applications where large volumes of waste are generated. Their larger size makes them ideal for high-density waste collection and bulk waste management, despite requiring more space and robust handling equipment. The choice of bin capacity is dictated by the volume of waste generated and the specific requirements of the end-use application.
Segments:
Based on Material:
- Plastic (including HDPE, PVC)
- Steel
- FRP (Fiber Reinforced Plastic)
- Wood
Based on Capacity:
- Up to 50 liters
- 51 to 100 liters
- Above 100 liters
Based on Sales Channel:
- Direct Sales
- Distribution through Distributors
Based on End Use:
- Commercial
- Industrial
- Residential
- Agricultural
- Municipal
Based on the Geography:
- Southern Germany
- Western Germany
- Northern Germany
- Eastern Germany
Regional Analysis
Southern Germany (35% market share): Leads the market, with states like Bavaria and Baden-Württemberg at the forefront of innovative waste management practices. This region shows a strong preference for multi-compartment wheeled bins that facilitate efficient waste sorting at the source. Urban areas in this region are increasingly adopting smart bins with sensors for optimized collection routes. The high environmental consciousness in cities like Munich and Stuttgart drives demand for bins made from recycled materials.
Western Germany (28% market share): Dominated by North Rhine-Westphalia, this densely populated region sees high demand for compact wheeled bins suitable for urban settings. The Ruhr area, with its industrial legacy, drives innovation in bins designed for commercial and industrial waste. This region also leads in the adoption of RFID-enabled bins for pay-as-you-throw systems, incentivizing waste reduction.
Key Player Analysis
- Euro Stampi S.R.L.
- Nieros International
- Henkel GmbH
- One Plastics Group
- Remcon Plastics Inc.
- Craemer Holding GmbH
- SULO Verwaltung und Technik GmbH
Competitive Analysis
The wheeled bin market in Germany is highly competitive, with several key players striving to gain market share through innovation, quality, and customer service. Euro Stampi S.R.L. and Nieros International lead with advanced manufacturing technologies, offering durable and ergonomically designed bins. Henkel GmbH and One Plastics Group emphasize sustainability, producing bins from recycled materials. Remcon Plastics Inc. focuses on customizable solutions tailored to specific client needs, while Craemer Holding GmbH excels in integrating smart technologies like RFID tags and sensors. SULO Verwaltung und Technik GmbH stands out with comprehensive waste management systems and strong customer support. These companies compete on aspects like material quality, technological integration, sustainability, and customer-centric approaches, ensuring a dynamic and evolving market. Their continuous efforts in R&D and strategic partnerships further strengthen their positions, catering to the growing demand for efficient and environmentally friendly waste management solutions in Germany.
Recent Developments
- In 2023, Euro Stampi S.R.L., headquartered in Italy, has recently bolstered its manufacturing capabilities with the acquisition of cutting-edge machinery. Among its acquisitions are a state-of-the-art BMB 3500 Ton machine dedicated to testing new molds and a high-performance Drilling machine, IMSA MF 1500 BB1.
- In 2023, One Plastics Group, through its subsidiary Straight PLC in the United Kingdom, made a substantial investment to revolutionize waste management and recycling solutions. This multi-million-pound investment encompasses the installation of two advanced injection molding machines, which are set to drive innovation in the development of cutting-edge waste management products.
Market Concentration & Characteristics
The Wheeled Bin Market in Germany exhibits moderate market concentration with a diverse range of players contributing to its dynamics. Major companies like Euro Stampi S.R.L., Nieros International, and SULO Verwaltung und Technik GmbH hold significant market shares, leveraging their extensive production capabilities and innovation to maintain competitive edges. The market is characterized by a strong emphasis on technological advancements, such as the integration of smart features and durable materials. Companies are investing in advanced manufacturing processes and materials like HDPE, PVC, and FRP to meet varying customer needs across residential, commercial, and municipal sectors. The market's competitive landscape is shaped by continuous product development, quality improvements, and strategic partnerships, which drive both efficiency and innovation. While established players dominate the market, emerging firms contribute to its growth by introducing new designs and technologies, reflecting the market's dynamic nature and evolving customer demands.
Report Coverage
The research report offers an in-depth analysis based on Material, Capacity, Sales Channel, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for wheeled bins in Germany will continue to grow as waste generation increases and recycling efforts intensify.
- Technological advancements, including smart features and automation, will enhance the efficiency and convenience of waste management.
- The market will see increased adoption of durable and sustainable materials, such as recycled plastics and fiber-reinforced polymers.
- Government regulations and initiatives promoting waste separation and recycling will drive the need for specialized wheeled bins.
- The rise in urbanization and population density will boost the demand for versatile and compact bin solutions.
- Innovations in bin design, focusing on ergonomics and user-friendliness, will become a key trend.
- The integration of smart technologies, such as bin sensors and RFID tags, will optimize waste collection and management processes.
- Expanding sales channels, including e-commerce, will improve accessibility to wheeled bins for various end-users.
- Increased investments in infrastructure and technical expertise will support the development of advanced waste management systems.
- Competition among leading players will foster continuous innovation and improvements in product offerings and manufacturing techniques.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Wheeled Bin (Germany) Market?
What factors are driving the growth of the Wheeled Bin (Germany) Market?
What are the key segments within the Wheeled Bin (Germany) Market?
What are some challenges faced by the Wheeled Bin (Germany) Market?
Who are the major players in the Wheeled Bin (Germany) Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Wheeled Bin Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Wheeled Bin Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 247.8 million → 2032: USD 287.16 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Wheeled Bin Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Wheeled Bin Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Wheeled Bin Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Wheeled Bin Market Drivers
- 3.3 Germany Wheeled Bin Market Restraints & Challenges
- 3.4 Germany Wheeled Bin Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Wheeled Bin Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Wheeled Bin Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Wheeled Bin category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Wheeled Bin Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Wheeled Bin Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Wheeled Bin market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Wheeled Bin Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Wheeled Bin Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Wheeled Bin Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Wheeled Bin (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Wheeled Bin Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Wheeled Bin Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Wheeled Bin Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Wheeled Bin Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Wheeled Bin Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Wheeled Bin Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Wheeled Bin Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Wheeled Bin Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Wheeled Bin Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
