
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Green Finance Market Size 2024 | USD 5068250 Million |
| Green Finance Market, CAGR | 21.45% |
| Green Finance Market Size 2032 | USD 23990438.28 Million |
Market Overview:
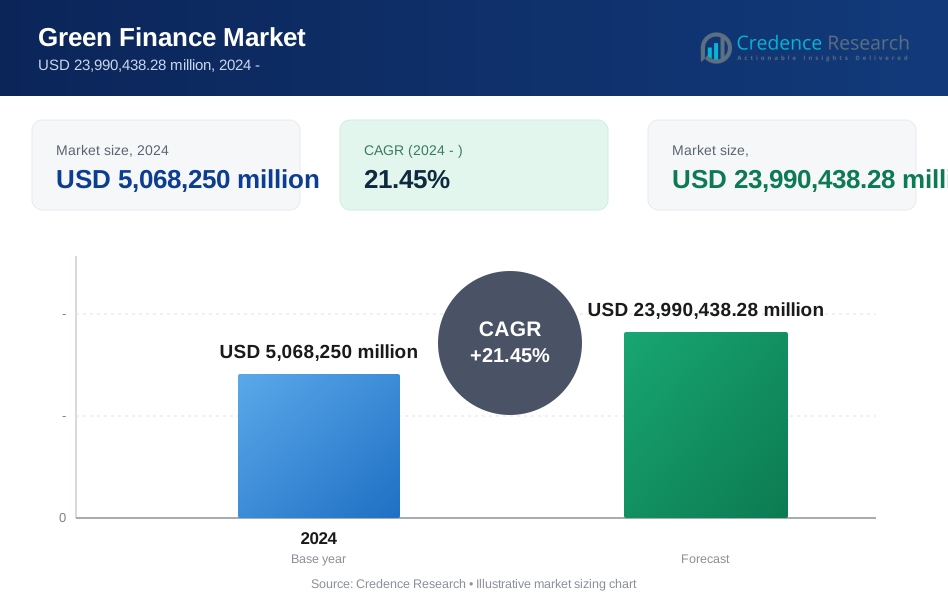
Green Finance Market size was valued at USD 5068250 million in 2024 and is anticipated to reach USD 23990438.28 million by 2032, at a CAGR of 21.45% during the forecast period (2024-2032).
Several key factors are driving the expansion of the green finance market. Regulatory frameworks and policy support, including the European Union’s Green Deal, the Sustainable Finance Disclosure Regulation (SFDR), and China's green bond standards, are reinforcing transparency and accountability in green investments. Moreover, growing investor interest in ESG-compliant portfolios, coupled with increased corporate responsibility and climate risk disclosures, is accelerating market momentum. Technological advancements in fintech and blockchain are further facilitating efficient tracking and reporting of green finance activities, enhancing investor confidence and market participation. Rising climate-related financial risks are prompting financial institutions to shift toward sustainable asset classes. In addition, voluntary carbon markets and transition finance instruments are gaining traction as part of broader climate finance strategies.
Regionally, Europe holds the largest share of the green finance market, supported by robust policy measures, sustainability-driven financial institutions, and a mature green bond market. North America follows, driven by corporate ESG initiatives and evolving regulatory landscapes. The Asia-Pacific region is emerging as a high-growth market, led by China, Japan, and South Korea, where government-backed sustainability programs and infrastructure investments are fostering green finance adoption. Southeast Asian nations are also launching regional taxonomies and green finance frameworks to attract sustainable capital. Meanwhile, African and Latin American countries are leveraging international climate finance mechanisms to fund clean energy and adaptation projects. Regional development banks and multilateral institutions are playing a critical role in de-risking sustainable investments in emerging markets. Cross-border collaborations and knowledge-sharing platforms are also accelerating regional green finance growth and alignment with global sustainability standards.
Market Insights:
- The green finance market is expected to grow from USD 5068250 million in 2024 to USD 23990438.28 million by 2032, at a CAGR of 21.45%.
- Regulatory support such as the EU Green Deal, SFDR, and China’s green bond standards is accelerating green capital flows.
- Investor demand for ESG-compliant portfolios is rising, driving growth in green bonds, climate funds, and sustainability-linked loans.
- Companies like Unilever and Patagonia are integrating sustainability into operations, showcasing strong corporate climate commitments.
- Fintech innovations and blockchain are improving ESG data tracking, transparency, and investor participation in green finance.
- Europe holds 45% of the global market, followed by North America (28%) and Asia-Pacific (19%) as a rapidly expanding region.
- Lack of global standards and limited ESG data in emerging markets pose risks of greenwashing and hinder inclusive market growth.
Market Drivers:
Regulatory Support and Policy Frameworks
Governments and regulatory bodies worldwide are playing a pivotal role in accelerating the growth of the green finance market. Comprehensive policy frameworks such as the European Union’s Sustainable Finance Action Plan, the Green Deal, and taxonomy regulations have set clear standards for sustainable investments. These initiatives are designed to enhance transparency, reduce greenwashing, and channel capital toward environmentally responsible projects. Similarly, countries like China, the UK, and Canada have introduced national green bond standards and disclosure requirements that support market development. The establishment of green taxonomies is helping investors identify eligible green assets and make informed decisions aligned with climate and sustainability goals.
Rising Demand for ESG and Sustainable Investments
Investor sentiment is increasingly shifting in favor of Environmental, Social, and Governance (ESG) considerations, driving the demand for green finance products. Institutional and retail investors are actively seeking portfolios that generate not only financial returns but also measurable environmental impact. For instance, Unilever is integrating sustainability into its business model by focusing on sustainable agriculture practices and reducing waste across its supply chain, demonstrating the growing commitment to sustainability among major corporations. This trend is reflected in the growing issuance of green bonds, sustainability-linked loans, and climate funds. Asset managers and pension funds are integrating ESG criteria into their investment strategies, supported by rising shareholder activism and stakeholder expectations. The demand for ESG reporting and assurance services is also increasing, encouraging companies to improve sustainability performance and transparency.
Climate Change Awareness and Corporate Responsibility
As climate risks become more evident, businesses and financial institutions are responding with stronger commitments to sustainability and climate resilience. Companies are setting net-zero targets, adopting science-based emissions reduction goals, and investing in clean technologies. For instance, Patagonia is committed to environmental responsibility by using environmentally-friendly materials in its products and promoting sustainable manufacturing practices, showcasing the ambitious goals being set by forward-thinking companies. Financial institutions are aligning their lending and investment portfolios with global climate goals, in line with frameworks like the Task Force on Climate-related Financial Disclosures (TCFD) and the Glasgow Financial Alliance for Net Zero (GFANZ). This growing corporate responsibility is driving green finance uptake as organizations seek to future-proof operations and enhance long-term value.
Technological Advancements and Innovation
Technology is significantly transforming the green finance landscape by enabling greater efficiency, transparency, and scalability. Fintech solutions, such as AI-powered ESG analytics and blockchain-based verification platforms, are improving the tracking and reporting of green assets. These tools enhance data reliability, streamline compliance processes, and increase investor confidence. Additionally, digital platforms are democratizing access to green investment opportunities, allowing broader participation from retail investors. Innovation in climate fintech is also supporting the development of new financial instruments tailored to sustainability outcomes, further driving growth in the green finance ecosystem.
Market Trends:
Surge in Green Bond Issuance
Green bonds continue to dominate the green finance market as a leading instrument for mobilizing capital toward sustainable projects. Governments, corporations, and multilateral institutions are increasingly issuing green bonds to finance initiatives such as renewable energy, energy-efficient infrastructure, and climate resilience. The growing standardization of green bond frameworks, including alignment with the International Capital Market Association (ICMA) principles, has enhanced market credibility. In addition, sovereign green bonds are gaining traction, with countries using them to signal long-term climate commitments and attract ESG-conscious investors.
Integration of ESG in Financial Strategies
The integration of Environmental, Social, and Governance (ESG) factors into financial decision-making has become a mainstream trend. Asset managers, banks, and insurers are embedding ESG metrics into risk assessments, portfolio management, and lending practices. This shift is driven by investor demand, regulatory mandates, and a broader recognition of the financial implications of climate risk. For instance, Reliance Industries, one of India's largest conglomerates, has committed to becoming net carbon zero by 2035, with significant investments in clean energy, particularly in solar and hydrogen projects. Companies are increasingly disclosing ESG performance in line with global standards such as the Task Force on Climate-related Financial Disclosures (TCFD), reinforcing transparency and investor trust.
Emergence of Transition Finance Instruments
Transition finance is emerging as a critical tool for supporting high-emission industries in their shift toward net-zero targets. Financial instruments such as sustainability-linked loans and transition bonds are enabling companies to access capital while committing to measurable climate goals. For instance, Mitsubishi Heavy Industries (MHI) Group issued its inaugural JPY 10 billion five-year transition bond in September 2022, with proceeds to be used for financing projects aimed at decarbonizing existing energy infrastructure and building hydrogen solutions. These instruments are especially relevant in sectors like energy, transportation, and heavy industry, where gradual decarbonization is essential. The growing acceptance of transition finance reflects a pragmatic approach to climate action, encouraging progress without limiting capital flow to only pure green assets.
Growth of Climate-Focused Fintech Solutions
Technological innovation is reshaping green finance through the rise of climate-focused fintech platforms. These tools leverage artificial intelligence, machine learning, and blockchain to provide real-time ESG analytics, automate impact reporting, and verify green claims. Startups and financial institutions are adopting these technologies to enhance efficiency and transparency in sustainable investing. The adoption of digital platforms is also expanding retail investor access to green products, further democratizing the market and accelerating capital flow into sustainable sectors.
Market Challenges Analysis:
Lack of Standardization and Greenwashing Risks
One of the most significant challenges in the green finance market is the lack of global standardization in defining and verifying what qualifies as a “green” investment. The absence of universally accepted taxonomies and disclosure frameworks leads to inconsistent reporting, which creates confusion among investors and hinders comparability across financial products. For instance, the Climate Bonds Initiative and the Green Bonds Principles are commonly referenced taxonomies developed by international organizations, providing a foundation for various countries to establish their own green-bond listing guidelines. This fragmentation increases the risk of greenwashing-where companies misrepresent their environmental credentials to attract sustainable capital. Although several jurisdictions have introduced taxonomies and regulatory frameworks, the divergence in criteria across regions limits the efficiency of cross-border investments and undermines investor confidence. As a result, investors face difficulties in evaluating the authenticity and impact of green financial products, slowing market growth.
Data Gaps and Limited Access in Emerging Markets
Another critical challenge is the limited availability of reliable, consistent, and verifiable environmental data. Many companies, particularly in developing countries, lack the infrastructure or expertise to collect and report ESG metrics in line with international standards. This data gap affects risk assessment, impact measurement, and decision-making processes for investors. Additionally, small and medium-sized enterprises (SMEs) and businesses in emerging markets often face restricted access to green finance due to high due diligence requirements, perceived credit risks, and limited institutional capacity. Despite growing interest, capital flows remain concentrated in advanced economies, leaving a significant financing gap for sustainable development in low-income regions. Strengthening global data frameworks and incentivizing ESG disclosure can help bridge these gaps and create a more inclusive green finance ecosystem.
Market Opportunities:
The green finance market presents significant opportunities for stakeholders across the financial ecosystem, driven by the global transition toward a low-carbon economy. As climate goals become central to national agendas, the demand for green financial instruments such as green bonds, sustainability-linked loans, and ESG-focused investment funds is expected to rise sharply. Financial institutions have the opportunity to expand their portfolios by offering innovative products that align with environmental and social impact goals. Additionally, the growing emphasis on corporate sustainability presents a chance for banks and asset managers to support businesses in decarbonizing operations through tailored financial solutions. The integration of green finance into core strategies also allows investors to capture long-term value while managing climate-related risks more effectively.
Emerging markets represent another area of significant opportunity, as they require substantial funding for sustainable infrastructure, renewable energy, and climate adaptation. With proper risk mitigation tools and blended finance mechanisms, green finance can unlock capital flows into these underserved regions, contributing to inclusive and resilient growth. Furthermore, technological innovation, particularly in climate-focused fintech, offers new avenues for scaling green finance. Tools that enhance transparency, automate ESG reporting, and democratize access to sustainable investments can broaden investor participation and build market trust. As global regulatory alignment improves and public-private collaboration strengthens, the green finance market is well-positioned to accelerate capital deployment toward sustainable development goals while generating positive environmental, social, and economic outcomes.
Market Segmentation Analysis:
By Type
The green finance market is segmented by type into green bonds, green loans, and sustainability-linked instruments. Green bonds hold the largest market share, driven by their widespread adoption among governments and corporations for financing eco-friendly projects. Green loans are also gaining momentum, particularly among businesses seeking capital for energy efficiency and clean technology investments. Sustainability-linked instruments are emerging rapidly, offering flexibility by linking financial terms to a borrower’s environmental performance.
By Transaction
By transaction, the market is divided into investment, lending, and insurance. Investment dominates the segment, with asset managers and institutional investors increasingly allocating funds toward ESG-compliant portfolios. Green lending is expanding as banks incorporate sustainability criteria into credit decisions. The insurance segment is also evolving, with climate risk underwriting and green insurance products supporting sustainable development initiatives.
By End-User
The end-user segment includes governments, corporates, and individuals. Governments remain key drivers of green finance, issuing sovereign green bonds and implementing policy frameworks. Corporates are the fastest-growing segment, adopting green finance to meet regulatory expectations and stakeholder demands for sustainability. Individual investors are increasingly participating through ESG-focused funds and green investment platforms, contributing to broader market growth.
Segmentations:
By Type
- Green Bonds
- Green Loans
- Sustainability-Linked Bonds
- Sustainability-Linked Loans
- Mixed-Sustainability Instruments
- Investment
- Lending
- Underwriting
- Insurance Services
- Governments
- Corporations
- Financial Institutions
- Individuals
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe
Europe holds 45% of the global green finance market in 2024, making it the leading region. This dominance is driven by a well-established regulatory framework, including the EU Sustainable Finance Action Plan, the European Green Deal, and the EU Taxonomy Regulation. Countries such as Germany, France, and the Netherlands have developed advanced green bond markets and actively promote ESG integration across financial institutions. Strong policy support, investor awareness, and mandatory sustainability disclosures have further strengthened the region’s position as a global leader in green finance. Major European financial institutions are aligning their portfolios with net-zero targets, accelerating capital flows into clean energy and sustainable infrastructure. Additionally, the EU’s focus on cross-border green investment is fostering integration across member states and attracting international investors.
North America
North America accounts for 28% of the global green finance market, led by the United States and Canada. The region has seen significant growth due to rising ESG investment demand, increased corporate climate commitments, and evolving regulatory developments. The U.S. Securities and Exchange Commission’s climate-related disclosure proposals and Canada’s initiatives on sustainable finance taxonomy are influencing market behavior. Financial institutions, municipalities, and corporations are accelerating the issuance of green bonds and sustainability-linked instruments across key sectors such as energy, infrastructure, and technology. Private sector initiatives and investor coalitions are playing a crucial role in scaling sustainable finance across the continent. Furthermore, climate risk management and resilience planning are increasingly integrated into public and corporate financial strategies.
Asia-Pacific
Asia-Pacific holds 19% of the global green finance market and is recognized as a rapidly expanding region. China, Japan, South Korea, and India are at the forefront, backed by strong government support and national sustainability agendas. China has established one of the largest green bond markets globally, supported by public banks and strategic green development plans. Southeast Asian nations are also making progress through regional collaboration, regulatory reforms, and investment in climate-resilient infrastructure, making the region an important contributor to future green finance growth. Green finance hubs are emerging in key cities like Hong Kong, Singapore, and Tokyo, fostering innovation and regional cooperation. The rise of blended finance models is also enabling greater private sector participation in sustainable projects across developing economies in the region.
Key Player Analysis:
- BNP Paribas
- Clarity AI
- Starling Bank
- Stripe, Inc.
- Triodos Bank UK Ltd.
- Refinitiv
- KPMG International
- Arabesque Partners
- Goldman Sachs
- Pwc
- Acuity Knowledge Partners
- NOMURA HOLDINGS, INC.
Competitive Analysis:
The green finance market is highly competitive, with a mix of global financial institutions, development banks, asset managers, and fintech firms driving innovation and capital mobilization. Leading players such as HSBC, BNP Paribas, BlackRock, and JPMorgan Chase have integrated sustainability into their core strategies, offering a range of green bonds, ESG funds, and sustainability-linked instruments. Development institutions like the World Bank and the Asian Development Bank play a key role in de-risking green investments in emerging markets. Additionally, fintech startups are gaining traction by offering digital platforms for ESG analytics and green investment access. Competitive advantage is increasingly defined by a firm’s ability to demonstrate transparency, impact measurement, and alignment with global sustainability frameworks. Companies that invest in ESG data capabilities and product innovation are better positioned to capture rising demand. Strategic partnerships, regulatory compliance, and climate-focused investment strategies remain essential to maintaining competitiveness in this evolving market.
Recent Developments:
- In March 2025, Clarity AI launched an AI-driven solution to transform how asset managers and investors conduct sustainability research, enabling investment teams to take full control of their sustainability assessments.
- In October 2024, PwC announced a 71% reduction in Scope 1 and 2 greenhouse gas emissions from its FY19 baseline.
- In November 2023, Stripe launched Climate Orders, allowing businesses to pre-order carbon removal tons as part of its Stripe Climate initiative.
Market Concentration & Characteristics:
The green finance market exhibits moderate to high market concentration, with dominance by a few large global financial institutions, multilateral development banks, and regional leaders actively shaping market direction. These entities drive the issuance of green bonds, the structuring of sustainability-linked products, and the implementation of ESG investment strategies. The market is characterized by increasing regulatory alignment, rising investor demand for transparent and impactful financing, and the integration of environmental considerations into mainstream financial decision-making. Innovation is a defining characteristic, with the emergence of fintech solutions enhancing data accuracy, traceability, and investor accessibility. Despite growth, the market remains uneven across regions due to disparities in policy frameworks, capital availability, and ESG disclosure practices. Collaboration between public and private sectors is strengthening, and voluntary sustainability standards are gradually being integrated into formal regulations. The market continues to evolve rapidly, with a strong focus on accountability, data-driven reporting, and long-term environmental value.
Report Coverage:
The research report offers an in-depth analysis based on Type, Transection, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Green finance is expected to become a mainstream component of global financial systems, driven by increasing regulatory mandates and investor demand for sustainable assets.
- Governments will likely expand national green finance frameworks, supporting the development of climate-resilient infrastructure and low-carbon technologies.
- Financial institutions are projected to increase integration of ESG factors into lending, investment, and risk management practices.
- The adoption of digital tools such as AI, blockchain, and ESG data analytics will enhance transparency, monitoring, and impact reporting in green finance.
- Emerging markets are anticipated to attract higher levels of green capital through blended finance models and multilateral support.
- Corporate issuers are expected to scale up the issuance of green and sustainability-linked bonds to meet climate commitments and stakeholder expectations.
- Collaboration between public and private sectors will intensify to close financing gaps and support sustainable development goals.
- The development of standardized global taxonomies and reporting frameworks will improve comparability and reduce greenwashing risks.
- Retail participation in green finance is likely to rise through accessible digital investment platforms and green savings products.
- Green finance will play a critical role in driving the global transition toward a net-zero economy, aligning capital markets with long-term climate objectives.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Regulatory Support and Policy Frameworks
Comprehensive policy initiatives such as the EU Green Deal, SFDR, and national green bond standards are setting clear guidelines for sustainable investments, increasing transparency, and channeling capital toward environmentally responsible projects. These frameworks reduce greenwashing and encourage both public and private sector participation in green finance.
Growing Investor Demand for ESG-Compliant Portfolios
Institutional and retail investors are increasingly seeking financial products that deliver both returns and measurable environmental impact, driving the proliferation of green bonds, sustainability-linked loans, and ESG-focused funds. This shift is reinforced by rising shareholder activism and stakeholder expectations for corporate sustainability.
Technological Advancements in Fintech and Blockchain
Innovations such as AI-powered ESG analytics and blockchain-based verification platforms are improving the efficiency, transparency, and reliability of green finance transactions. These technologies facilitate better tracking, reporting, and democratize access to green investment opportunities, boosting investor confidence and market participation.
Corporate Climate Commitments and Risk Management
Corporations are setting ambitious net-zero targets and integrating sustainability into their operations, often in response to climate risk disclosures and frameworks like TCFD. This drives demand for green finance instruments to fund decarbonization, clean technology adoption, and climate resilience initiatives.
Expansion of Voluntary Carbon Markets and Transition Finance
The rise of voluntary carbon markets and transition finance instruments, such as sustainability-linked and transition bonds, is enabling high-emission sectors and emerging markets to access capital for climate-aligned projects. These tools support a pragmatic approach to decarbonization and broaden the scope of green finance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Green Finance Market?
What factors are driving the growth of the Green Finance Market?
What are the key segments within the Green Finance Market?
What are some challenges faced by the Green Finance Market?
Who are the major players in the Green Finance Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Green Bonds
- 1.2.2 Green Loans
- 1.2.3 Sustainability-Linked Bonds
- 1.2.4 Sustainability-Linked Loans
- 1.2.5 Mixed-Sustainability Instruments
- 1.3 By End-User
- 1.3.1 Governments
- 1.3.2 Corporations
- 1.3.3 Financial Institutions
- 1.3.4 Individuals
- 1.4 By Transaction
- 1.4.1 Investment
- 1.4.2 Lending
- 1.4.3 Underwriting
- 1.4.4 Insurance Services
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,068,250 million → 2032: USD 23,990,438.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Green Finance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Green Finance Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Green Finance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Green Finance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Green Finance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Green Finance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Green Finance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Green Finance Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,068,250 million → 2032: USD 23,990,438.28 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Green Finance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Green Bonds
- 12.3.6.2 Green Loans
- 12.3.6.3 Sustainability-Linked Bonds
- 12.3.6.4 Sustainability-Linked Loans
- 12.3.6.5 Mixed-Sustainability Instruments
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Governments
- 12.4.6.2 Corporations
- 12.4.6.3 Financial Institutions
- 12.4.6.4 Individuals
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Transaction - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Investment
- 12.5.6.2 Lending
- 12.5.6.3 Underwriting
- 12.5.6.4 Insurance Services
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Green Finance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Green Finance Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Green Finance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Green Finance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BNP Paribas
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Goldman Sachs
- 18.4 HSBC
- 18.5 BlackRock
- 18.6 JPMorgan Chase
- 18.7 Triodos Bank
- 18.8 Refinitiv
- 18.9 KPMG International
- 18.10 Stripe, Inc.
- 18.11 Arabesque Partners
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

