
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Green Tires Market Size 2024 | USD 12,775 million |
| Automotive Green Tires Market, CAGR | 4.40% |
| Automotive Green Tires Market Size 2032 | USD 18,028 million |
Market Overview
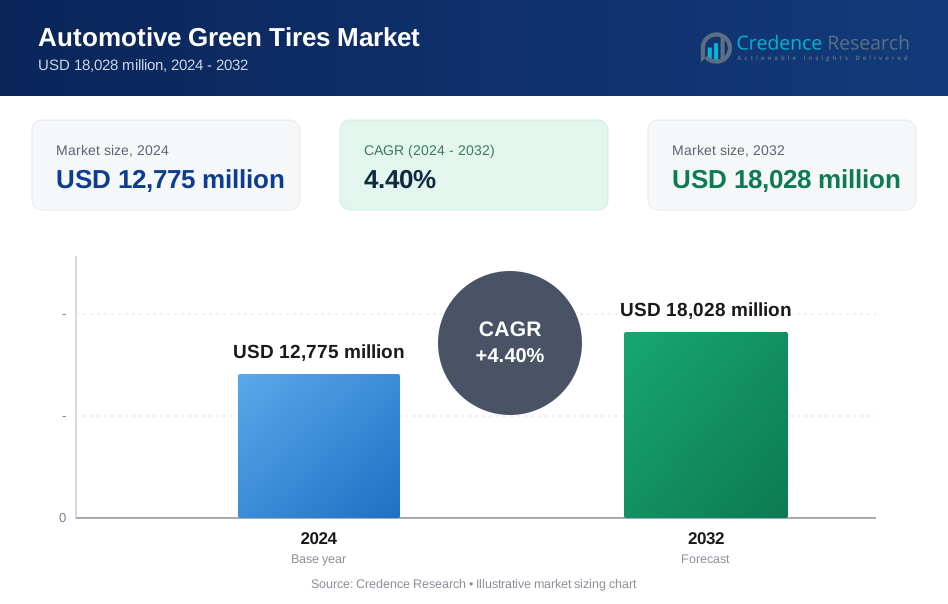
The automotive green tires market is projected to grow from USD 12,775 million in 2024 to USD 18,028 million by 2032, registering a CAGR of 4.40% during the forecast period.
The automotive green tires market is driven by rising environmental awareness, tightening emission regulations, and the growing demand for fuel-efficient vehicles. Consumers and automakers are increasingly favoring sustainable alternatives that reduce rolling resistance and improve mileage, supporting the widespread adoption of eco-friendly tire technologies. The shift toward electric and hybrid vehicles further accelerates demand, as these platforms prioritize energy efficiency and low-resistance components. Manufacturers are investing in innovative materials such as silica-reinforced rubber and bio-based polymers to enhance performance while minimizing environmental impact. The integration of smart tire technologies for pressure and tread monitoring also aligns with the broader trend toward intelligent mobility. Moreover, government incentives and policies promoting green mobility are encouraging the development and commercialization of sustainable tire solutions. OEMs are forming strategic alliances with tire manufacturers to co-develop models tailored to next-generation vehicles. As sustainability becomes a core automotive value, the market for green tires continues to expand across developed and emerging economies alike.
The automotive green tires market demonstrates strong geographical presence across Asia-Pacific, Europe, North America, and the Rest of the World, including Latin America, the Middle East, and Africa. Asia-Pacific leads the market due to rapid EV adoption and large-scale tire production, particularly in China, Japan, South Korea, and India. Europe follows with strict environmental regulations and widespread consumer demand for sustainable mobility. North America shows steady growth driven by federal incentives and rising EV usage. The Rest of the World is gradually expanding, supported by regulatory reforms and increased awareness. Key players operating globally include Michelin, Bridgestone, Continental AG, The Goodyear Tire & Rubber Company, Hankook Tire, Pirelli & C. S.p.A., Cheng Shin Rubber Ind. Co., Zhongce Rubber Group Co., Kumho Tire, and Nokian Tyres Plc, all of which are actively innovating and expanding their eco-friendly tire portfolios to address regional demands and environmental compliance.
Market Insights
- The automotive green tires market is expected to grow from USD 12,775 million in 2024 to USD 18,028 million by 2032, with a CAGR of 4.40%.
- Rising demand for fuel efficiency, lower emissions, and sustainable mobility is driving adoption of green tires globally.
- The shift toward electric and hybrid vehicles is creating strong demand for low rolling resistance and high-efficiency tire technologies.
- Tire manufacturers are investing in advanced materials like silica, natural rubber, and bio-based polymers to enhance performance and reduce environmental impact.
- Asia-Pacific leads with 34% market share, followed by Europe at 29%, North America at 21%, and the rest of the world at 16%.
- High production costs and limited consumer awareness remain key barriers, particularly for smaller manufacturers and in price-sensitive regions.
- Key players such as Michelin, Bridgestone, Continental, Goodyear, and Hankook are innovating through OEM collaborations and sustainability-focused product lines.
Market Drivers
Rising Demand for Fuel Efficiency and Lower Emissions
The automotive green tires market is driven by the global push to reduce carbon emissions and enhance fuel economy. Automakers and consumers alike are seeking solutions that improve mileage without compromising performance. Green tires reduce rolling resistance, directly improving vehicle fuel efficiency. This characteristic supports emission reduction targets and sustainability goals. Regulatory bodies worldwide are enforcing strict emission norms, further accelerating adoption. Tire manufacturers are innovating with advanced compounds to meet these evolving expectations.
- For instance, Goodyear’s Assurance Fuel Max tires are engineered to reduce rolling resistance and, according to internal company testing, can save up to 2,600 miles (4,000 km) worth of fuel over the life of four tires for an average vehicle.
Growth of Electric and Hybrid Vehicle Adoption
The rapid expansion of electric and hybrid vehicle fleets globally supports growth in the automotive green tires market. These vehicles require low-resistance, high-durability tires to optimize battery performance and extend driving range. Tire compatibility has become critical to EV efficiency, pushing manufacturers to redesign tread patterns and sidewalls. Governments offer tax incentives for EVs, indirectly driving demand for compatible green tires. OEMs are collaborating with tire producers for customized EV tire models. This synergy fosters long-term market development.
- For instance, Michelin has introduced the Pilot Sport EV tire, specifically designed for electric vehicles like the Tesla Model S, featuring a bespoke tread pattern and reinforced sidewalls that reduce energy loss and support heavier EV weights.
Increased Use of Sustainable Materials in Tire Manufacturing
Growing environmental consciousness is reshaping material sourcing strategies in the tire industry. The automotive green tires market benefits from the shift toward bio-based materials such as natural rubber, silica, and renewable oils. These inputs lower the carbon footprint of tire production and disposal. Consumers are showing a preference for environmentally responsible products. Tire companies are investing in R&D to enhance the performance of sustainable materials. These innovations make green tires both efficient and commercially viable.
Stringent Global Regulatory and Environmental Standards
Governments worldwide are implementing legislation that encourages greener automotive components. The automotive green tires market responds to these mandates by offering compliant, eco-friendly alternatives. Regulatory frameworks in Europe, North America, and parts of Asia promote sustainable transport solutions. These policies create a favorable landscape for green tire adoption. Industry players must align with evolving safety, emission, and recyclability standards. Regulatory pressure continues to drive technological advancements and influence procurement decisions across the automotive value chain.
Market Trends
Integration of Silica and Advanced Tread Compounds
Tire manufacturers are increasingly incorporating silica and next-generation polymers into green tire formulations. These materials reduce rolling resistance while improving wet grip and durability. The automotive green tires market benefits from this shift, as it supports both regulatory compliance and consumer expectations for safety. Advanced tread designs further enhance performance without compromising fuel efficiency. Companies are prioritizing low-heat generation compounds that extend tire life. This trend reinforces the market’s alignment with eco-efficiency and performance balance.
- For instance, Bridgestone and other major tire producers have adopted in-situ silica/silane technology in synthetic rubber compounds, achieving up to a 30% reduction in rolling resistance and a 15% increase in wet adhesion compared to conventional carbon black tires.
OEM Collaboration for Electric and Hybrid Vehicle Fitments
Original Equipment Manufacturers (OEMs) are forging strategic partnerships with tire companies to develop bespoke green tires for electric and hybrid vehicles. The automotive green tires market reflects this trend through the increased launch of model-specific tires optimized for low noise, high torque tolerance, and energy efficiency. OEMs prioritize lightweight tires with low rolling resistance to extend EV driving range. These collaborations support integrated product development. Custom tire solutions offer competitive advantages in a highly regulated and innovation-driven segment.
- For instance, BMW has collaborated with leading tire suppliers to introduce unique tires for its new European EV platform, co-developing solutions that reduce noise and rolling resistance while improving energy efficiency.
Rise of Circular Economy and Recycling Initiatives
Sustainability in the tire industry now extends beyond materials and into lifecycle management. The automotive green tires market is witnessing rising interest in recyclable materials and circular economy models. Manufacturers are exploring tire retreading, bio-derived inputs, and closed-loop recycling systems. Governments and environmental organizations advocate for end-of-life tire reuse standards. This trend encourages innovation in product design and post-use processing. Eco-labeling and traceability features are also gaining importance among environmentally conscious consumers and regulators.
Digitalization and Smart Tire Technologies
Digital transformation is influencing product development and aftermarket strategies in the green tire space. The automotive green tires market is embracing smart tire technologies that monitor pressure, tread wear, and temperature in real time. These features optimize tire performance, extend service life, and support predictive maintenance. Fleet operators benefit from data-driven efficiency improvements. Tire makers are integrating embedded sensors and IoT systems. This trend bridges sustainability with digital innovation and reinforces the market’s forward-looking trajectory.
Market Challenges Analysis
High Production Costs and Limited Consumer Awareness
The automotive green tires market faces challenges linked to higher production costs and limited end-user awareness. Advanced materials like silica and bio-based polymers, while effective, increase manufacturing expenses. Small and mid-sized manufacturers may struggle to scale due to cost-intensive R&D and raw material sourcing. Many consumers remain unaware of the long-term benefits of green tires, focusing instead on initial purchase price. Limited marketing and education around performance advantages hinder wider adoption. Bridging this gap requires strategic outreach and affordability improvements.
Complex Supply Chains and Material Sourcing Issues
Sourcing sustainable materials consistently across global supply chains poses a major challenge for the automotive green tires market. It depends on renewable inputs that are often subject to price volatility, regional availability, and climate-related disruptions. Ensuring quality, performance, and compliance across suppliers adds to operational complexity. Manufacturers must navigate evolving regulatory standards, which differ by region and complicate product standardization. It must also address logistical constraints in scaling eco-friendly tire components across international markets.
Market Opportunities
Rising Adoption of EVs and Government Incentives
The global shift toward electric mobility opens significant growth avenues for the automotive green tires market. EVs demand low rolling resistance and lightweight tire solutions to maximize battery efficiency. Governments are offering subsidies and tax incentives for eco-friendly vehicle components, including green tires. This regulatory push enhances market entry opportunities, especially for innovative startups. Tire manufacturers can tap into OEM collaborations to co-develop EV-optimized tires. The market stands to gain from expanding electric fleets across urban and fleet sectors.
Expansion in Emerging Markets and Sustainable Infrastructure
Emerging economies present untapped potential for the automotive green tires market due to rapid urbanization and increasing environmental regulations. Countries in Asia-Pacific, Latin America, and parts of Africa are strengthening sustainability frameworks and investing in green mobility. This creates demand for environmentally compliant automotive components. The growth of smart cities and eco-conscious transport infrastructure supports long-term market penetration. Tire makers can leverage regional partnerships and localize production to reduce costs and improve access. It can scale quickly with targeted product adaptation and distribution strategies.
Market Segmentation Analysis:
By Material Type
The automotive green tires market features a range of materials focused on reducing environmental impact and enhancing performance. Silica-based tires lead the segment due to their low rolling resistance and superior wet grip. Natural rubber-based tires hold a strong share owing to their biodegradability and reduced carbon footprint. Synthetic rubber-based tires provide durability and cost efficiency, making them popular in commercial applications. Bio-based tires are emerging as a niche yet promising category, driven by innovation in renewable inputs.
- For instance, Michelin sources natural rubber only from non-deforested areas and supports sustainable farming through the Global Platform for Sustainable Natural Rubber.
By Vehicle Type
The automotive green tires market serves multiple vehicle categories, with passenger cars accounting for the largest share. Consumers prioritize fuel efficiency and sustainability in personal vehicles, which boosts demand for eco-friendly tires. Light commercial vehicles are adopting green tires to optimize fleet performance and reduce fuel costs. Heavy-duty trucks and buses follow, supported by regulatory mandates for emission reduction. Off-road vehicles represent a growing segment, especially in agriculture and construction sectors seeking low-impact solutions.
- For example, Goodyear demonstrated tires with 90% eco-friendly materials, tested for lower rolling resistance and regulatory compliance, targeting the needs of logistics and delivery operators.
By Rim Size
Rim size plays a critical role in the application and performance of green tires. The 16”-18” segment dominates the automotive green tires market due to its compatibility with a wide range of passenger cars and SUVs. Tires in the 13”-15” category cater to compact cars and are favored for city driving. The 19”-21” and more than 21” segments are gaining momentum with luxury vehicles and performance EVs that demand optimized handling and efficiency with larger tire profiles.
Segments:
Based on Material Type
- Silica-based Tires
- Natural Rubber-based Tires
- Synthetic Rubber-based Tires
- Bio-based Tires
Based on Vehicle Type
- Passenger Car
- Light Commercial Vehicle
- Heavy Duty Trucks
- Buses and Coaches
- Off-road Vehicles
Based on Rim Size
- 13”-15”
- 16”-18”
- 19”-21”
- More than 21”
Based on Propulsion
- IC Engine
- Electric
Based on Sales Channel
- Original Equipment Manufacturers (OEMs)
- Aftermarket
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America North America captures 21% of the automotive green tires market, driven by stringent environmental standards and growing EV adoption. The United States leads the regional demand, supported by federal incentives and state-level emissions regulations. Major tire manufacturers are investing in sustainable production technologies and localizing supply chains. Fleet operators across the U.S. and Canada are integrating low-resistance tires to reduce fuel consumption. Consumer preference for eco-friendly vehicles supports strong aftermarket demand. Strategic OEM partnerships and growing awareness of sustainability will continue to influence market momentum.
Europe Europe accounts for 29% of the automotive green tires market, led by advanced regulatory frameworks and proactive sustainability mandates. Countries like Germany, France, and the Netherlands are setting benchmarks in fuel efficiency and green mobility adoption. Tire labeling regulations and eco-certifications influence consumer choices and product development. Companies in the region are leading innovation in bio-based compounds and recyclability. The rise in hybrid and electric vehicle registrations continues to stimulate demand. OEMs and tire firms are collaborating on next-generation tire designs suited for Europe’s evolving mobility ecosystem.
Asia-Pacific Asia-Pacific holds 34% of the automotive green tires market, making it the largest regional contributor. China, Japan, and South Korea are leading growth through large-scale EV adoption and national green transport policies. Local manufacturers are expanding capacity to meet rising domestic demand for sustainable tire solutions. Government incentives and investment in EV infrastructure support market growth. India is also emerging with favorable regulations and rising consumer awareness. The region benefits from strong OEM presence and growing partnerships in sustainable tire manufacturing.
Rest of the World The rest of the world represents 16% of the automotive green tires market, covering Latin America, the Middle East, and Africa. While infrastructure remains limited, policy reforms and interest in low-emission vehicles are gaining pace. Countries like Brazil and the UAE are investing in green mobility and EV adoption. Tire makers are entering these markets with localized strategies and pricing models. Awareness campaigns and pilot sustainability projects are improving market conditions. Gradual adoption across commercial and passenger vehicle segments presents long-term growth potential.
Key Player Analysis
- Hankook Tire
- Cheng Shin Rubber Ind. Co.
- Nokian Tyres Plc.
- Michelin
- Kumho Tire
- The Goodyear Tire & Rubber Company
- Zhongce Rubber Group Co.
- Continental AG
- Bridgestone
- Pirelli & C. S.p.A.
Competitive Analysis
The automotive green tires market is highly competitive, with key players focusing on material innovation, sustainability, and OEM collaborations. Companies like Bridgestone, Michelin, and Continental AG lead with strong R&D capabilities and global distribution networks. They invest in silica-based compounds, bio-materials, and energy-efficient manufacturing. Emerging players such as Zhongce Rubber Group and Cheng Shin Rubber are expanding through strategic partnerships and localized production. It rewards companies that align product performance with environmental compliance. Competitors are prioritizing electric vehicle tire solutions, reinforcing their relevance in a rapidly evolving mobility landscape. The market favors brands that deliver fuel efficiency, extended tire life, and lower rolling resistance without compromising safety. Manufacturers are also integrating digital technologies for performance monitoring and lifecycle tracking. Continuous investment in sustainable product lines and circular economy practices is shaping long-term competitiveness. Global expansion strategies and product differentiation remain essential to gain traction in mature and developing regions alike.
Recent Developments
- In July 2024, Michelin introduced a new green tire line made with 46% sustainable materials, including both renewable and recycled inputs, aiming to reduce its carbon footprint without compromising performance.
- In March 2024, GRI Tires launched the GREEN XLR EARTH series and ULTIMATE GREEN XT tires, both featuring high percentages of sustainable materials and reduced environmental impact.
- In 2023, JK Tyre and Industries unveiled an eco-friendly tire developed using recyclable and sustainable materials, reinforcing its commitment to low-impact tire innovation.
- In 2023, Bridgestone advanced its environmental roadmap by investing in AI-powered control systems to enhance manufacturing efficiency and optimize digital data utilization for achieving carbon neutrality by 2030.
Market Concentration & Characteristics
The automotive green tires market is moderately concentrated, with a mix of established global manufacturers and emerging regional players. It is characterized by strong emphasis on innovation, sustainability, and OEM collaboration. Leading companies maintain competitive advantage through investments in research and development, proprietary material technologies, and global distribution networks. The market rewards tire makers that align with evolving environmental regulations and performance standards. It exhibits moderate barriers to entry due to high capital requirements and the technical complexity of producing eco-friendly tires. Demand is driven by both original equipment and replacement sectors, with growing preference for fuel-efficient and low-resistance tires across all vehicle types. The market shows a clear shift toward silica-based and bio-material formulations, reflecting broader sustainability goals. It remains dynamic, with competition intensifying around electric vehicle compatibility, smart tire integration, and circular economy practices. Regional expansion, product diversification, and alignment with government incentives are key strategies shaping competitive positioning.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Vehicle Type, Rim Size, Propulsion, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Global EV adoption will drive consistent demand for green tires across personal and commercial vehicle segments.
- Manufacturers will expand use of bio-based polymers and silica to enhance tire sustainability and performance.
- OEMs will co-develop tire solutions tailored for electric and hybrid vehicle platforms to maximize efficiency.
- Government regulations will push automakers and suppliers toward stricter environmental tire performance standards.
- Rising consumer preference for sustainable products will influence tire replacement and upgrade decisions.
- Smart tire sensors will integrate with digital systems to monitor performance and improve vehicle efficiency.
- Developing regions will adopt green tires as part of broader sustainable transport infrastructure plans.
- Eco-friendly tire production processes will reduce emissions and resource consumption across global manufacturing sites.
- Competitive pressure will drive continuous R&D investment in next-generation green tire technologies.
- EV charging infrastructure growth will support green tire demand through aligned vehicle and component compatibility.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Emission Regulations and Environmental Standards
Governments worldwide are enforcing stricter emission norms and sustainability mandates, compelling automakers and tire manufacturers to adopt green tire technologies that reduce rolling resistance and environmental impact.
Growth of Electric and Hybrid Vehicle Adoption
The rapid expansion of electric and hybrid vehicle fleets increases demand for low-resistance, high-efficiency tires, as these vehicles require optimized tires to maximize battery range and overall energy efficiency.
Advancements in Sustainable Materials
Tire manufacturers are investing in R&D to incorporate silica, natural rubber, and bio-based polymers, which enhance tire performance while reducing the carbon footprint of both production and end-of-life disposal.
OEM and Tire Manufacturer Collaborations
Automotive OEMs are partnering with tire companies to co-develop green tires tailored for next-generation vehicles, especially EVs and hybrids, accelerating innovation and market penetration.
Government Incentives and Green Mobility Policies
Subsidies, tax incentives, and supportive policies for eco-friendly vehicles and components are encouraging both manufacturers and consumers to adopt green tires, particularly in regions prioritizing sustainable transport infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive green tires market?
What are the key segments within the Automotive green tires market?
What are some challenges faced by the Automotive green tires market?
Who are the major players in the Automotive green tires market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Rim Size
- 1.2.1 13”-15”
- 1.2.2 16”-18”
- 1.2.3 19”-21”
- 1.2.4 More than 21”
- 1.3 By Propulsion
- 1.3.1 IC Engine
- 1.3.2 Electric
- 1.4 By Vehicle Type
- 1.4.1 Passenger Car
- 1.4.2 Light Commercial Vehicle
- 1.4.3 Heavy Duty Trucks
- 1.4.4 Buses and Coaches
- 1.4.5 Off-road Vehicles
- 1.5 By Material Type
- 1.5.1 Silica-based Tires
- 1.5.2 Natural Rubber-based Tires
- 1.5.3 Synthetic Rubber-based Tires
- 1.5.4 Bio-based Tires
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,775 million → 2032: USD 18,028 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Green Tires Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Green Tires Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Green Tires Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Green Tires Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Green Tires Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Green Tires Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Green Tires Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Green Tires Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,775 million → 2032: USD 18,028 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Green Tires Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Rim Size - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 13”-15”
- 12.3.7.2 16”-18”
- 12.3.7.3 19”-21”
- 12.3.7.4 More than 21”
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Propulsion - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 IC Engine
- 12.4.7.2 Electric
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Car
- 12.5.7.2 Light Commercial Vehicle
- 12.5.7.3 Heavy Duty Trucks
- 12.5.7.4 Buses and Coaches
- 12.5.7.5 Off-road Vehicles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Material Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Silica-based Tires
- 12.6.7.2 Natural Rubber-based Tires
- 12.6.7.3 Synthetic Rubber-based Tires
- 12.6.7.4 Bio-based Tires
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Green Tires Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Green Tires Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Green Tires Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Michelin
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bridgestone
- 17.4 Continental AG
- 17.5 The Goodyear Tire & Rubber Company
- 17.6 Hankook Tire
- 17.7 Pirelli & C. S.p.A.
- 17.8 Cheng Shin Rubber Ind. Co.
- 17.9 Zhongce Rubber Group Co.
- 17.10 Kumho Tire
- 17.11 Nokian Tyres Plc
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

