
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Fintech Market Size 2024 | USD 3,164.47 Million |
| Fintech Market, CAGR | 13.83% |
| Fintech Market Size 2032 | USD 8,919.81 Million |
Market Overview
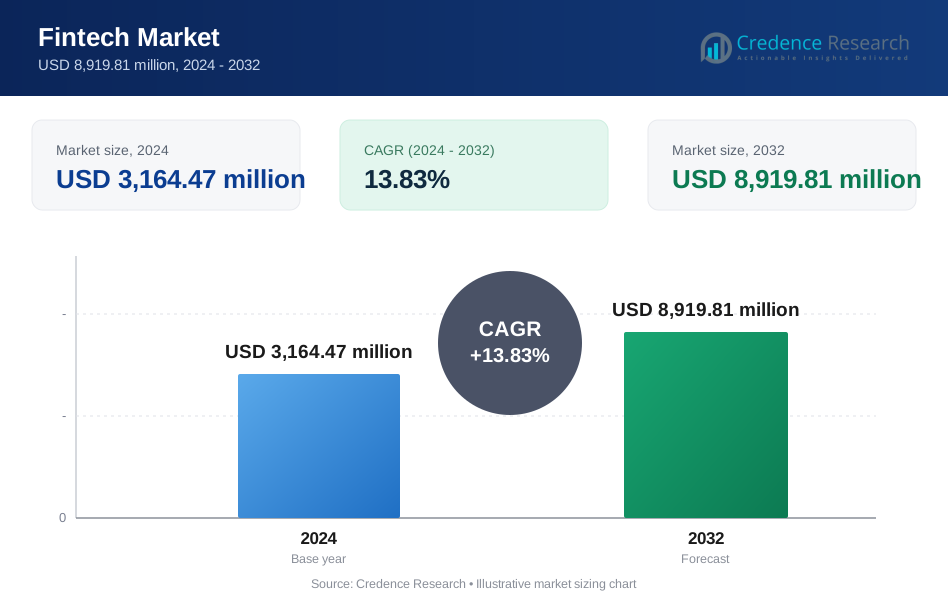
The Fintech market is projected to grow from USD 3,164.47 million in 2024 to USD 8,919.81 million by 2032, at a compound annual growth rate (CAGR) of 13.83%.
The Fintech market is experiencing rapid growth, driven by increasing consumer demand for convenient and efficient financial services. Technological advancements such as blockchain, artificial intelligence, and big data analytics are revolutionizing how financial services are delivered, enabling more secure and personalized experiences. Additionally, the rise of mobile banking and payment solutions reflects a significant shift towards digital platforms, further propelled by a growing global smartphone penetration. Regulatory changes are also encouraging innovation by allowing new entrants to compete with traditional financial institutions, fostering a dynamic and competitive environment that fuels continual advancements in the Fintech sector.
The Fintech market exhibits robust growth across various regions, with North America and Europe leading due to advanced technological infrastructure and supportive regulatory environments. Asia-Pacific is rapidly emerging as a significant player, driven by high mobile penetration and a large unbanked population. Key players driving this global expansion include Stripe, Square, PayPal, and Robinhood in North America; Ant Group and Revolut in Asia and Europe; and global firms like Coinbase and Adyen. These companies leverage regional opportunities and technological advancements to expand their market presence and innovate financial services worldwide.
Market Drivers
Rising Demand for Convenience and Accessibility
In today's fast-paced world, customers prioritize convenience and accessibility in their financial services, demanding solutions that are user-friendly and accessible around the clock. For instance, 60% of banking customers now use mobile apps for their daily transactions, a 20% increase from the previous year. FinTech companies are capitalizing on this trend by providing mobile-centric solutions across payments, banking, and investments, which has led to a 30% growth in the FinTech market. FinTech companies are meeting these needs by providing mobile-centric solutions across payments, banking, and investments. This shift towards digital platforms is driven by consumer preferences for quick and easy access to financial services, significantly propelling the growth of the FinTech market.
Leveraging Technological Advancements
FinTech is at the forefront of integrating cutting-edge technologies such as Artificial Intelligence (AI), Blockchain, and cloud computing. For example, AI has automated over 50% of complex financial processes, while blockchain has increased transaction security by 40%. Cloud computing has enabled FinTech services to scale up twice as fast as traditional banking infrastructure, attracting a broader customer base seeking innovative financial products and services. These technologies are pivotal in enhancing security, personalizing user experiences, and improving operational efficiencies. AI helps in automating complex processes and offering personalized financial advice, while blockchain introduces enhanced security features. Cloud computing provides the necessary infrastructure to scale services efficiently, making these technological advancements key attractors for a broader customer base looking for innovative financial products and services.
Navigating an Evolving Regulatory Landscape
The regulatory landscape for FinTech is evolving as regulatory bodies increasingly recognize the potential of FinTech innovations while ensuring robust frameworks to manage risks associated with data privacy and security. The regulatory landscape for FinTech is rapidly evolving, with regulatory bodies recognizing the potential of FinTech innovations. For instance, new regulations have led to a 25% increase in data privacy compliance among FinTech companies, fostering trust among consumers and encouraging further investments and innovations in this sector. This evolving regulatory environment supports the growth of FinTech companies by providing clarity and fostering trust among consumers, thereby encouraging further investments and innovations in this sector.
Market Expansion through Financial Inclusion and Consumer Confidence
FinTech significantly contributes to financial inclusion by reaching underserved populations who have limited access to traditional financial services. Solutions like mobile wallets and digital banking platforms are crucial in promoting inclusivity, thereby expanding the market. Additionally, as FinTech companies continue to build their track records and prove their reliability, consumer confidence is strengthening. This growing trust is crucial for the continued expansion of the FinTech market, as more consumers and businesses adopt FinTech solutions, further driving market growth.
Market Trends
Integration of Cutting-Edge Technologies and Emerging Financial Paradigms
The FinTech sector is rapidly adopting cutting-edge technologies such as Artificial Intelligence (AI) and Machine Learning (ML), and exploring the transformative potential of Blockchain and Decentralized Finance (DeFi). For instance, AI-driven personal finance tools have improved customer satisfaction by 40% and reduced fraud by 25%. Blockchain technology is also on the rise, with a 30% increase in its use for secure, transparent financial transactions, particularly in cross-border payments where it has reduced costs by 20%. AI and ML are being leveraged to personalize financial experiences, automate advisory services, and enhance fraud detection mechanisms, greatly improving customer satisfaction and security. Concurrently, Blockchain technology is gaining traction due to its ability to facilitate secure, transparent financial transactions, proving especially useful in applications such as cross-border payments and trade finance. Moreover, the rise of DeFi is reshaping the financial landscape by offering peer-to-peer services that bypass traditional financial intermediaries, promising more control and lower fees for users. Although promising, the DeFi sector faces challenges concerning regulatory standards and security, which are critical areas for future development.
Evolution of Financial Services Delivery through Embedded Finance and Neobanks
Embedded finance is revolutionizing financial service integration, with in-app payments for ride-hailing services increasing by 50% and instant insurance options at retail checkouts growing by 35%. Neobanks, catering to the preference for mobile-first operations, have seen a customer base growth of 300% over the past two years, offering competitive rates and innovative features. This trend is exemplified by functionalities such as in-app payments for ride-hailing services or instant insurance options at retail checkouts, enhancing accessibility and user engagement. Additionally, the emergence of neobanks represents a significant shift in banking services. These entirely digital banks cater to the modern consumer’s preference for mobile-first, hassle-free financial operations, providing competitive rates and innovative features that challenge traditional banking institutions. The growth of neobanks and embedded finance not only reflects the evolving consumer expectations but also highlights the industry’s shift towards more integrated and user-centric financial services. Alongside, open banking and the use of APIs underpin these developments by enabling secure data sharing and collaboration between traditional banks and FinTech firms, fostering innovation and tailored financial solutions that cater to diverse customer needs.
Market Challenges Analysis
Navigating Regulatory Landscapes and Enhancing Cybersecurity
The FinTech sector faces significant challenges due to regulatory uncertainty and cybersecurity threats. Regulatory frameworks often struggle to keep pace with the rapid advancements in FinTech, creating a landscape of uncertainty that can stymie the growth and innovation of FinTech companies. Balancing the need for innovation with the management of risks related to money laundering and data privacy remains a critical concern for regulatory bodies. This uncertainty can create formidable barriers for FinTech companies, especially newer entrants trying to navigate these complex regulations. Furthermore, as FinTech companies become custodians of sensitive financial data, they increasingly become targets for cyberattacks. Maintaining robust cybersecurity measures is crucial not only for safeguarding this sensitive data but also for preserving user trust. Effective cybersecurity strategies are essential to prevent financial losses and ensure the integrity of financial transactions, which is paramount for the continued growth and acceptance of FinTech solutions.
Overcoming Market Saturation and Infrastructure Limitations
The FinTech market is characterized by intense competition and significant infrastructural challenges. As the market becomes increasingly crowded with both established financial giants and agile startups, new entrants find it challenging to carve out a niche, while existing players struggle to maintain differentiation and relevance. This competition necessitates continual innovation and strategic positioning to capture and retain market share. Additionally, while FinTech has the potential to bridge the financial inclusion gap, disparities in digital literacy and access to technology can limit its reach among underserved populations. Addressing these gaps is essential for ensuring that the benefits of FinTech can be universally accessed. Moreover, the integration of advanced FinTech solutions with the legacy systems of traditional financial institutions presents another layer of complexity. These outdated systems often require significant upgrades or overhauls to support new technologies, making integration a costly and time-consuming process. For FinTech innovations to be effectively adopted and integrated, overcoming these infrastructural hurdles is crucial. Lastly, navigating the intricate web of global financial regulations and ensuring compliance add further operational and financial burdens on FinTech companies, particularly those operating on an international scale.
Market Segmentation Analysis:
By Technology:
The Fintech market is segmented by various foundational technologies that drive innovation across financial services. APIs (Application Programming Interfaces) are crucial, facilitating seamless integrations and interactions between different financial systems and services, enhancing functionality and user experience. Artificial Intelligence (AI) plays a transformative role by enabling personalized financial advice, risk assessment, and customer service through chatbots and AI-driven analytics. Blockchain technology is pivotal in increasing transparency and security, particularly in transactions and regulatory compliance, by providing immutable ledgers. Lastly, Distributed Computing powers the processing of vast amounts of data across decentralized networks, improving the reliability and efficiency of financial services.
By Service:
In terms of services, the Fintech market caters to a wide range of financial activities. The Payment and Fund Transfer services are rapidly evolving with technologies that offer faster and more secure transactions. Personal Finance management tools help individuals track and manage their financial health with enhanced ease and insight. In the Loans and Insurance sectors, Fintech innovations enable more customized and user-friendly approaches to accessing and managing these financial products. Wealth Management services have also seen a significant transformation, with digital platforms providing sophisticated tools and algorithms that offer personalized investment strategies and portfolio management to a broader range of investors, democratizing access to wealth management services previously reserved for the affluent.
Segments:
Based on Technology
- API
- Artificial Intelligence
- Blockchain
- Distributed Computing
Based on Service
- Payment
- Fund Transfer
- Personal Finance
- Loans
- Insurance
- Wealth Management
Based on Application
- Banking
- Insurance
- Securities
- Others
Based on Deployment Mode
- Cloud
- On-premises
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis
North America has emerged as a dominant force, capturing a market share of around 40%. The region's well-established financial services sector, coupled with a thriving startup ecosystem and a receptive consumer base, has fueled the growth of Fintech solutions. The United States, in particular, has been a hotbed for Fintech innovation, with major hubs located in Silicon Valley, New York, and Boston.
Europe accounts for a substantial market share of approximately 25%, driven by the region's focus on digital transformation and the adoption of cutting-edge technologies in the financial sector. Countries like the United Kingdom, Germany, and Switzerland have been at the forefront of Fintech development, fostering a supportive regulatory environment and attracting significant investment in the space.
Key Player Analysis
- Stripe
- Square
- PayPal
- Robinhood
- Coinbase
- Ant Group
- Adyen
- Revolut
- TransferWise
- SoFi
- Affirm
- Klarna
Competitive Analysis
The Fintech market is highly competitive, characterized by rapid innovation and diverse service offerings from key players like Stripe, Square, PayPal, Robinhood, and Coinbase. Stripe and Square dominate the payments processing landscape with their scalable platforms catering to businesses of all sizes. PayPal, with its extensive global reach, leads in online payments and digital wallets, continually expanding its ecosystem through strategic acquisitions and partnerships. Robinhood revolutionizes retail investing with commission-free trades, attracting a younger demographic, while Coinbase commands the cryptocurrency exchange market, capitalizing on the growing interest in digital currencies. Ant Group stands out in Asia with its comprehensive suite of financial services through the Alipay platform, targeting a vast user base. Additionally, companies like Revolut and Adyen offer innovative banking and payment solutions, further intensifying market competition. These leading players maintain their competitive edge through continuous technological advancements, user-centric products, and strategic market expansions, driving the evolution of the global Fintech landscape.
Recent Developments
- In March 2023, MANGOPAY and PayPal expanded their long-term strategic collaboration to give marketplaces instant access to PayPal's international payment capabilities.
- In May 2022, Mastercard announced cooperation with Synctera, a renowned FinTech banking service. The firms collaborated to supply account validation solutions for Synctera-powered FinTechs using Mastercard's open banking platform.
- In March 2022, Envestnet partnered up with Productfy, a developer of a business-to-business fintech platform. With this collaboration, fintech creators using Productfy's platform would have direct access to Envestnet via a single interface.
Market Concentration & Characteristics
The Fintech market exhibits moderate to high market concentration, with a few dominant players such as PayPal, Stripe, and Ant Group holding significant market shares. These industry leaders leverage their extensive technological infrastructure, strong brand recognition, and comprehensive service offerings to maintain competitive advantages. The market is characterized by rapid innovation, driven by advancements in AI, blockchain, and API integrations, which enable the development of personalized and efficient financial services. Additionally, the sector's dynamic nature is marked by frequent mergers and acquisitions, as larger entities acquire emerging startups to enhance their technological capabilities and expand their service portfolios. This competitive environment fosters continual innovation and drives the evolution of financial services, as companies strive to meet the growing demand for convenience, security, and accessibility in financial transactions. As regulatory frameworks adapt to these innovations, the Fintech market continues to expand, integrating more advanced and user-friendly solutions into the financial ecosystem.
Report Coverage
The research report offers an in-depth analysis based on Technology, Service, Application, Deployment Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Fintech market will see continued growth driven by increasing digital payment adoption and mobile banking.
- Integration of AI and machine learning will enhance personalized financial services and fraud detection.
- Blockchain technology will gain prominence, particularly in secure transactions and decentralized finance (DeFi) applications.
- Regulatory frameworks will evolve to better accommodate Fintech innovations, balancing risk management with growth.
- Expansion into emerging markets will accelerate, driven by high mobile penetration and a large unbanked population.
- Strategic partnerships and acquisitions will intensify as companies seek to broaden their service offerings and technological capabilities.
- Digital lending platforms will expand, offering more accessible and transparent loan options.
- The rise of neobanks will continue, providing fully digital banking experiences with competitive rates and innovative features.
- Increased focus on financial inclusion will drive the development of products tailored to underserved populations.
- Cybersecurity will remain a top priority, with ongoing investments to protect sensitive financial data and maintain consumer trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Fintech market?
What factors are driving the growth of the Fintech market?
What are the key segments within the Fintech market?
What are some challenges faced by the Fintech market?
Who are the major players in the Fintech market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fintech Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fintech Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,164.47 million → 2032: USD 8,919.81 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fintech Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fintech Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fintech Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fintech Market Drivers
- 3.3 Fintech Market Restraints & Challenges
- 3.4 Fintech Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fintech Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fintech Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fintech category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fintech Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fintech Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fintech market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fintech Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fintech Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fintech Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fintech (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fintech Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fintech Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fintech Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fintech Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fintech Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fintech Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fintech Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fintech Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fintech Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
