
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
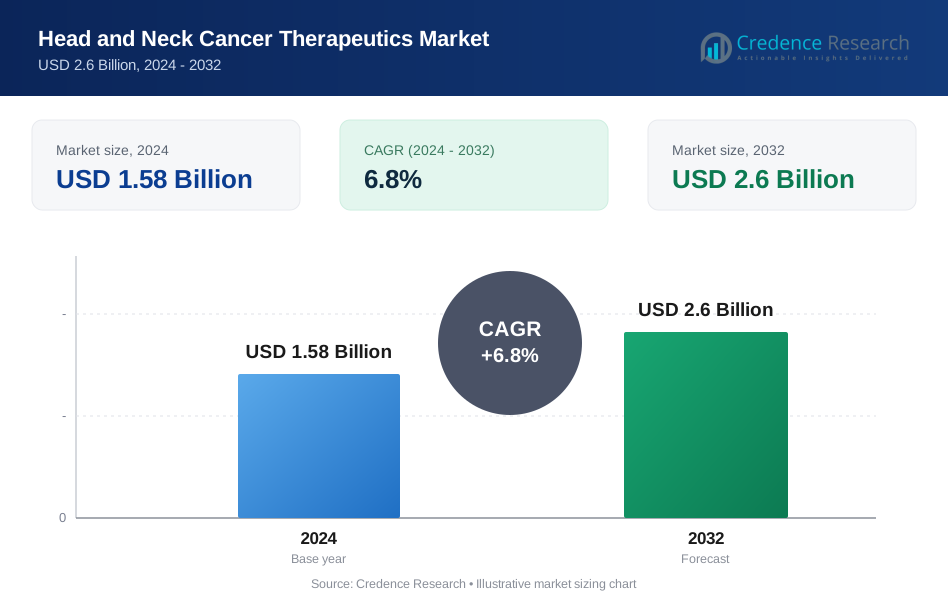
| Head and Neck Cancer Therapeutics Market Size 2024 | USD 1.58 Billion |
| Head and Neck Cancer Therapeutics Market, CAGR | 6.8%. |
| Head and Neck Cancer Therapeutics Market Size 2032 | USD 2.6 Billion |
Market Insights:
The head and neck cancer therapeutics market is projected to grow from USD 1.58 billion in 2024 to USD 2.6 billion by 2032, implying a CAGR of 6.8% over 2024–2032.
Market growth is associated with rising incidence of head and neck cancers and continued demand for more effective and tolerable treatment options. Risk factors commonly linked to these cancers include tobacco use, alcohol consumption, and human papillomavirus (HPV) infection, which can increase the treated patient base in some regions.
Treatment development is also shifting toward targeted therapies and immunotherapies, including checkpoint inhibitors and monoclonal antibodies, which in some indications can improve outcomes versus conventional chemotherapy and may offer different side-effect profiles. Increased pharmaceutical R&D investment and broader adoption of precision medicine approaches are supporting pipeline activity, while awareness programs and improvements in early detection can increase diagnosis rates and treatment uptake. Patient assistance programs and public funding for oncology can further support access, although coverage and affordability vary materially by country and payer system.
Regionally, North America accounts for the largest share, supported by higher use of advanced therapies, established oncology care pathways, and significant R&D activity. Europe follows, with demand supported by public healthcare coverage in many countries, oncology research funding, and screening and awareness initiatives. Asia-Pacific is positioned as the fastest-growing region, driven by a rising cancer burden and improving access to advanced therapies as healthcare infrastructure expands in markets such as India, China, and Japan. Latin America and the Middle East show steadier growth, linked to expanding oncology capacity and awareness efforts, though access constraints and uneven reimbursement can limit the pace of adoption.
Market Insights:
- The market is projected to grow from USD 1.58 billion in 2024 to USD 2.6 billion by 2032, implying a CAGR of 6.8% over 2024–2032.
- Rising diagnosis volumes for head and neck cancers, commonly associated with tobacco use, alcohol consumption, and HPV infection, continue to support demand for therapeutic interventions.
- Precision medicine adoption is expanding, supported by wider availability of genetic profiling and biomarker testing.
- North America is described as holding 40% of global market share, supported by higher uptake of advanced therapies, established oncology infrastructure, and sustained oncology R&D investment.
- Asia-Pacific is described as the fastest-growing region, linked to rising cancer burden, increasing healthcare investment, and broader access to advanced treatments in China, India, and Japan, although access remains uneven between urban and non-urban settings.
- Awareness campaigns, public funding, and patient support programs can increase diagnosis rates and treatment uptake, but the impact typically depends on local screening capacity, referral pathways, and reimbursement coverage.
Market Drivers:
Rising Prevalence of Head and Neck Cancers
Higher prevalence and diagnosis rates of head and neck cancers support demand for treatment. Tobacco use, alcohol consumption, and HPV infection are frequently cited risk factors. Some public health agencies report that HPV is associated with a large share of throat and mouth cancers, which can shift incidence patterns by subsite and geography.
These factors increase the treated population and can raise demand for therapies across first-line, recurrent, and metastatic settings. Population aging can further increase risk in many markets, which may expand the addressable patient base over time. However, treatment uptake and outcomes remain influenced by stage at diagnosis, access to specialized care, and affordability.
Advancements in Targeted and Immunotherapy Treatments
Targeted therapies and immunotherapies have expanded the treatment toolkit, particularly for recurrent or metastatic disease and for biomarker-defined subgroups. EGFR-directed approaches and monoclonal antibodies are used in certain regimens, and checkpoint inhibitors such as pembrolizumab have demonstrated survival benefits in selected patient populations.
These modalities can offer different efficacy and safety profiles compared with conventional chemotherapy, but clinical benefit varies and may be limited by primary or acquired resistance. Ongoing clinical trials and additional approvals continue to shape how these therapies are positioned in treatment pathways.
Increasing Focus on Precision Medicine
Precision medicine use is growing as genomic profiling and biomarker testing become more available in oncology workflows. Tools such as next-generation sequencing can help identify potentially actionable alterations and support treatment selection where evidence-based options exist.
This approach can improve the probability of treatment-response in certain subgroups and may reduce unnecessary exposure to ineffective therapies, but it can also increase upfront diagnostic costs. Adoption depends on testing reimbursement, turnaround time, and availability of therapies matched to identified biomarkers.
Government and Private Sector Initiatives
Public policy and private-sector activity support market development through awareness, screening, and investments in oncology capacity. Some programs include cancer screening and referral pathways within broader health coverage initiatives. Pharmaceutical companies also use collaborations and partnerships to accelerate development and improve market access. Public–private initiatives can support research and, in some cases, affordability measures, although coverage depth and real-world access differ materially by country.
Market Trends:
Growing Adoption of Immunotherapy
Immunotherapy is being used more widely in head and neck cancer care, particularly immune checkpoint inhibitors, with additional modalities (including cellular therapies) under active investigation. Interest is driven by the potential for durable responses in some patients, including those with recurrent or metastatic disease and those with limited benefit from conventional chemotherapy. However, outcomes vary by tumor subtype, biomarker status, prior treatment history, and patient fitness, and not all patients respond.
For instance, GeoVax has reported Phase 2 clinical work evaluating its gene therapy candidate Gedeptin in combination with pembrolizumab, with study objectives that include pathologic response endpoints in a defined patient cohort. This reflects ongoing efforts to expand immunotherapy-based strategies through combination and novel mechanisms.
Use of immunotherapy has expanded as clinical evidence and regulatory decisions have supported specific indications, and as clinician familiarity has increased. At the same time, real-world adoption is influenced by reimbursement, patient selection, toxicity management capacity, and access to multidisciplinary oncology care.
Integration of Artificial Intelligence in Oncology
AI tools are increasingly applied across oncology workflows, including biomarker discovery, response prediction research, and trial design support. In clinical settings, some of the most practical near-term applications are in imaging and radiotherapy planning, where automation can reduce repetitive tasks and improve workflow consistency. The impact on outcomes depends on local validation, quality control, and how well AI systems integrate into existing clinical processes.
For instance, an Allegheny Health Network study reported usability results for an AI-based autocontouring tool in head and neck radiotherapy planning, indicating improved planning efficiency and reduced contouring time under the study’s conditions. Results like these suggest operational benefits, although performance can vary by institution, imaging protocols, and clinician oversight.
AI-enabled diagnostics and monitoring tools are also being evaluated to support earlier detection and follow-up, but clinical utility depends on sensitivity, specificity, regulatory clearance, and adoption within standard pathways of care.
Increasing Emphasis on Combination Therapies
Combination regimens are a central development focus in head and neck cancer, with trials evaluating immunotherapy combined with chemotherapy, radiation, or targeted agents. The rationale is to improve response rates and address resistance mechanisms observed with single-agent approaches. Combination strategies can broaden the set of patients who benefit, but they can also increase toxicity, complexity of care, and cost, which may limit real-world uptake without clear net clinical benefit.
For instance, a Phase 2 study at Emory University reported outcomes for cabozantinib combined with pembrolizumab in recurrent or metastatic head and neck squamous cell carcinoma, including a high proportion of patients showing clinical benefit and a subset achieving partial responses. Findings such as these support continued investigation, although confirmation in larger, controlled studies is typically needed to establish routine use.
Overall, the shift toward combination approaches reflects attempts to optimize sequencing and synergy across modalities, with adoption likely to depend on comparative efficacy, safety, and payer coverage in specific indications.
Expansion of Telemedicine and Digital Health Solutions
Telemedicine and digital health tools are increasingly used to support access and continuity of care, particularly for follow-up visits, symptom checks, and coordination across specialists. These approaches can help patients in remote or underserved areas connect with oncology teams and can support monitoring of adherence and side effects during treatment. However, effectiveness depends on connectivity, digital literacy, and the ability to escalate to in-person evaluation when clinically necessary.
For instance, a systematic review identified studies using telemedicine to monitor head and neck cancer patients and reported improvements in patient engagement and self-management, particularly during the COVID-19 period when remote care expanded rapidly. While these findings indicate potential benefits, outcomes are influenced by program design, patient selection, and local healthcare capacity.
As these tools mature, they may improve care coordination and reduce some access barriers, but they are unlikely to fully offset constraints related to specialist availability, diagnostic infrastructure, and treatment affordability.
Market Challenges Analysis:
High Treatment Costs
High costs remain a key constraint in head and neck cancer therapeutics, particularly for newer modalities such as immunotherapy, targeted therapies, and precision-medicine approaches. Total cost of care can increase further when prolonged treatment duration is required and when biomarker testing, imaging, adverse-event management, and supportive care are added. These cost layers can limit adoption in price-sensitive markets and in settings with constrained reimbursement, even when clinical benefit is established. As a result, market uptake often concentrates in countries and payer systems with stronger coverage and oncology budgets.
Limited Access to Advanced Healthcare Infrastructure
Access to specialist oncology infrastructure remains uneven across and within regions. Limited availability of multidisciplinary cancer centers, radiotherapy capacity, pathology and biomarker testing, and trained oncology personnel can delay diagnosis and restrict access to advanced regimens. Rural and remote populations are more likely to face delayed presentation and treatment initiation due to weaker referral pathways and diagnostic capability. Late-stage diagnosis reduces the probability of curative intent treatment and can shift care toward more resource-intensive systemic therapy, which can further strain health systems.
Adverse Effects and Resistance to Therapies
While treatment options have expanded, toxicity remains a practical barrier in real-world use. Many regimens can cause adverse effects that reduce adherence, require dose modification, or increase supportive care needs, particularly in frail patients or those with comorbidities. In addition, resistance to targeted therapies and immunotherapies can limit durability of response and contribute to disease progression, increasing reliance on subsequent lines of therapy. Addressing resistance often requires combination strategies and additional clinical development, which raises R&D cost and can increase regimen complexity and total cost of care.
Regulatory and Approval Delays
Regulatory timelines can slow market expansion, particularly for novel mechanisms and combination regimens that require extensive evidence across safety, efficacy, and appropriate comparators. Long clinical development cycles and the need for mature endpoints can delay approvals, while post-approval requirements and real-world evidence expectations can influence labeling and reimbursement decisions. These factors can defer patient access to new therapies and increase development expense, which may reinforce pricing pressure and limit uptake in markets with strict cost-effectiveness thresholds.
Market Opportunities:
The increasing adoption of precision medicine represents a meaningful opportunity in head and neck cancer therapeutics, particularly where biomarker testing and genomic profiling are becoming more available. Improved identification of biomarkers and actionable alterations can support development of more targeted therapies and enable more selective treatment use.
This can improve response probability for certain patient subgroups and reduce exposure to less effective regimens. The scale of this opportunity depends on the breadth of validated biomarkers in head and neck cancers, test reimbursement, and the ability of health systems to integrate testing into routine pathways. Investments by governments and healthcare organizations in diagnostic infrastructure can accelerate adoption, but access is likely to remain uneven across regions and care settings.
Innovation in immunotherapy and combination regimens is another major opportunity, as clinical development increasingly evaluates checkpoint inhibitors with chemotherapy, radiotherapy, or targeted agents. Combination strategies aim to improve response rates and durability and to address resistance observed with single-agent approaches. These approaches may expand the treatable population, but their commercial potential will depend on demonstrable net benefit versus added toxicity and cost, as well as payer willingness to reimburse more complex regimens. Companies with strong clinical development capabilities and trial networks are better positioned to generate the comparative evidence needed for broader uptake.
Emerging markets also present expansion potential as oncology infrastructure improves and awareness increases, which can raise diagnosis rates and treatment uptake. However, near-term growth will likely be constrained by affordability, limited specialist capacity, and uneven access to biomarker testing and advanced drugs. Partnerships with local providers, staged market entry, and access programs may be important to translating demand into sales.
The Head and Neck Cancer Therapeutics Market is segmented by therapy type, route of administration, distribution channel, and region. By therapy type, chemotherapy remains widely used due to established protocols and availability, while immunotherapy and targeted therapy are growing faster in settings where clinical guidelines, biomarker testing, and reimbursement support their use. Advanced modalities are often positioned around improved efficacy in selected populations and different safety profiles, but their uptake varies by indication and line of therapy.
By route of administration, injectable therapies account for a large share because many oncology regimens are infusion-based and delivered in supervised settings. Oral therapies are expanding where suitable options exist and where monitoring and adherence support are in place, given their convenience for long-term management.
By distribution channel, hospital pharmacies typically hold the largest share because they support administration of complex regimens and coordinate supportive care in oncology centers. Retail and specialty pharmacies are important for dispensing oral oncology drugs and supportive medications, while online pharmacies are growing in certain markets where regulation, cold-chain logistics, and prescription verification support safe dispensing, particularly for refills and ongoing therapy supply.
Segmentation:
By Therapy Type:
- Chemotherapy
- Immunotherapy
- Targeted Therapy
By Route of Administration:
- Injectable
- Oral
- By Channel
By Retail & Specialty Pharmacies:
- Hospital Pharmacies
- Online Pharmacies
By Region:
- North America
- United States
- Canada
- Europe
- United Kingdom
- Germany
- France
- Asia-Pacific
- China
- India
- Japan
- Latin America
- Brazil
- Mexico
- Middle East and Africa
- South Africa
- United Arab Emirates
Regional Analysis:
North America is described as accounting for approximately 40% of global revenue, supported by established oncology infrastructure and higher uptake of advanced therapies. Use of pembrolizumab and nivolumab has influenced treatment patterns in eligible populations. Pipeline development is supported by public and private oncology research funding, while real-world access is shaped by reimbursement rules that vary by payer, indication, and line of therapy.
Europe is described as contributing around 30% of global share, supported by public health coverage in many countries, oncology research funding, and awareness initiatives that can increase diagnosis and referral. EU-level and national research programs support development of targeted and personalized approaches. Prevention measures, including vaccination, may influence long-term incidence, while near-term demand continues to be driven by the current diagnosed population and treatment eligibility.
Asia-Pacific is described as the fastest-growing region and about 20% of global revenue, supported by high case volumes and expanding access to oncology services. Growth is associated with expanding oncology capacity, increasing availability of advanced therapies in major urban centers, and rising clinical trial activity. However, access remains uneven across countries and between urban and rural areas, which can limit consistent uptake of biomarker testing and newer drugs.
Latin America and the Middle East & Africa are described as contributing about 10% combined and expanding steadily. In Latin America, demand is concentrated in larger markets such as Brazil and Mexico, where tobacco and alcohol use are relevant risk factors. Expansion of cancer care capacity and affordability programs can improve access, but coverage remains uneven. In the Middle East & Africa, investments in Gulf oncology services and selected African initiatives are improving access to diagnostics and treatment, while infrastructure gaps, workforce constraints, and reimbursement limitations continue to restrict broader adoption in many countries.
Key Player Analysis:
- AstraZeneca
- Bristol-Myers Squibb Company
- Clinigen Group plc.
- Coherus BioSciences.
- Eli Lilly and Company
- Hoffmann-La Roche Ltd.
- Merck & Co.
- Sanofi
- Takeda Pharmaceutical Company Limited
- Teva Pharmaceutical Industries Ltd
Competitive Analysis:
The market is competitive, with large pharmaceutical companies and biotechnology firms leading in immunotherapy and targeted therapy development. Companies such as Bristol-Myers Squibb and Merck have established checkpoint inhibitor franchises that are used in eligible head and neck cancer settings, supported by broad clinical development programs and global commercialization capabilities.
Pipeline competition includes efforts in combination regimens, biomarker-driven strategies, and novel immune approaches. Strategic partnerships, licensing, and M&A remain common tools to expand portfolios and accelerate development timelines. Regional firms contribute through local trials, biosimilar development, and cost-positioned offerings, which can increase price pressure and expand access in some markets.
Recent Developments:
- In December 2024, the EMA's CHMP approved six biosimilars, including Celltrion's Eydenzelt®, Osenvelt®, Stoboclo®, and Avtozma®, as well as Biocon's Yesintek® and CuraTeQ's Zefylti®. Between July and November 2024, Europe saw the launch of three ustekinumab biosimilars-STADA/Alvotech's Uzprovo®, Sandoz's Pyzchiva®, and Celltrion's SteQeyma®-joining earlier approvals like Formycon's Otulfi®, Samsung Bioepis' Eksunbi™, and Amgen's Wezenla™.
- In China, GSK submitted a new drug application to the NMPA for Blenrep® with BorDex to treat relapsed or refractory multiple myeloma. On December 9, 2024, Formycon and MS Pharma announced plans to commercialize FYB202, a Stelara® biosimilar, in the Middle East and North Africa.
Market Concentration & Characteristics:
The Head and Neck Cancer Therapeutics Market exhibits a moderately concentrated structure, with a few global pharmaceutical companies holding a significant share due to their advanced therapies and extensive R&D investments. Market leaders such as Merck & Co., Bristol Myers Squibb, and AstraZeneca dominate through innovations in immunotherapy and targeted treatments. Their well-established distribution networks and strategic collaborations with research institutions solidify their market position.
Emerging players and regional firms contribute to market diversity by focusing on cost-effective solutions and niche therapeutic segments, such as precision medicine and combination therapies. The market is characterized by rapid advancements in treatment modalities, a growing emphasis on personalized medicine, and increasing investments in clinical trials. High regulatory requirements for drug approvals and significant R&D costs present barriers to entry, while the rising adoption of innovative technologies underscores the market's dynamic and competitive nature.
Report Coverage:
The research report offers an in-depth analysis based By Therapy Type, By Route of Administration and By Retail & Specialty Pharmacies. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints.
Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Head and Neck Cancer Therapeutics Market?
What drives the market's growth?
Which region holds the largest market share?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Head and Neck Cancer Therapeutics Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Head and Neck Cancer Therapeutics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.58 Billion → 2032: USD 2.6 Billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Head and Neck Cancer Therapeutics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Head and Neck Cancer Therapeutics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Head and Neck Cancer Therapeutics Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Head and Neck Cancer Therapeutics Market Drivers
- 3.3 Head and Neck Cancer Therapeutics Market Restraints & Challenges
- 3.4 Head and Neck Cancer Therapeutics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Head and Neck Cancer Therapeutics Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Head and Neck Cancer Therapeutics Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Head and Neck Cancer Therapeutics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Head and Neck Cancer Therapeutics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Head and Neck Cancer Therapeutics Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Head and Neck Cancer Therapeutics. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Head and Neck Cancer Therapeutics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Head and Neck Cancer Therapeutics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Head and Neck Cancer Therapeutics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Head and Neck Cancer Therapeutics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Head and Neck Cancer Therapeutics
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Head and Neck Cancer Therapeutics Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Head and Neck Cancer Therapeutics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Head and Neck Cancer Therapeutics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Head and Neck Cancer Therapeutics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Head and Neck Cancer Therapeutics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Head and Neck Cancer Therapeutics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Head and Neck Cancer Therapeutics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Head and Neck Cancer Therapeutics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
