
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Honey Food Market Size 2024 | USD 8990 million |
| Honey Food Market, CAGR | 5.18% |
| Honey Food Market Size 2032 | USD 13465.57 million |
Market Overview:
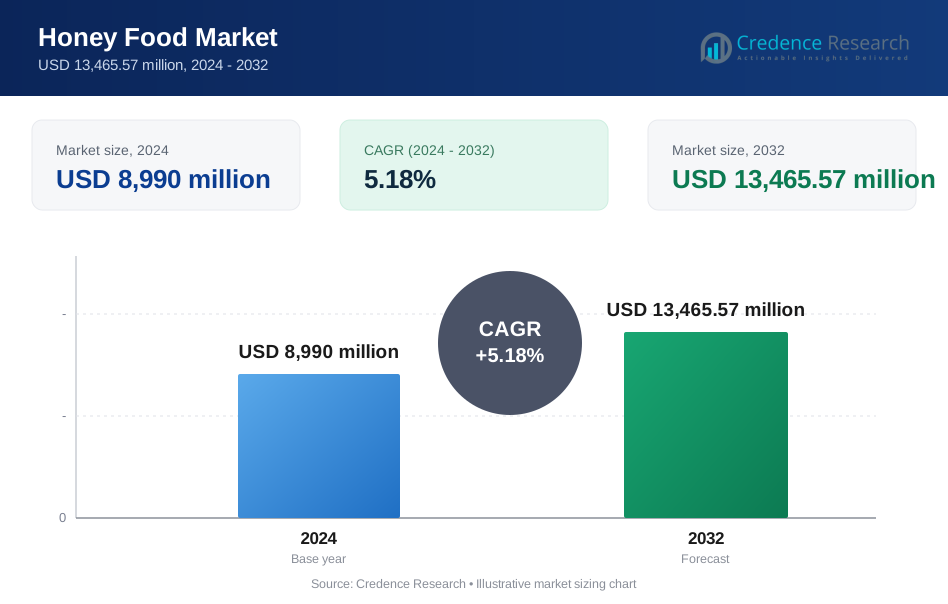
The Global Honey food Market size was valued at USD 8990 million in 2024 and is anticipated to reach USD 13465.57 million by 2032, at a CAGR of 5.18% during the forecast period (2024-2032).
Several key drivers are propelling the honey market's growth. A significant factor is the increasing consumer shift towards natural and healthier alternatives to refined sugar, driven by rising health consciousness and awareness of honey's nutritional benefits, including its antioxidant properties. Additionally, honey's versatile applications in the food and beverage industry, such as in bakery products, beverages, and as a flavor enhancer, contribute to its heightened demand. The cosmetic and pharmaceutical sectors also utilize honey for its antimicrobial and moisturizing properties, further bolstering market expansion. The growing popularity of functional foods and the increasing application of honey in traditional medicines are also influencing market growth. Furthermore, rising investments in sustainable beekeeping practices are enhancing production quality and volume.
Regionally, Asia Pacific holds a dominant position in the global honey market, primarily due to large-scale production and consumption in countries like China and India. China leads the region with substantial honey production, accounting for a significant share of global output. The region's growth is also supported by traditional dietary preferences and increasing awareness of honey's health benefits. Europe follows, with strong consumer preference for natural and organic products driving market expansion. The demand for premium honey varieties and strict quality standards further support the region’s growth trajectory. In North America, the market is bolstered by a growing number of beekeepers and increasing demand for natural sweeteners. The presence of diverse honey varieties and rising consumer awareness about the health benefits of natural sweeteners contribute to market development. Additionally, government initiatives supporting local beekeeping industries are positively impacting regional growth. The expansion of online retail channels is further enhancing honey's market penetration across various geographies, making it more accessible to a broader consumer base.
Market Insights:
- The global honey market was valued at USD 8,990 million in 2024 and is anticipated to reach USD 13,465.57 million by 2032, growing at a CAGR of 5.18% during the forecast period (2024-2032).
- Honey’s versatility in the food and beverage industry, particularly in bakery products and beverages, is significantly boosting its market demand.
- Expanding applications in the pharmaceutical and cosmetic sectors, due to honey's antimicrobial and moisturizing properties, are contributing to market growth.
- Rising investments in sustainable beekeeping practices are enhancing honey production quality and volume, supporting long-term market sustainability.
- Asia Pacific dominates the global honey market, supported by large-scale production and growing consumer awareness about honey's health benefits.
- Europe’s focus on organic and high-quality honey varieties, along with strict regulations, is enhancing market stability and consumer trust.
- North America’s market growth is fueled by increasing demand for natural sweeteners, the adoption of advanced beekeeping practices, and the expansion of e-commerce platforms.
Market Drivers:
Rising Consumer Preference for Natural and Healthier Sweeteners
The global honey market is experiencing significant growth, primarily driven by a shift in consumer preferences toward natural and healthier alternatives to refined sugar. As awareness of health issues such as obesity and diabetes increases, consumers are actively seeking natural sweeteners like honey, which offers not only sweetness but also nutritional benefits. For instance, the National Honey Board reports that honey's use in non-alcoholic beverages and functional drinks is particularly noteworthy, as consumers seek flavorful, nutrient-rich options. Honey contains antioxidants, vitamins, and minerals, making it a favorable choice among health-conscious individuals. This trend is evident in the U.S., where honey consumption has risen by 36% over the past decade, reaching 618 million pounds in 2021.
Expanding Applications in the Food and Beverage Industry
Honey's versatility has led to its widespread adoption in the food and beverage sector. It serves as a natural sweetener and flavor enhancer in various products, including bakery items, beverages, and sauces. For instance, companies like Nature's Path use honey in their granola bars to enhance flavor and provide a natural energy source. The food industry accounts for 80% of honey consumption worldwide, reflecting its integral role in culinary applications. Additionally, honey's natural properties, such as its ability to act as a preservative due to its antimicrobial characteristics, make it a valuable ingredient in extending the shelf life of food products.
Increasing Utilization in Pharmaceuticals and Cosmetics
Beyond its culinary uses, honey's medicinal and therapeutic properties have been recognized and utilized in the pharmaceutical and cosmetic industries. Its antibacterial and anti-inflammatory attributes make it a common component in cough syrups and topical ointments. In the cosmetic industry, honey is valued for its moisturizing and soothing properties, leading to its inclusion in products like facial masks, lotions, and hair conditioners. The growing consumer inclination toward natural and organic personal care products has further propelled the demand for honey in these sectors.
Technological Advancements and Sustainable Beekeeping Practices
Technological innovations in honey extraction and processing have enhanced production efficiency and quality. Improved extraction techniques have increased yield, meeting the rising global demand. Additionally, sustainable beekeeping practices have gained prominence, addressing environmental concerns and ensuring the health of bee populations. Initiatives supporting beekeepers, such as the USDA's Emergency Assistance for Livestock, Honeybees, and Farm-raised Fish Program (ELAP), provide compensation for losses due to adverse conditions, bolstering the industry's resilience.
Market Trends:
Growing Demand for Natural Sweeteners
The honey market is experiencing significant growth driven by the increasing consumer preference for natural sweeteners over refined sugars. For instance, a survey by the National Honey Board highlights consumer preference for honey due to its natural origin and additional nutritional benefits, such as antioxidants and vitamins. Honey is favored for its additional nutritional benefits, including antioxidants, vitamins, and minerals. Health-conscious consumers are incorporating honey into their diets as a natural alternative, aligning with the broader trend of adopting healthier lifestyles.
Technological Advancements and Sustainable Practices
Technological advancements in honey extraction and processing have significantly improved production efficiency and yield. For example, the Rainforest Alliance promotes sustainable beekeeping practices that address environmental concerns while supporting the long-term health of bee populations. Enhanced extraction techniques are enabling higher output to meet growing demand. Additionally, sustainable beekeeping practices are gaining traction, addressing environmental concerns and ensuring the long-term health of bee populations. These practices contribute to ecological balance and ensure the consistent availability of high-quality honey.
Product Innovation and Diversification
Product innovation is a notable trend shaping the honey market. Manufacturers are introducing diverse honey-based products, such as energy gels, spreads, and infused honey varieties, to cater to evolving consumer preferences. Such innovations are expanding honey’s application across multiple sectors.
Rise of E-commerce and Direct-to-Consumer Sales
E-commerce has emerged as a vital distribution channel for honey products. The convenience of online shopping and access to a broader range of specialty and artisanal honey varieties have driven increased consumer engagement. Producers are focusing on strengthening their online presence and enhancing direct-to-consumer sales strategies to reach a wider customer base and adapt to changing purchasing behaviors.
Market Challenges Analysis:
Environmental and Biological Threats
The honey industry confronts significant challenges from environmental and biological factors that threaten bee health and, consequently, honey production. Parasites such as the Varroa destructor mite pose a severe risk to bee colonies by feeding on bees and transmitting lethal viruses, leading to substantial colony losses. Additionally, exposure to pesticides and herbicides compromises bee immunity and foraging behavior, further exacerbating colony decline. Climate change introduces unpredictable weather patterns, affecting the availability of floral resources essential for nectar collection. Moreover, habitat loss due to urbanization and agricultural expansion limits bees' access to diverse floral sources, reducing honey yield. The decrease in bee populations not only threatens honey production but also impacts broader agricultural ecosystems due to bees' role in pollination. Addressing these issues necessitates collaboration between governments, agricultural sectors, and environmental organizations to promote bee-friendly practices and reduce harmful chemical usage.
Market Dynamics and Economic Pressures
The honey market also faces challenges stemming from economic pressures and market dynamics. The prevalence of honey adulteration undermines consumer trust and affects the market value of genuine honey products. For instance, a recent authenticity test revealed that over 90% of honey samples from UK retailers were suspect, highlighting the widespread issue of adulteration. Additionally, global competition and the influx of low-cost honey imports can distort pricing structures, affecting local producers' profitability. Supply chain disruptions, such as those experienced during the COVID-19 pandemic, have led to increased costs and logistical challenges for honey producers. Moreover, the lack of standardized global regulations regarding honey quality intensifies market disparities, complicating international trade. These economic pressures necessitate robust regulatory frameworks and innovative solutions to ensure the sustainability and profitability of the honey industry. Strengthening traceability systems and promoting fair-trade certifications can further enhance product credibility and market stability.
Market Opportunities:
The honey market presents significant growth opportunities driven by evolving consumer preferences and expanding applications across various industries. Increasing consumer inclination towards natural and organic products has positioned honey as a preferred alternative to refined sugars and artificial sweeteners. The rising awareness of honey’s nutritional benefits, including its antioxidant and antimicrobial properties, creates further demand in the food and beverage sector. Moreover, the growing trend of health and wellness has led to an increased consumption of honey in functional foods and beverages, catering to consumers seeking natural energy sources and immune-boosting ingredients. This shift is encouraging manufacturers to develop innovative honey-infused products, such as health drinks, snacks, and spreads, thereby enhancing product diversity and market reach.
In addition to its culinary applications, honey’s expanding use in the pharmaceutical and cosmetic industries presents lucrative opportunities. The demand for natural and organic personal care products is increasing, with honey being widely utilized in skincare and haircare formulations due to its moisturizing and healing properties. Furthermore, the pharmaceutical sector is leveraging honey’s medicinal qualities for the development of natural remedies and therapeutic products. Growing global interest in sustainable and ethical sourcing is also shaping market opportunities, with consumers increasingly favoring products from responsible beekeeping practices. The rise of e-commerce platforms and direct-to-consumer sales channels further enhances market potential by providing producers access to a broader audience. Leveraging these trends, companies can expand their market presence by focusing on product innovation, sustainable sourcing, and enhanced digital strategies.
Market Segmentation Analysis:
By Type
The honey market is segmented by type into wildflower honey, clover honey, buckwheat honey, and others. Wildflower honey holds a significant share due to its unique flavor profile and widespread availability. Clover honey is also popular, especially in North America, due to its mild taste and versatility in culinary applications. Specialty honey types, such as manuka honey, are gaining traction due to their distinct health benefits, offering premium opportunities for market expansion.
By Application
In terms of application, the food and beverage sector dominates the market, with honey being extensively used as a natural sweetener, flavor enhancer, and preservative in bakery products, beverages, and sauces. The pharmaceutical segment is expanding due to honey’s antibacterial and anti-inflammatory properties, which make it a key ingredient in medicinal formulations. The cosmetics industry is also witnessing increased demand for honey, driven by its moisturizing and healing attributes in skincare and haircare products.
By Packaging
The packaging segment is categorized into jars, bottles, tubs, and others. Bottles are the most preferred packaging type due to convenience, ease of use, and extended shelf life. Jars are favored for premium and artisanal honey varieties, enhancing product presentation. Sustainable and eco-friendly packaging options are also gaining attention, aligning with consumer demand for environmentally responsible products.
Segmentations:
- By Type
- Wildflower Honey
- Clover Honey
- Buckwheat Honey
- Alfalfa Honey
- Manuka Honey
- Acacia Honey
- Others
- By Application
- Food and Beverage
- Pharmaceuticals
- Cosmetics and Personal Care
- Foodservice Industry
- Others
- By Packaging
- Glass Jars
- Plastic Bottles
- Tubs
- Sachets
- Others
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
Asia Pacific
Asia Pacific dominates the global honey market, holding a market share of 38%. China is the largest producer in this region, contributing 444,000 metric tons of honey, accounting for a significant portion of global production. The region's market growth is driven by traditional dietary practices that incorporate honey and the increasing awareness of its health benefits. Rising disposable incomes and urbanization in countries like India and China are further propelling the demand for natural sweeteners, solidifying Asia Pacific's position as a key market for honey products. Additionally, the expansion of commercial beekeeping and government initiatives promoting sustainable agricultural practices are enhancing production capabilities. The increasing demand for premium and organic honey varieties is encouraging local producers to invest in quality enhancement. Furthermore, the growth of e-commerce platforms is facilitating wider market access for honey manufacturers across the region.
Europe
Europe holds a substantial 28% share of the global honey market, with Ukraine and Spain leading in production. Ukraine produces 69,940 metric tons of honey, while Spain contributes 37,000 metric tons. European consumers exhibit strong preferences for natural and organic products, fueling the demand for high-quality honey. Strict quality standards and regulations ensure product authenticity, enhancing consumer trust and market growth. Additionally, the region's emphasis on sustainable farming practices aligns with the growing trend for ethically sourced products. Increasing demand for locally produced honey is driving small-scale production initiatives. Moreover, the presence of various artisanal and specialty honey brands is further diversifying the European market landscape.
North America
North America accounts for 22% of the global honey market, with the United States as a major contributor. The U.S. produces 71,180 metric tons of honey. The market is characterized by increasing consumer preference for natural and healthier food alternatives, which has boosted honey consumption. Honey’s versatility in various food applications and its health benefits have led to its greater incorporation into daily diets. The adoption of advanced beekeeping technologies is enhancing productivity and honey quality across the region. Additionally, growing awareness of pollinator health is fostering community initiatives supporting sustainable beekeeping. The rising trend of gourmet and flavored honey products is also contributing to market diversification and growth.
Key Player Analysis:
- Dabur India Ltd.
- Dutch Gold Honey
- New Zealand Honey Co.
- Capilano Honey
- Savannah Bee Company
- Rowse Honey
- Honey Care Africa
- Honningcentralen
- Barkman Honey
- Nature Nate's
- Sandt's Honey Co.
- Jamie's Hive-to-Table
Competitive Analysis:
The global honey market is characterized by intense competition, with key players focusing on product innovation, quality enhancement, and sustainable practices to strengthen their market positions. Leading companies such as Dabur India Ltd., Dutch Gold Honey, and Capilano Honey prioritize offering high-quality, natural honey products to meet evolving consumer demands. For example, Dabur India Ltd. has expanded its product portfolio to include specialty honey varieties infused with herbs, catering to health-conscious consumers.
Companies are investing in sustainable beekeeping practices and expanding product portfolios to include organic, raw, and specialty honey varieties. Strategic collaborations, mergers, and acquisitions are also prevalent, enabling companies to enhance their global presence and distribution networks. Additionally, e-commerce platforms are becoming a critical sales channel, prompting companies to strengthen their digital strategies. The competitive landscape is further shaped by stringent quality regulations, pushing manufacturers to maintain product authenticity. Overall, market players are leveraging innovation, sustainability, and strategic partnerships to gain a competitive edge and capture greater market share.
Recent Developments:
- In March 2025, Dutch Gold Honey was acquired by New Water Capital Partners II L.P., a private equity investment firm. This acquisition is expected to accelerate Dutch Gold's growth through additional investments in capacity, operational systems, and organizational resources.
- In 2023, New Zealand Honey Co. was recognized as one of the major key players in the global honey market, contributing to the market's growth and innovation.
- In 2023, Rowse Honey was identified as one of the leading players in the global Organic Honey Market, contributing to the market's growth and innovation.
Market Concentration & Characteristics:
The global honey market is moderately fragmented, characterized by the presence of several key players alongside numerous small and regional producers. Major companies such as Dabur India Ltd., Dutch Gold Honey, and Capilano Honey hold significant market shares, while local producers contribute to regional diversity. The market is defined by a strong emphasis on product authenticity, quality standards, and sustainable sourcing. Increasing consumer demand for organic, raw, and natural honey is driving producers to innovate and diversify their offerings. Sustainable beekeeping practices and adherence to quality regulations are becoming essential characteristics for market participants. Additionally, the rise of e-commerce and direct-to-consumer sales is reshaping distribution channels, enhancing market accessibility. The market's competitive nature encourages continuous product development, packaging innovation, and strategic partnerships, positioning companies to meet evolving consumer preferences while maintaining strong brand credibility.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, Packaging and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for natural and organic honey products is expected to increase as consumers prioritize healthier and sustainable food choices.
- Technological advancements in beekeeping and honey extraction are likely to enhance production efficiency and product quality.
- Innovations in product offerings, including flavored and infused honey varieties, will drive diversification and cater to evolving consumer preferences.
- The food and beverage sector will continue to be the largest consumer of honey, particularly in bakery, confectionery, and beverage products.
- The cosmetic and pharmaceutical industries will expand their use of honey, leveraging its natural antibacterial and moisturizing properties.
- Sustainable and ethical beekeeping practices will gain greater importance, driven by environmental concerns and consumer awareness.
- E-commerce and direct-to-consumer sales channels will play a significant role in expanding market reach and accessibility.
- Increased government initiatives and support for local beekeepers will promote sustainable production and industry growth.
- The rising popularity of premium and artisanal honey products will create new opportunities for small and regional producers.
- Strategic collaborations, mergers, and acquisitions will be key strategies for companies seeking to strengthen their market presence and expand globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global honey market?
What is driving the growth of the honey market?
How is honey used in various industries?
How is the honey market expanding across regions?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Honey Food Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Honey Food Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,990 million → 2032: USD 13,465.57 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Honey Food Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Honey Food Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Honey Food Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Honey Food Market Drivers
- 3.3 Honey Food Market Restraints & Challenges
- 3.4 Honey Food Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Honey Food Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Honey Food Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Honey Food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Honey Food Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Honey Food Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Honey Food market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Honey Food Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Honey Food Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Honey Food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Honey Food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Honey Food Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Honey Food Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Honey Food Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Honey Food Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Honey Food Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Honey Food Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Honey Food Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Honey Food Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Honey Food Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
