
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Honey Powder market Size 2024 | USD 240.1 million |
| U.S. Honey Powder market, CAGR | 3.47% |
| U.S. Honey Powder market Size 2032 | USD 316.0 million |
Market Overview:
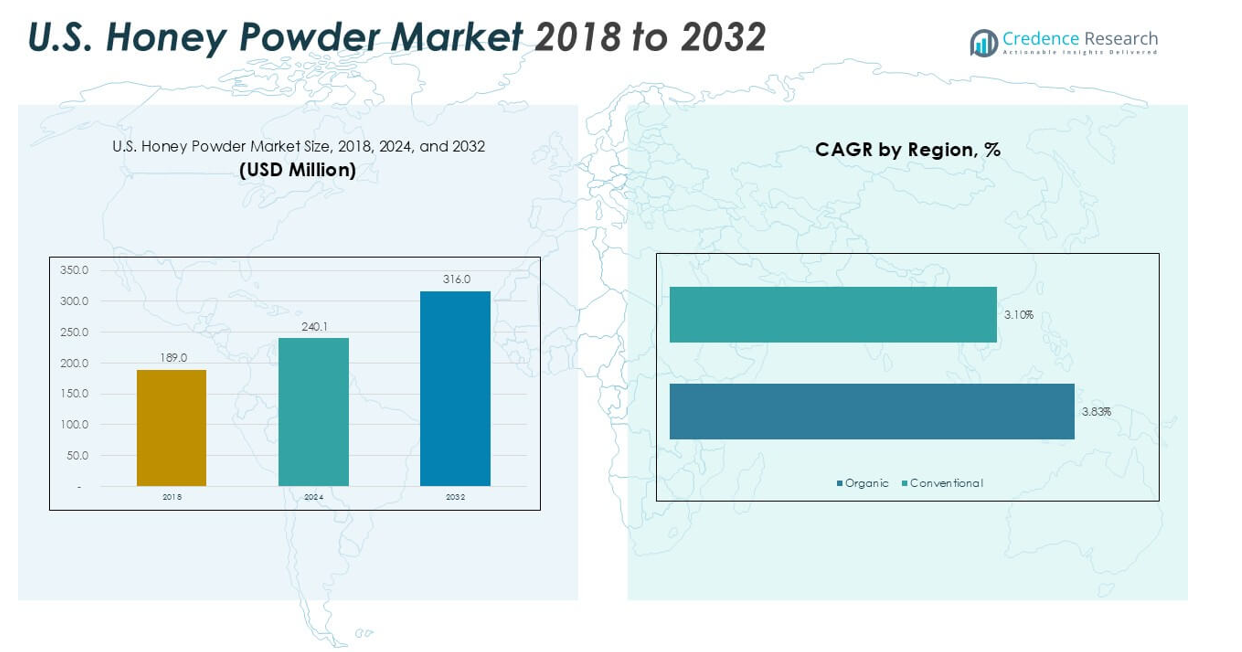
The U.S. Honey Powder market size was valued at USD 189.0 million in 2018 and reached USD 240.1 million in 2024. It is anticipated to reach USD 316.0 million by 2032, registering a compound annual growth rate (CAGR) of 3.47% during the forecast period.
The U.S. Honey Powder market features several top-tier players capturing significant share through scale, product innovation, and regional alignment. Cargill leads with approximately 15% market share, followed by ADM at 12%, reflecting their dominant position in large-scale production, R&D, and pan‑U.S. distribution. Among U.S. regions, the Western United States is the primary demand center due to its thriving food-processing infrastructure and organic market strength, closely trailed by the Midwest, South, and Northeast. These companies optimize regional capacities and logistics to capitalize on varying consumer preferences, emphasizing clean-label, organic, and traceable honey powder formats to maintain leadership across food, nutraceutical, and personal care sectors.
Market Insights
- The U.S. Honey Powder market was valued at USD 240.1 million in 2024 and is projected to reach USD 316.0 million by 2032, registering a CAGR of 3.47% during the forecast period.
- Demand is driven by increasing consumer preference for natural sweeteners, clean-label ingredients, and functional food additives in food, beverage, and nutraceutical applications.
- Trends include rising adoption of organic honey powder, a shift toward online sales channels, and product innovation targeting health-conscious and specialty markets.
- The market remains competitive with major players such as Cargill and ADM together accounting for about 27% share, while challenges include volatility in raw honey supply and competition from alternative sweeteners.
- Regionally, the Western U.S. leads with around 34% market share, followed by the Midwest at 28%, South at 23%, and Northeast at 15%; by product type, the conventional segment dominates due to its affordability and broad usage.
Market Segmentation Analysis:
By Product Type:
Within the U.S. Honey Powder market, the conventional segment holds the largest market share, accounting for a significant portion of total revenue. Conventional honey powder benefits from widespread availability and competitive pricing, making it the preferred choice among food manufacturers and industrial users. Although organic honey powder has gained attention due to rising consumer interest in clean-label and natural products, its adoption remains limited by higher costs and stricter certification requirements. The dominance of conventional honey powder is driven by cost-effectiveness and established distribution networks.
- For instance, ADM’s Decatur, Illinois facility has a dedicated production capacity of 1,250 metric tons of conventional honey powder annually, serving major North American food manufacturers.
By Application:
The food & beverages segment dominates the application category in the U.S. Honey Powder market, holding the largest revenue share. Food and beverage manufacturers rely heavily on honey powder as a natural sweetener and flavor enhancer, leveraging its extended shelf life and ease of incorporation into various products. The segment’s growth is supported by increasing demand for clean-label ingredients and sugar alternatives in baked goods, confectionery, and ready-to-eat products. The food & beverages application continues to outperform others due to consumer preference for healthier, naturally sourced ingredients.
- For instance, Cargill states that it supplies honey powder to over 100 food processing plants across the U.S. and includes the ingredient in at least 85 separate product formulations in the U.S. market.
By Sales Channel:
Offline sales channels represent the dominant segment in the U.S. Honey Powder market, capturing a major share of total sales. Distributors, specialty ingredient suppliers, and wholesalers ensure robust product availability to commercial buyers and large-scale users. The preference for offline channels persists due to the established business relationships and bulk purchasing options they offer. However, the online segment is experiencing steady growth, supported by the expanding reach of e-commerce and demand for direct-to-consumer purchasing. The dominance of offline channels is driven by efficient supply chains and industry trust in traditional procurement methods.
Market Overview
Expanding Demand for Natural Sweeteners
Rising consumer awareness of the health risks associated with refined sugar is driving increased adoption of honey powder as a natural sweetener. Food and beverage manufacturers leverage honey powder’s clean-label appeal, extended shelf life, and ease of formulation in various products. The trend toward reducing artificial additives and promoting healthier diets positions honey powder as a desirable alternative, fueling its demand in packaged foods, beverages, and health-conscious product lines across the U.S.
- For example, Nestlé USA revealed in a recent ingredient disclosure that honey powder is now included in 47 product SKUs ranging from granola bars to instant cereals.
Growth in Functional Food and Nutraceutical Markets
The growing interest in functional foods and nutraceuticals boosts the use of honey powder for its antioxidant and antimicrobial properties. Manufacturers incorporate honey powder into supplements, meal replacements, and health snacks to cater to consumers seeking added wellness benefits. The ingredient’s natural origin and nutritional profile support product differentiation in an increasingly competitive market, further strengthening its presence within health-focused categories and expanding its use beyond traditional food and beverage applications.
- For instance, NOW Foods has launched 14 new supplements and wellness products in 2022 and 2023 that feature honey powder as a functional ingredient.
Rising Popularity in Beauty and Personal Care Applications
Honey powder is gaining traction in the beauty and personal care sector due to its moisturizing and antibacterial properties. Formulators use it in skincare and haircare products, appealing to consumers who prioritize natural, effective ingredients. The trend toward clean beauty and organic formulations accelerates this shift, with honey powder offering both functional benefits and a compelling marketing story. This driver broadens the market’s scope and enhances its growth prospects across non-food industries.
Key Trends & Opportunities
Expansion of Clean-Label and Organic Product Lines
The U.S. Honey Powder market is witnessing a surge in clean-label and organic product offerings. Brands capitalize on consumer preferences for transparency, minimal processing, and sustainable sourcing by introducing organic honey powder lines. This trend presents opportunities for manufacturers to target premium segments and cater to health-focused buyers willing to pay higher prices for certified organic ingredients, thus enhancing margins and brand loyalty.
- For instance, Woodland Foods expanding its organic honey powder portfolio by releasing six new certified organic honey powder SKUs in the past 18
Digitalization and E-commerce Growth
The proliferation of digital platforms and e-commerce channels is transforming market access and consumer engagement. More producers and suppliers are leveraging online marketplaces to reach a wider audience, offer direct-to-consumer sales, and provide product information transparency. This trend creates new growth avenues for small and mid-sized players, reducing entry barriers and increasing the accessibility of honey powder products nationwide.
- For instance, Z Natural Foods reported that it processed over 60,000 direct online orders for honey powder products through its website and major e-commerce platforms during the 2023 calendar year
Key Challenges
Volatility in Raw Honey Supply and Pricing
Fluctuating availability and cost of raw honey pose a significant challenge for honey powder manufacturers. Adverse weather, disease, and environmental factors can disrupt honey production, causing supply shortages and price spikes. These uncertainties complicate procurement strategies and affect profitability, requiring market participants to develop more resilient supply chains and risk management practices.
Competition from Alternative Sweeteners
The U.S. Honey Powder market faces strong competition from a broad array of natural and artificial sweeteners, including stevia, agave, and monk fruit. These alternatives often offer different functional properties and price points, influencing manufacturer decisions and consumer preferences. Sustaining market share requires continuous product innovation, clear communication of honey powder’s benefits, and competitive pricing strategies.
Stringent Regulatory and Certification Requirements
Meeting stringent regulatory standards and obtaining necessary certifications, especially for organic honey powder, present hurdles for market players. Compliance with food safety, labeling, and quality assurance regulations can increase operational costs and extend time-to-market for new products. Navigating these complexities is critical for successful market participation, particularly for companies seeking to access premium and export-oriented segments.
Regional Analysis
Western United States
The Western United States holds the largest share in the U.S. Honey Powder market, contributing approximately 34% of the total market value. In 2018, the market size in this region stood at USD 64.3 million. The region benefits from a strong presence of natural and organic product manufacturers, driving higher demand for both organic and conventional honey powder. Organic honey powder in the West demonstrates a robust CAGR of 3.83%, outpacing conventional products, supported by consumers’ preference for clean-label ingredients and sustainable sourcing.
Midwestern United States
The Midwestern United States accounts for roughly 28% market share in the U.S. Honey Powder market, with a 2018 value estimated at USD 53.0 million. The region’s established food processing sector is a key driver for honey powder consumption, particularly in bakery and snack products. Conventional honey powder remains dominant, with a CAGR of 3.10%, as large-scale manufacturers prioritize cost efficiency. However, the organic segment is gaining traction, supported by rising health consciousness and demand for natural sweeteners across Midwestern states.
Southern United States
Representing about 23% of the U.S. Honey Powder market, the Southern United States registered a market size of USD 43.5 million in 2018. The region’s growth is fueled by the expanding food and beverage industry and increasing popularity of nutraceuticals. Conventional honey powder continues to lead, but organic variants are seeing accelerated adoption, supported by a CAGR of 3.83%. Southern consumers’ growing awareness of healthy living and interest in value-added products support market expansion across both product types.
Northeastern United States
The Northeastern United States captures nearly 15% of the market, with a 2018 market value of USD 28.4 million. This region is characterized by a strong inclination toward organic and premium food products, contributing to a higher CAGR of 3.83% for organic honey powder compared to conventional types. The market benefits from dense urban populations and demand from gourmet and specialty food manufacturers. While conventional honey powder maintains steady growth, organic options are rapidly gaining share in the Northeast’s dynamic and health-conscious market.
Market Segmentations:
By Product Type
- Organic
- Conventional
By Application
- Food & Beverages
- Beauty and Personal Care
- Nutraceutical
- Others
By Sales Channel
- Offline
- Online
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The U.S. Honey Powder market reflects a highly competitive landscape, shaped by multinational ingredient giants and specialized regional producers. Leading global players: Cargill (approximately 15% market share), ADM (12%), and Nestlé-collectively command around 40% of the market, leveraging extensive distribution networks, broad product portfolios, and deep R&D capabilities. These firms continuously invest in capacity expansion and value-chain integration to support rising demand. Companies compete on the basis of product purity, adherence to clean-label standards, and the ability to offer organic and functional variants. Strategic moves such as expanding production capacity, investing in research and development, and securing certifications have become common as firms seek to strengthen their presence. The market also benefits from an evolving supply chain and growing demand across food, nutraceutical, and personal care applications, encouraging continuous improvement and adaptation among market participants.
Key Player Analysis
- Imperial Sugar Company
- Lamex Food Group Limited
- Archer Daniels Midland Company
- Nestlé
- Domino Specialty Ingredients
- AmTech Ingredients
- Z Natural Foods
- Woodland Foods
- Augason Farms
- NOW Foods
Recent Developments
- In December 2024, Aldi introduced a new range of snacks featuring hot honey, a flavor trend popularized on TikTok. Priced at £1.49, the range includes items like Hot Honey Flatbreads, Greek Feta and hot honey bites, Hot Honey Pork Belly bites, and Honey, Chilli, and Camembert crisps. Additionally, Aldi collaborated with Sauce Shop to create a Spiced Cranberry Hot Honey Sauce for the festive season.
- In November 2024, Topgam introduced Hanumam, which is a line of honey-based gum doses, started locally characterized by a high dose of liquid honey in Israel. This product differs by using liquid honey instead of powder shapes and appeals to health -conscious consumers in search of natural ingredients.
- In October 2024, Nespresso launched its first ready for drink coffee, Measant Origins Columbia, Colombia with high quality coffee beans with honey from Colombia. This limited-Setsrit drink starts from October 2, 2024, the United States available in, which was in line with the commitment to the functionality and stability of Nesspresso.
- In 2023, Belize Sugar Industries (BSI) successfully attained recertification with zero non-conformities, following an external audit against the updated ProTerra Standard. Compliance with 80% of all indicators, including core ones, is essential for ProTerra certification. This achievement underscores BSI's commitment to meeting stringent sustainability criteria and maintaining high operational standards.
- In August 2023, the New Zealand Olympic Committee revealed that Mānuka Pharm had been designated as the official honey partner of the New Zealand Team. Mānuka Pharm leveraged this partnership to promote its unique offerings.
Market Concentration & Characteristics
The U.S. HONEY POWDER Market demonstrates moderate concentration, with a handful of prominent players such as Cargill, ADM, and Nestlé holding a significant share, while numerous regional and niche firms contribute to competitive diversity. It features a dynamic environment shaped by innovation in product formulation, certification standards, and clean-label initiatives. Leading companies leverage large-scale manufacturing capabilities, integrated supply chains, and established distribution networks to secure their market positions. The market displays strong consumer orientation toward natural sweeteners, functional ingredients, and organic variants, which encourages ongoing investment in research and product development. Entry barriers remain moderate due to the need for compliance with food safety regulations, consistent quality, and certification requirements. It experiences steady demand from food, beverage, nutraceutical, and personal care sectors, with conventional honey powder leading due to its cost-effectiveness and versatility. Regional variations in demand and preferences influence supply strategies and drive targeted product offerings.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Producers will expand organic honey powder offerings to meet rising demand for clean-label and natural products.
- Manufacturers will invest in traceability systems to enhance product transparency and consumer trust.
- Formulators will incorporate honey powder into functional foods and nutraceuticals for added health benefits.
- The online channel will gain importance as e-commerce platforms reach wider audiences and niche markets.
- Supply chains will diversify to reduce reliance on raw honey from traditional sources and mitigate price volatility.
- Certification standards, such as non-GMO and fair trade, will become more widespread across the value chain.
- Manufacturers will pursue strategic partnerships and acquisitions to accelerate capacity expansion and market reach.
- Innovation in flavor-infused and blend products will increase to support food, beverage, and personal care applications.
- Demand will grow in personal care and cosmetics as formulators leverage honey powder’s antimicrobial and moisturizing properties.
- Regional producers will tailor their product portfolios to address local consumer preferences and regulatory requirements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Honey Powder Market?
What factors are driving the growth of the U.S. Honey Powder Market?
What are the key segments within the U.S. Honey Powder Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 240.1 million → 2032: USD 316.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Honey Powder Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Honey Powder Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Honey Powder Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Honey Powder Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Honey Powder Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Honey Powder Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Honey Powder Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Honey Powder Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 240.1 million → 2032: USD 316.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Honey Powder Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Honey Powder Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Honey Powder Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Honey Powder Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
