
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Human Growth Hormone (HGH) Treatment And Drugs Market Size 2024 | USD 3,575 Million |
| Human Growth Hormone (HGH) Treatment And Drugs Market, CAGR | 3.7% |
| Human Growth Hormone (HGH) Treatment And Drugs Market Size 2032 | USD 4,780.86 Million |
Market Overview:
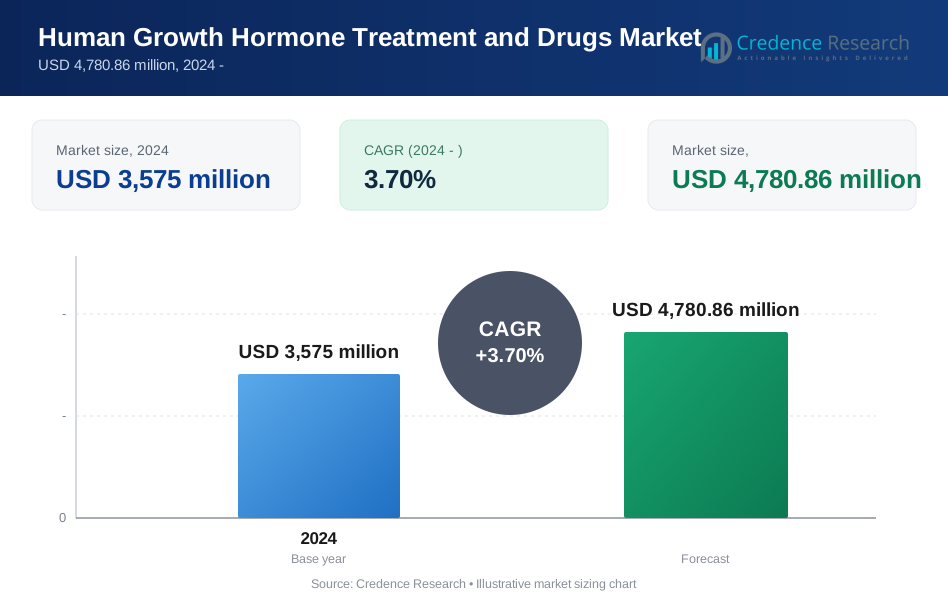
The global Human Growth Hormone (HGH) Treatment And Drugs Market size was valued at USD 3,575 million in 2024 and is anticipated to reach USD 4,780.86 million by 2032, at a CAGR of 3.7% during the forecast period (2024-2032).
This growth is driven by the increasing prevalence of growth hormone deficiencies and the rising awareness of the benefits of HGH treatments.
Several factors are driving the growth of the HGH Treatment and Drugs Market. The increasing incidence of growth hormone deficiencies due to congenital conditions, genetic disorders, and specific medical therapies has led to a higher demand for HGH treatments. Additionally, the growing awareness of endocrine disorders and the effectiveness of HGH in treating these conditions is fueling market growth. Furthermore, advancements in biotechnology and the development of novel HGH therapies with improved safety profiles and long-term efficacy are expected to drive market expansion.
Regionally, North America holds the largest market share in the HGH Treatment and Drugs Market, followed by Europe and the Asia-Pacific region. The dominance of North America can be attributed to the high prevalence of growth hormone deficiencies, well-established healthcare infrastructure, and the presence of key market players in the region. Europe is also a significant market due to the increasing adoption of HGH therapies and favorable government initiatives. The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, driven by the rising awareness of HGH treatments, improving healthcare infrastructure, and increasing healthcare expenditure in countries such as China and India.
Market Insights:
- The HGH treatment and drugs market is projected to grow from USD 3,575 million in 2024 to USD 4,780.86 million by 2032, with a CAGR of 3.7% during the forecast period.
- Rising prevalence of growth hormone deficiencies, advancements in recombinant DNA technology, and increasing adoption of biosimilar products are major growth catalysts.
- Innovations in drug delivery systems, including needle-free and sustained-release formulations, enhance patient compliance and expand market potential.
- High costs of treatment and strict regulatory frameworks pose challenges to market growth.
- North America dominates the market due to established healthcare infrastructure and significant R&D investments.
- The Asia-Pacific region is witnessing rapid growth, driven by rising healthcare expenditure and improving access to treatments.
- Europe follows North America in market share, while Latin America and the Middle East & Africa show moderate growth potential.
Market Drivers:
Clinical Need and Disease Prevalence:
The increasing prevalence of growth hormone-related disorders, including growth hormone deficiency, Turner syndrome, and Prader-Willi syndrome, is driving substantial market expansion. For instance, recent epidemiological studies show growth hormone deficiency affects between 1/28,800 to 1/46,700 new cases per year, with a 20-year cumulative incidence of 127/100,000 for boys and 93/100,000 for girls. For Turner syndrome, the prevalence is approximately 3.2 per 10,000 female live births, with program ranges varying from 1.0 to 10.4. For Prader-Willi syndrome, it affects approximately 1 in 37,037 persons in the US population.
Technological Advancements:
Innovations in recombinant DNA technology and biotechnology have revolutionized HGH production methods, leading to safer and more effective synthetic growth hormones. For instance, in June 2023, Pfizer Inc. and OPKO Health Inc. received FDA approval for NGENLA, a once-weekly human growth hormone analog for children aged three and older with growth failure. Clinical trials demonstrated NGENLA's effectiveness with an annual height gain rate of 10.12 cm/year compared to 9.78 cm/year in the control group.
Healthcare Infrastructure:
The expansion of hospital pharmacies and specialty treatment centers has enhanced treatment accessibility. For instance, digital transformation in pharmacy services has led to more individualized and efficient patient care, with telehealth adoption surging from 11% in 2019 to 46% during recent years. The implementation of telepharmacy services has been particularly successful, with 95.6% of pharmacies utilizing phone services and 80% using messaging applications for patient care.
Research and Development:
Pharmaceutical companies are heavily investing in developing long-acting formulations and novel drug delivery systems. For instance, currently, five approved long-acting growth hormone drugs are available on the market, utilizing various technologies such as depot formulations, PEGylated formulations, pro-drug formulations, non-covalent albumin binding growth hormone, and growth hormone fusion proteins. These developments have significantly improved treatment options and patient compliance through reduced injection frequency from daily to weekly or monthly administration.
Market Trends:
Treatment Evolution:
The landscape of growth hormone therapy has transformed significantly since the introduction of recombinant human growth hormone in 1985. For instance, currently, five approved long-acting growth hormone drugs dominate the market, utilizing advanced technologies such as depot formulations, PEGylated formulations, pro-drug formulations, non-covalent albumin binding, and fusion proteins. Sogroya® became the first FDA-approved LAGH formulation, while NGENLA received regulatory approvals in more than 40 markets including Canada, Australia, Japan, and EU Member States.
Clinical Advancements:
Clinical trials have demonstrated remarkable efficacy in newer formulations. For instance, the Phase 3 heiGHt trial showed that TransCon Growth Hormone achieved an annualized height velocity of 11.2 cm compared to 10.3 cm with daily Genotropin, with an estimated treatment difference of 0.86 cm. in the NGENLA group, patients achieved an annual height gain rate of 10.12 cm/year compared to 9.78 cm/year in the active control group, demonstrating consistent efficacy across new formulations.
Treatment Accessibility:
The emergence of multiple administration options has enhanced treatment accessibility and patient compliance. For instance, studies show that patients treated with PEG-rhGH demonstrated significantly better adherence, with an average of only 0.48 ± 0.82 missed doses in the first year compared to 11.50 ± 7.83 missed doses with daily treatments. by the second year, these numbers improved further to 0.30 ± 0.61 missed doses for PEG-rhGH versus 20.24 ± 14.84 for daily treatments.
Performance Applications:
A comprehensive review of 44 high-quality studies involving 303 GH-treated subjects and 137 placebo recipients revealed significant physiological improvements. For instance, treatment resulted in an average gain of 4.6 pounds of lean body mass over 20 days, with subjects simultaneously shedding a similar amount of body fat. the foresiGHt Trial demonstrated that TransCon hGH achieved a -1.67% reduction in trunk fat compared to placebo, along with a significant increase in total body lean mass of +1.60 kg.
Market Challenges Analysis:
Cost and Accessibility Barriers:
The prohibitive cost of HGH therapies presents a significant market barrier, with long-term treatments often spanning several years and straining healthcare budgets. In the U.S., the average annual cost of HGH therapy ranges from $10,000 to $60,000 per patient, making affordability a critical issue, especially for uninsured individuals. Additionally, the Federal Drug Administration (FDA) and European Medicines Agency (EMA) require extensive clinical trials and validations, further escalating development costs. On average, the development of a new biologic drug, including HGH, costs between $1.2 billion and $2.6 billion due to stringent regulatory requirements. In Australia, the Therapeutic Goods Administration (TGA) mandates strict prescription requirements and import controls. Patients are prohibited from importing HGH, even with prescriptions, and must obtain it through licensed physicians with special permits from the Office of Drug Control. These regulatory constraints contribute to treatment inaccessibility and regional disparities in HGH availability.
Regulatory Compliance:
Stringent regulatory frameworks imposed by authorities like the FDA and EMA demand meticulous compliance throughout the drug development and commercialization process. The average approval timeline for new HGH therapies exceeds 10 years, adding significant financial burdens to pharmaceutical companies. Additionally, regulatory agencies enforce strict advertising laws to prevent misuse. The Federal Court of Australia, for example, imposed a $10 million penalty in 2019 on a company for illegally advertising prescription peptides, underscoring the consequences of non-compliance. In the U.S., the FDA issued over 50 warning letters between 2020 and 2023 to clinics and online retailers marketing HGH without proper authorization. These regulatory requirements significantly extend development timelines, increase operational costs, and restrict direct-to-consumer advertising.
Safety and Side Effects:
The management of adverse effects remains a critical challenge in HGH therapy. Common side effects include edema (fluid retention), joint pain, insulin resistance, and increased risk of certain cancers, necessitating careful patient monitoring. Healthcare providers must oversee sophisticated pharmacological interventions and ongoing medical supervision to mitigate risks. A 2021 study published in the Journal of Clinical Endocrinology & Metabolism indicated that 30–40% of adult HGH users experience at least one significant adverse effect, highlighting the need for stringent safety protocols. The TGA specifically emphasizes that HGH should only be administered under strict medical supervision due to the risks associated with improper use, particularly in off-label applications such as bodybuilding and anti-aging treatments.
Manufacturing Complexities:
The intricate biotechnological processes involved in producing recombinant human growth hormone (rhGH) demand advanced facilities and stringent quality control measures. The manufacturing of HGH involves multiple purification and filtration steps, with yields as low as 20–30%, increasing costs and production time. Compliance with Good Manufacturing Practice (GMP) guidelines, as enforced by regulatory bodies like the FDA and EMA, further necessitates state-of-the-art infrastructure. These requirements contribute to elevated production costs, often exceeding $500 per milligram of rhGH, making large-scale production challenging, especially in developing regions. Additionally, a 2023 report by the International Society for Pharmaceutical Engineering (ISPE) noted that only a handful of manufacturers worldwide have the capability to produce high-quality HGH at scale, leading to supply chain constraints and regional treatment disparities.
Market Opportunities:
The Human Growth Hormone (HGH) Treatment and Drugs Market offers substantial opportunities for growth, driven by advancements in biotechnology and the rising demand for innovative therapies. Increasing awareness about growth hormone deficiencies and associated disorders presents a significant opportunity for market players to expand their offerings. The growing adoption of biosimilars, supported by regulatory approvals, is expected to make treatments more accessible and cost-effective, particularly in emerging economies. Additionally, the development of novel drug delivery systems, such as sustained-release and needle-free devices, provides an opportunity to enhance patient adherence and expand the patient pool. Strategic partnerships and collaborations among pharmaceutical companies to advance R&D efforts further bolster market potential.
Emerging markets, particularly in Asia-Pacific, present untapped opportunities due to improving healthcare infrastructure and rising disposable income. Countries such as China and India are experiencing a growing incidence of growth-related disorders, creating a fertile ground for market expansion. Moreover, increasing government initiatives to address rare diseases and enhance public healthcare systems provide a conducive environment for companies to introduce affordable and effective HGH treatments. Furthermore, the aging population and its susceptibility to growth hormone deficiencies in developed and developing regions alike create a steady demand for HGH therapies. Companies investing in precision medicine and personalized treatment approaches will likely gain a competitive edge, capitalizing on the growing need for tailored healthcare solutions in this expanding market.
Market Segmentation Analysis:
By Route of Administration
The market is categorized into subcutaneous, intramuscular, and oral administration. Subcutaneous administration dominates the segment, attributed to its higher efficacy, ease of use, and improved patient adherence. Several long-acting HGH formulations, such as Somapacitan and Skytrofa, utilize subcutaneous delivery to ensure sustained hormone release. Intramuscular administration, while effective, is less preferred due to pain and lower patient compliance. Oral formulations, though still in the early stages, are gaining traction with ongoing advancements in biotechnology aimed at enhancing bioavailability.
By Application
HGH therapies are primarily used in growth hormone deficiency (GHD), Turner syndrome, Prader-Willi syndrome, idiopathic short stature, and other metabolic disorders. Growth hormone deficiency (GHD) holds the largest market share, driven by the increasing prevalence of pediatric and adult cases. Additionally, non-medical applications, such as HGH use in anti-aging treatments and sports performance enhancement, are contributing to market expansion despite regulatory scrutiny.
By Distribution Channel
The market is segmented into hospital pharmacies, retail pharmacies, and online pharmacies. Hospital pharmacies lead the market, as HGH treatments require physician supervision and specialized handling. Retail pharmacies serve as an important channel, particularly in developed regions with established prescription frameworks. Meanwhile, online pharmacies are experiencing rapid growth due to rising digital healthcare adoption, providing convenience and cost-effective options for patients.
Segmentations:
By Route of Administration:
- Subcutaneous
- Intramuscular
- Intravenous
- Oral
By Application:
- Growth Hormone Deficiency
- Turner Syndrome
- Idiopathic Short Stature (ISS)
- Prader-Willi Syndrome (PWS)
- Other Applications
By Distribution Channel:
- Hospital Pharmacy
- Specialty Pharmacy
- Retail Pharmacy
- Online Pharmacy
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for 40% of the global market in 2024. the region’s dominance is attributed to advanced healthcare infrastructure, high awareness about growth hormone therapies, and substantial investment in research and development. For instance, the United States leads within North America due to the strong presence of key market players, widespread adoption of innovative drug delivery systems, and favorable reimbursement policies. Canada also contributes to growth with increasing healthcare expenditure and government support for rare disease treatments.
Europe
Europe is the second-largest market, representing 30% of the global share. the region benefits from high adoption rates of advanced therapeutic options and supportive regulatory frameworks. For instance, countries such as Germany, the United Kingdom, and France drive growth due to strong biotechnology industries and robust healthcare systems. the European market is further supported by the availability of biosimilars, which reduce treatment costs and expand access to HGH therapies.
Asia-Pacific
Asia-Pacific is the fastest-growing region, with a market share of 20% in 2024, projected to increase significantly by 2032. For instance, rapid economic growth, improving healthcare infrastructure, and rising awareness of growth hormone deficiencies in countries like China, India, and Japan are fueling market expansion. increasing healthcare expenditure and government initiatives to address rare diseases also create opportunities for manufacturers in the region.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa together account for 10% of the global market. For instance, in Latin America, countries like Brazil and Mexico are witnessing moderate growth due to improving healthcare access and rising medical tourism. meanwhile, the Middle East & Africa region is seeing a steady increase in HGH adoption, supported by ongoing healthcare infrastructure development and growing awareness campaigns targeting rare disorders.
Key Player Analysis:
- Novo Nordisk A/S
- Pfizer Inc.
- Eli Lilly and Company
- Merck KGaA
- Sandoz International GmbH (a division of Novartis AG)
- Ferring Pharmaceuticals
- Ipsen S.A.
- Teva Pharmaceutical Industries Ltd.
- GeneScience Pharmaceuticals Co., Ltd.
- LG Chem
Competitive Analysis:
The Human Growth Hormone (HGH) Treatment and Drugs Market is highly competitive, with key players focusing on innovation, strategic collaborations, and geographic expansion to strengthen their market presence. major companies, including Novo Nordisk A/S, Pfizer Inc., Eli Lilly and Company, and Sandoz International GmbH, lead the market through extensive R&D investments and a strong product portfolio. the emergence of biosimilars, driven by companies like Teva Pharmaceutical Industries Ltd. and LG Chem, is intensifying competition by offering cost-effective alternatives to branded products. For instance, smaller players and regional firms, such as GeneScience Pharmaceuticals Co., Ltd., are leveraging regional market demands to establish a foothold. market participants are increasingly adopting advanced drug delivery systems and targeting emerging markets like Asia-Pacific to capitalize on growth opportunities. this competitive landscape underscores the dynamic and evolving nature of the HGH treatment and drugs market.
Recent Developments:
Pfizer
June 2023: FDA approved NGENLA (somatrogon-ghla) for pediatric patients aged three and older with growth failure.
August 2023: Successfully launched NGENLA in the U.S. market following the approval.
Novo Nordisk
February 2025: Completed clinical trials for somapacitan in Japanese adults, showing comparable efficacy to daily growth hormone treatment.
March 2024: Ongoing Phase 2 trial for somapacitan in children born small, showing 3x higher treatment adherence compared to daily treatment.
Sandoz
October 2024: Reported strong performance in biosimilars with Omnitrope showing high demand.
December 2024: Achieved milestone of over 886,092 patient treatment-years of experience worldwide with their biosimilar rhGH, now approved in 80 countries.
Eli Lilly
December 2024: Announced $3 billion investment to expand manufacturing facility in Wisconsin, focusing on injectable medicines and device assembly.
Merck KGaA
September 2023: Expanded Saizen® availability with Aluetta® pen now reaching 67 countries.
Market Concentration & Characteristics:
The Human Growth Hormone (HGH) Treatment and Drugs Market exhibits a moderately concentrated structure, with a few key players such as Novo Nordisk A/S, Pfizer Inc., and Eli Lilly and Company dominating a significant share. These companies leverage their extensive R&D capabilities, strong global presence, and comprehensive product portfolios to maintain competitive advantages. The market is characterized by continuous innovation, particularly in drug delivery systems and biosimilar development, which are reshaping treatment paradigms. While multinational corporations lead the market with advanced technologies and widespread distribution networks, smaller regional players also contribute by catering to localized demands. Regulatory compliance and high development costs act as entry barriers, ensuring the dominance of established players. Moreover, the increasing focus on patient-centric solutions, affordability, and accessibility is shaping the competitive dynamics, creating opportunities for both large firms and emerging companies to thrive.
Report Coverage:
The research report offers an in-depth analysis based on Route of Administration, Application, Distribution Channel, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Advances in biotechnology will drive the development of novel, long-acting formulations, improving patient compliance and therapeutic outcomes.
- Increased adoption of biosimilars will enhance affordability and accessibility, particularly in emerging markets.
- Personalized medicine approaches will grow, leveraging genetic profiling to optimize HGH treatment efficacy.
- Innovative drug delivery systems, such as needle-free injectors and sustained-release formulations, will gain traction, addressing patient convenience.
- Rising awareness of growth hormone disorders among healthcare professionals and patients will contribute to early diagnosis and treatment.
- Regulatory approvals for new indications and expanded age groups are expected to widen the market's scope.
- Partnerships between pharmaceutical companies and research institutions will accelerate innovation and clinical trials.
- Healthcare infrastructure improvements in developing regions will facilitate market penetration and expansion.
- Digital health technologies, including remote monitoring and telemedicine, will play a significant role in managing HGH therapies.
- Environmental sustainability and cost-efficiency in production processes will emerge as priorities for manufacturers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Growth Hormone Deficiencies
The increasing incidence of growth hormone-related disorders such as growth hormone deficiency, Turner syndrome, and Prader-Willi syndrome is driving demand for HGH therapies, as more patients require effective treatment options.
Advancements in Biotechnology and Drug Delivery
Innovations in recombinant DNA technology and the development of long-acting, sustained-release, and needle-free formulations have improved the safety, efficacy, and convenience of HGH treatments, expanding the patient pool and boosting market growth.
Growing Adoption of Biosimilars
The introduction and regulatory approval of biosimilar HGH products are making treatments more affordable and accessible, particularly in emerging markets, thereby increasing overall market penetration.
Expansion of Healthcare Infrastructure and Digital Health
Improvements in hospital and specialty pharmacy networks, along with the adoption of telehealth and digital pharmacy services, are enhancing patient access to HGH therapies and supporting market expansion.
Increased Awareness and Early Diagnosis
Rising awareness among healthcare professionals and the public about endocrine disorders and the benefits of early HGH intervention is leading to earlier diagnosis and higher treatment rates, further fueling market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Human Growth Hormone (HGH) Treatment and Drugs Market?
What factors are driving the growth of the Human Growth Hormone (HGH) Treatment and Drugs Market?
What are some challenges faced by the Human Growth Hormone (HGH) Treatment and Drugs Market?
Who are the major players in the Human Growth Hormone (HGH) Treatment and Drugs Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Growth Hormone Deficiency
- 1.2.2 Turner Syndrome
- 1.2.3 Idiopathic Short Stature (ISS)
- 1.2.4 Prader-Willi Syndrome (PWS)
- 1.2.5 Other Applications
- 1.3 By Route of Administration
- 1.3.1 Subcutaneous
- 1.3.2 Intramuscular
- 1.3.3 Intravenous
- 1.3.4 Oral
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,575 million → 2032: USD 4,780.86 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Human Growth Hormone Treatment and Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Human Growth Hormone Treatment and Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Human Growth Hormone Treatment and Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Human Growth Hormone Treatment and Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Human Growth Hormone Treatment and Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Human Growth Hormone Treatment and Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Human Growth Hormone Treatment and Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Human Growth Hormone Treatment and Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,575 million → 2032: USD 4,780.86 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Human Growth Hormone Treatment and Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Growth Hormone Deficiency
- 12.3.7.2 Turner Syndrome
- 12.3.7.3 Idiopathic Short Stature (ISS)
- 12.3.7.4 Prader-Willi Syndrome (PWS)
- 12.3.7.5 Other Applications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Subcutaneous
- 12.4.7.2 Intramuscular
- 12.4.7.3 Intravenous
- 12.4.7.4 Oral
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Human Growth Hormone Treatment and Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Human Growth Hormone Treatment and Drugs Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Human Growth Hormone Treatment and Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Human Growth Hormone Treatment and Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Novo Nordisk A/S
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Pfizer Inc.
- 18.4 Eli Lilly and Company
- 18.5 Merck KGaA
- 18.6 Sandoz International GmbH (Novartis AG)
- 18.7 Ferring Pharmaceuticals
- 18.8 Ipsen S.A.
- 18.9 Teva Pharmaceutical Industries Ltd.
- 18.10 GeneScience Pharmaceuticals Co., Ltd.
- 18.11 LG Chem
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

