
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Hunting Equipment and Accessories Market Size 2024 | USD 25,020.14 Million |
| Hunting Equipment and Accessories Market, CAGR | 7.38% |
| Hunting Equipment and Accessories Market Size 2032 | USD 44,225.92 Million |
Market Overview
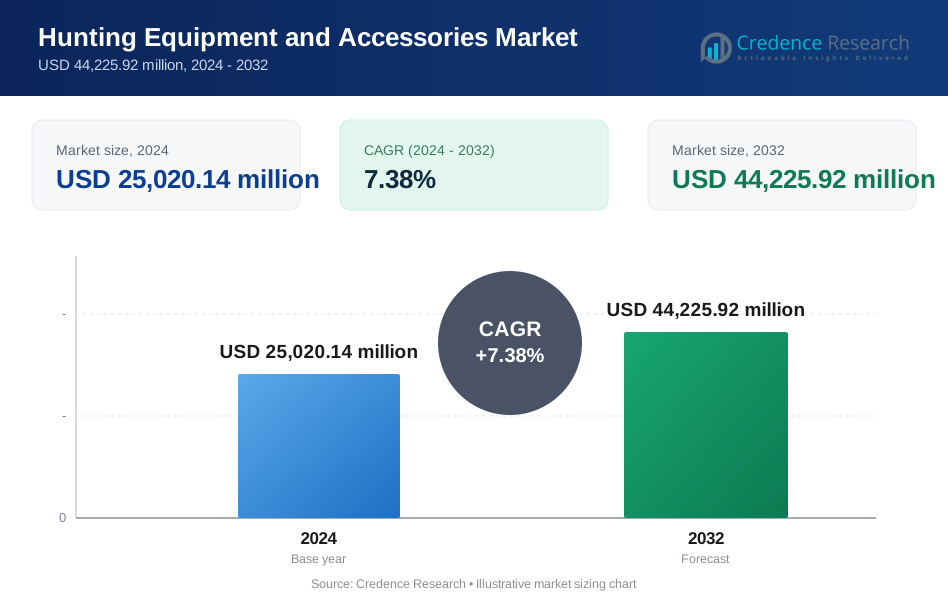
The Hunting Equipment and Accessories Market is projected to grow from USD 25,020.14 million in 2024 to USD 44,225.92 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.38%.
The Hunting Equipment and Accessories Market is driven by increasing participation in outdoor recreational activities, heightened interest in wildlife conservation, and the growing popularity of hunting as a sport. Technological advancements in equipment, such as enhanced accuracy in firearms and improved durability in accessories, are attracting both novice and experienced hunters. Additionally, the rise of e-commerce platforms has made hunting gear more accessible, further boosting market growth. Trends towards customization and the demand for eco-friendly materials in hunting accessories also reflect the evolving preferences of modern consumers.
The Hunting Equipment and Accessories Market is experiencing significant growth across various regions, with North America leading due to its strong hunting culture and expansive outdoor recreational activities. Europe follows closely, driven by the increasing popularity of hunting tourism. The Asia-Pacific region is also witnessing rising demand, particularly in countries with growing disposable incomes and expanding outdoor leisure activities. Key players such as Vista Outdoor Inc., Sturm Ruger and Co. Inc., and Beretta Holding SA dominate the market through their extensive product portfolios, strategic partnerships, and strong distribution networks, ensuring a competitive edge in both established and emerging markets.
Market Drivers
Increasing Popularity of Outdoor Activities
The Hunting Equipment and Accessories Market is experiencing growth driven by the rising interest in hunting and outdoor recreational activities. According to the 2022 National Survey of Fishing, Hunting, and Wildlife-Associated Recreation, nearly 11.5 million participants engaged in hunting in 2016, with 7.9 million of them being deer hunters. This trend is further supported by the growth of outdoor pursuits, as evidenced by the 2023 Outdoor Participation Trends Report, which states that the outdoor recreation participant base grew 2.3 percent in 2022 to a record 168.1 million participants, representing 55 percent of the U.S. population ages six and older. These complementary outdoor activities expand the market for hunting gear, as enthusiasts seek equipment that can serve multiple purposes, thereby driving demand for versatile and durable products.
Economic and Demographic Factors
Economic factors and demographic trends contribute to market growth. In 2016, hunters spent $7.1 billion on equipment alone, including expenditures on firearms, ammunition, archery gear, optics, calls, decoys, and more. Additionally, they spent $3.2 billion on travel to and from their hunting destinations, with a total spending of $27.1 billion to enjoy the sport. Demographic trends also play a role, with baby boomers making up roughly a third of all hunters in the U.S.. However, there's a need to attract younger and more diverse participants to sustain the market, as evidenced by preliminary survey results showing that more than 60% of college students approve of hunting, while about 30% currently hunt. Furthermore, increased urban-to-rural migration is leading to a growing interest in hunting, as people moving to rural areas seek to engage in outdoor activities, including hunting, thereby expanding the market base.
Technological Advancements
Technological advancements are playing a crucial role in enhancing the performance and appeal of hunting equipment. Improvements in materials and technology have led to better performance, increased accuracy, and greater durability of hunting gear, which are highly valued by both novice and experienced hunters. Additionally, the market is witnessing the introduction of innovative products that cater to the evolving needs and preferences of hunters, such as advanced optics, lightweight firearms, and smart accessories. These innovations not only improve the hunting experience but also attract a broader audience to the sport.
Wildlife Management and Conservation
Hunting also plays a significant role in wildlife management and conservation, which supports the market's growth. Revenue generated from hunting licenses and permits is often directed towards wildlife conservation efforts, contributing to the preservation of habitats and the maintenance of ecological balance. Moreover, hunting is an essential tool for managing wildlife populations, preventing overpopulation, and protecting ecosystems from the negative impacts of overgrazing or disease. This symbiotic relationship between hunting and conservation helps sustain the industry and ensures its continued relevance.
Market Trends
Technological Integration and Customization
The Hunting Equipment and Accessories Market is increasingly embracing technological integration, transforming traditional gear into smart, multifunctional tools. The incorporation of technology into hunting equipment, such as GPS devices, rangefinders, and camera systems, is becoming standard practice, offering hunters enhanced precision, convenience, and safety. These smart hunting tools not only improve the overall hunting experience but also attract a tech-savvy audience to the sport. Additionally, the use of advanced materials, such as lightweight and durable composites, is enhancing product performance and comfort, allowing hunters to carry gear that is both efficient and easy to use over long periods. This trend towards technological sophistication is complemented by a growing demand for customization and personalization. Hunters are increasingly seeking tailored equipment that meets their specific needs and preferences, whether it be in terms of functionality, aesthetics, or adaptability. Modular designs, which allow for interchangeable components, offer flexibility and enable hunters to modify their gear for different environments or game types, further driving market innovation and consumer engagement.
Focus on Sustainability and Ethical Practices
Sustainability is becoming a central focus in the Hunting Equipment and Accessories Market, reflecting broader environmental concerns and a shift towards more responsible consumption. The U.S. Fish and Wildlife Service reported that in 2016, 101.6 million Americans (40% of the U.S. population aged 16 years and older) participated in wildlife-related activities such as hunting, fishing, and wildlife-watching. There is a growing demand for eco-friendly hunting gear made from sustainable, biodegradable, and recycled materials, which aligns with the increasing environmental consciousness of consumers. Manufacturers are responding by developing products that minimize ecological impact, catering to hunters who prioritize sustainability in their purchasing decisions. Alongside this, there is a rising emphasis on ethical hunting practices, with consumers becoming more aware of the need for responsible hunting and conservation efforts. This shift in consumer values is influencing product development and marketing strategies, as brands strive to align themselves with the principles of sustainability and ethical behavior. The focus on sustainability extends beyond the products themselves to include packaging and production processes, with companies seeking to reduce their overall environmental footprint.
Market Challenges Analysis
Regulatory and Environmental Concerns
The Hunting Equipment and Accessories Market faces significant challenges related to regulatory and environmental concerns. As governments worldwide impose increasingly stringent regulations on hunting and wildlife conservation, manufacturers must navigate complex legal landscapes that can restrict product development and sales. For example, a study by the Wildlife Conservation Society found that hunting tourism, while profitable, generates 15 times less revenue than ecotourism, highlighting the shift towards more environmentally-friendly practices. These regulations are designed to protect wildlife and ensure sustainable hunting practices, but they can also create hurdles for companies trying to innovate or expand their offerings. Additionally, the growing environmental awareness among consumers and policymakers is pressuring manufacturers to adopt more sustainable practices in sourcing materials and production processes. This shift towards sustainability, while necessary and beneficial in the long term, often requires substantial investments in new technologies and supply chain adjustments, which can be both costly and time-consuming. As a result, companies must balance the need for compliance and sustainability with the demands of maintaining profitability and market share.
Economic Factors and Competition
Economic factors also play a crucial role in shaping the Hunting Equipment and Accessories Market. Economic downturns, such as recessions, can significantly reduce consumer spending on non-essential items like hunting gear, leading to decreased sales and market contraction. Furthermore, the rising costs of raw materials and production processes can force companies to increase product prices, which may deter price-sensitive consumers and further impact sales. In addition to these economic challenges, the market is characterized by intense competition among both established brands and new entrants. This competitive environment drives innovation but also makes it difficult for companies to maintain market share, especially in the face of aggressive pricing strategies and marketing efforts by rivals. The prevalence of counterfeit products in the market adds another layer of complexity, as these low-quality imitations can damage the reputation of established brands and erode consumer trust, ultimately impacting overall market performance.
Market Segmentation Analysis:
By Product:
The Hunting Equipment and Accessories Market is broadly segmented by product types, including guns and rifles, archery, ammunition, auxiliary equipment, and others. Guns and rifles remain the dominant segment, driven by consistent demand from both recreational hunters and professional sportsmen. Archery is witnessing growing popularity, especially with the increasing interest in bowhunting as an environmentally friendly and traditional hunting method. Ammunition is an essential and recurring purchase for hunters, contributing significantly to market revenue. Auxiliary equipment, such as scopes, binoculars, and protective gear, plays a crucial role in enhancing the hunting experience, making this segment vital for overall market growth.
By Application:
The market is also segmented by application into individual and commercial categories. The individual segment represents the largest share, as hunting remains a popular recreational activity for outdoor enthusiasts. This segment benefits from increasing disposable incomes and a growing interest in personalized and high-quality hunting gear. The commercial segment, while smaller, is expanding due to the rise in hunting tourism and organized hunting events. This segment includes professional hunting guides, game reserves, and commercial shooting ranges, which require a steady supply of hunting equipment and accessories to cater to their clientele.
Segments:
Based on Product:
- Gun and Rifle
- Archery
- Ammunition
- Auxiliary Equipment
- Others
Based on Application:
- Individual
- Commercial
Based on Distribution Channel:
- Supermarkets/Hypermarkets
- Specialty Stores
- Online Platforms
- Others
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America
North America, which holds a substantial 45% market share. This region's leadership is primarily driven by the United States, where hunting is deeply ingrained in the cultural fabric and outdoor recreational activities are highly popular. For instance, according to a report by the U.S. Fish and Wildlife Service in 2017, 101.6 million Americans (40% of the U.S. population aged 16 years and older) participated in wildlife-related activities in 2016, such as hunting, fishing, and wildlife-watching. The strong hunting tradition, coupled with favorable regulations and vast wilderness areas, has created a robust demand for a wide range of hunting equipment and accessories. North America's market dominance is further reinforced by the presence of major manufacturers and retailers specializing in hunting gear, as well as the region's high disposable income levels. The increasing trend towards high-tech hunting equipment, including advanced optics, GPS devices, and specialized clothing, has also contributed to the market's growth. Additionally, the region's emphasis on wildlife conservation and sustainable hunting practices has led to the development of eco-friendly and ethically sourced hunting products, further expanding the market offerings.
Europe
Europe follows as the second-largest market for hunting equipment and accessories, accounting for a 30% market share. Countries like Germany, France, and the United Kingdom have significant hunting communities and well-established hunting traditions, driving the demand for quality hunting gear. The European market is characterized by a strong focus on precision equipment, particularly in firearms and optics, reflecting the region's emphasis on marksmanship and ethical hunting practices. The growing popularity of hunting tourism in Eastern European countries has also contributed to market growth, as it has increased the demand for rental equipment and accessories. Moreover, Europe's stringent regulations on hunting and firearms have led to the development of specialized equipment that complies with local laws, creating niche market segments.
Key Player Analysis
- Vista Outdoor Inc.
- SPYPOINT
- Sturm Ruger and Co. Inc.
- Under Armour, Inc.
- Spyderco, Inc.
- Buck Knives, Inc.
- Beretta Holding SA
- Dick’s Sporting Goods, Inc.
- BPS Direct LLC
- American Outdoor Brands Corp.
Competitive Analysis
The Hunting Equipment and Accessories Market is highly competitive, with key players like Vista Outdoor Inc., Sturm Ruger and Co. Inc., and Beretta Holding SA leading the industry. Vista Outdoor Inc. leverages its diverse portfolio of hunting and outdoor products, strong brand recognition, and widespread distribution channels to maintain its market leadership. Sturm Ruger and Co. Inc. is renowned for its high-quality firearms and innovative designs, catering to a loyal customer base. Beretta Holding SA, with its long history and reputation for precision firearms, continues to dominate the premium segment of the market. Additionally, companies like American Outdoor Brands Corp. and Dick’s Sporting Goods, Inc. are focusing on expanding their product offerings and enhancing customer experience through both physical and online retail channels. The competition is intensified by the presence of smaller, specialized companies like Buck Knives, Inc. and Spyderco, Inc., which offer niche products, contributing to a dynamic and competitive market landscape.
Recent Developments
- In January 2024, Ruger celebrated the 60th anniversary of its iconic 10/22 rifle by introducing a new variation. While specific details of the new model were not provided in the available sources, this release commemorates six decades of the popular .22 caliber semi-automatic rifle’s production.
- In July 22, 2024, Vista Outdoor announced an increased purchase price from CSG for The Kinetic Group of $2.15 billion and increased cash consideration of $24.00 per share.
- In January 24, 2024, SPYPOINT announced the expansion of its FLEX series with the introduction of two new cellular trail cameras - the FLEX-M and the FLEX-PLUS.
- On March 12, 2024, Sturm Ruger & Company, Inc. announced 36 new configurations of the Ruger American® Rifle Generation II, which includes 18 configurations of the new Predator variant of this popular rifle.
- In March 18, 2024, American Outdoor Brands, Inc., headquartered in Springfield, Massachusetts, United States, is set to make headlines with its participation in the 36th Annual ROTH Conference. As a leading provider of outdoor products and accessories, the company's involvement underscores its commitment to industry innovation and active investor engagement.
Market Concentration & Characteristics
The Hunting Equipment and Accessories Market is characterized by moderate to high market concentration, with a mix of established players and specialized niche brands dominating the industry. Major companies like Vista Outdoor Inc., Beretta Holding SA, and Sturm Ruger and Co. Inc. hold significant market shares due to their extensive product portfolios, strong brand loyalty, and wide distribution networks. These companies benefit from economies of scale, allowing them to maintain competitive pricing and invest in research and development for product innovation. However, the market also includes smaller, specialized brands that cater to specific segments, such as archery or hunting apparel, adding to the diversity of the market. The market is marked by continuous innovation, driven by technological advancements and evolving consumer preferences. Despite the presence of dominant players, the market remains competitive, with new entrants and smaller brands challenging established companies by offering unique products or specialized services.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to see continued growth due to rising interest in outdoor activities and hunting as a recreational pursuit.
- Technological advancements in hunting equipment, such as smart gear and advanced optics, will drive innovation and attract tech-savvy consumers.
- Increasing demand for customized and personalized hunting gear will offer opportunities for manufacturers to cater to niche markets.
- Sustainability and eco-friendly product development will become more prominent as consumers prioritize environmentally responsible hunting practices.
- The growing popularity of e-commerce will expand distribution channels, making hunting equipment more accessible to a global audience.
- Economic stability and rising disposable incomes will support higher spending on premium hunting equipment and accessories.
- Emerging markets, particularly in Asia-Pacific and Latin America, will present new growth opportunities for the industry.
- Regulatory changes and environmental concerns may influence product development and market dynamics, requiring companies to adapt.
- Competition will intensify, with both established brands and new entrants striving to capture market share through innovation and marketing.
- Consumer demand for multi-functional and versatile hunting gear will drive product diversification and new product launches.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Popularity of Outdoor Activities
A growing interest in outdoor recreation, including hunting, is expanding the consumer base for hunting equipment and accessories. This trend is supported by rising participation rates in outdoor pursuits, driving demand for versatile and durable hunting gear.
Technological Advancements in Equipment
Innovations such as advanced optics, lightweight materials, and smart accessories are enhancing the performance and appeal of hunting gear. These advancements attract both novice and experienced hunters, broadening the market and encouraging repeat purchases.
Economic and Demographic Shifts
Rising disposable incomes and urban-to-rural migration are increasing the number of individuals engaging in hunting. Additionally, efforts to attract younger and more diverse participants are helping to sustain and grow the market.
Growth of E-commerce and Accessibility
The expansion of online platforms has made hunting equipment more accessible to a wider audience, facilitating easier product comparison and purchase. This shift is particularly significant for reaching consumers in remote or underserved regions.
Focus on Sustainability and Ethical Practices
Consumer demand for eco-friendly and ethically produced hunting gear is influencing manufacturers to adopt sustainable materials and responsible production processes. This aligns with broader environmental concerns and enhances brand reputation, supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hunting Equipment and Accessories Market?
What factors are driving the growth of the Hunting Equipment and Accessories Market?
What are the key segments within the Hunting Equipment and Accessories Market?
What are some challenges faced by the Hunting Equipment and Accessories Market?
Who are the major players in the Hunting Equipment and Accessories Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Gun and Rifle
- 1.2.2 Archery
- 1.2.3 Ammunition
- 1.2.4 Auxiliary Equipment
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Individual
- 1.3.2 Commercial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,020.14 million → 2032: USD 44,225.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hunting Equipment and Accessories Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hunting Equipment and Accessories Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hunting Equipment and Accessories Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hunting Equipment and Accessories Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hunting Equipment and Accessories Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hunting Equipment and Accessories Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hunting Equipment and Accessories Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hunting Equipment and Accessories Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,020.14 million → 2032: USD 44,225.92 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hunting Equipment and Accessories Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gun and Rifle
- 12.3.7.2 Archery
- 12.3.7.3 Ammunition
- 12.3.7.4 Auxiliary Equipment
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Individual
- 12.4.7.2 Commercial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hunting Equipment and Accessories End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hunting Equipment and Accessories Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hunting Equipment and Accessories Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hunting Equipment and Accessories Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Vista Outdoor Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sturm Ruger and Co. Inc.
- 18.4 Beretta Holding SA
- 18.5 American Outdoor Brands Corp.
- 18.6 Dick’s Sporting Goods, Inc.
- 18.7 BPS Direct LLC
- 18.8 Under Armour, Inc.
- 18.9 SPYPOINT
- 18.10 Buck Knives, Inc.
- 18.11 Spyderco, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

