
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Tactical Folding Knives Market Size 2024 | USD 1,218.9 million |
| U.S. Tactical Folding Knives Market, CAGR | 4.60% |
| U.S. Tactical Folding Knives Market Size 2032 | USD 1,746.7 million |
Market Overview
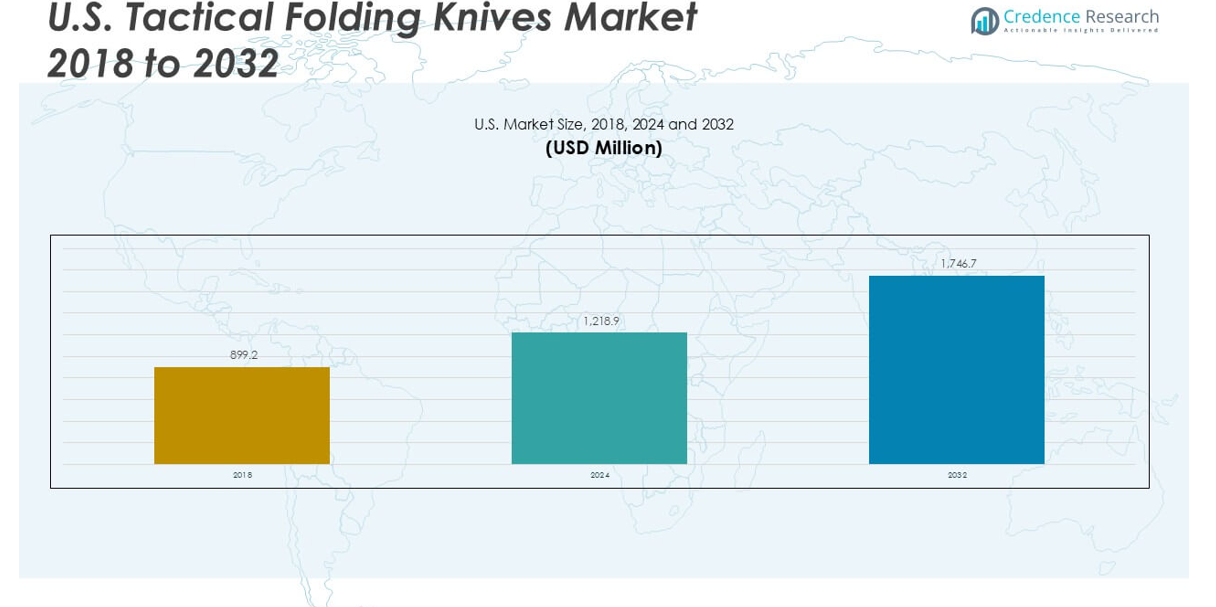
The U.S. Tactical Folding Knives market size was valued at USD 899.2 million in 2018, reached USD 1,218.9 million in 2024, and is anticipated to reach USD 1,746.7 million by 2032, at a CAGR of 4.60% during the forecast period.
The U.S. Tactical Folding Knives market is led by key players such as Benchmade Knife Company, Spyderco, Inc., Gerber Gear, Buck Knives, Inc., Zero Tolerance (ZT Knives – Kai USA), Kershaw Knives, and SOG Specialty Knives. These companies maintain strong market positions through product innovation, high-quality materials, and well-established brand loyalty among military, law enforcement, and outdoor users. The Western region dominates the market with a 35% share in 2024, driven by a strong outdoor culture and high defense activity. The Southern region follows closely, holding approximately 28% of the market share, supported by favorable regulations and a large consumer base.
Market Insights
- The U.S. Tactical Folding Knives market was valued at USD 1,218.9 million in 2024 and is expected to reach USD 1,746.7 million by 2032, growing at a CAGR of 4.60% during the forecast period.
- Growing demand from the military, defense, and outdoor recreational sectors is driving market growth, supported by rising consumer interest in durable, high-performance tactical knives.
- Increasing preference for premium materials, customizable designs, and e-commerce platforms is shaping key market trends, with online channels capturing a significant share.
- The market faces restraints due to varying state-level knife regulations, strict carry laws, and rising competition from low-cost and counterfeit products impacting brand credibility.
- Regionally, the West holds the largest market share at 35% in 2024, followed by the South at 28%, with the military and defense segment leading the application share across all regions.
Market Segmentation Analysis:
By Price Range:
In the U.S. Tactical Folding Knives market, the price range segment is divided into knives priced less than USD 40 and those priced above USD 40. The segment priced more than USD 40 dominated the market in 2024, accounting for a significant revenue share due to increasing consumer preference for high-quality, durable, and feature-rich tactical knives. These products offer superior blade materials and enhanced locking mechanisms, which appeal to military professionals, law enforcement, and outdoor enthusiasts. The demand in this segment is primarily driven by rising interest in premium performance knives for professional and recreational applications.
- For instance, Benchmade Knife Company offers tactical knives like the Benchmade 940 Osborne with a blade length of 86 mm and a thickness of 2.9 mm, utilizing CPM-S30V stainless steel for superior durability and edge retention.
By Application:
Military and defense emerged as the dominant sub-segment in 2024, holding a substantial market share. This dominance is supported by consistent government procurement and tactical requirements among armed forces and homeland security personnel. Tactical folding knives are essential for field operations, survival scenarios, and self-defense purposes in military settings. In the sales channel segment, the online platform leads the market with a considerable share. Online channels offer a wide product variety, competitive pricing, and easy accessibility, driving consumer preference. Growing reliance on e-commerce for specialty products, coupled with the convenience of doorstep delivery, has further strengthened online sales in this market.
- For instance, Gerber Gear supplies the U.S. military with tactical knives like the Propel Auto, featuring a 90 mm blade and an automatic opening mechanism, which meets specific operational standards for rapid deployment.
Market verview
Rising Demand from Military and Defense Sector
The U.S. tactical folding knives market is experiencing significant growth due to consistent demand from the military and defense sector. Tactical folding knives are essential tools for combat, survival, and field operations, making them a standard issue in many armed forces and law enforcement agencies. The versatility, portability, and multi-functional nature of these knives drive procurement initiatives. Ongoing modernization programs and increasing defense budgets further support market expansion as agencies prioritize reliable, high-performance equipment for operational efficiency and personnel safety.
- For instance, Emerson Knives, Inc. provides tactical models such as the CQC-7B, which has been in active use within the U.S. Navy SEAL teams and features a 76 mm blade with a wave-shaped opening mechanism for ultra-fast deployment
Increasing Populariy of Outdoor Recreational Activities
The growing interest in outdoor recreational activities, such as camping, hunting, and hiking, is fueling the demand for tactical folding knives in the U.S. market. Outdoor enthusiasts favor these knives for their compact design, easy handling, and multipurpose use in survival and field situations. Rising consumer awareness of self-reliance and preparedness has made tactical folding knives a preferred choice for outdoor gear. This shift in lifestyle preferences is creating strong growth opportunities for manufacturers offering lightweight, durable, and ergonomically designed products.
- For instance, Spyderco’s Paramilitary 2 offers a 3.44″ (87 mm) CPM‑S45VN blade and 3.75 oz (106 g) weight, making it a top choice among hikers and survivalists.
Expanding E-commerce and Direct-to-Consumer Channels
The rapid growth of e-commerce platforms and direct-to-consumer sales channels is significantly contributing to the market’s expansion. Online retail offers consumers a wide selection, detailed product specifications, and user reviews that influence purchasing decisions. Tactical folding knife manufacturers are leveraging online platforms to expand reach, offer customization, and engage directly with end-users. This sales strategy enhances customer loyalty, increases accessibility across the country, and allows smaller brands to effectively compete with established players, thereby stimulating market growth.
Key Trends & Opportunities
Technological Advancements in Blade and Handle Materials
The tactical folding knives market is witnessing a notable shift towards advanced materials that enhance product performance. Manufacturers are increasingly utilizing high-carbon stainless steel, titanium, and G-10 composites to improve blade sharpness, corrosion resistance, and handle durability. These innovations cater to the growing consumer demand for lightweight, robust, and long-lasting knives suitable for both professional and recreational use. Continuous research in material science presents an opportunity for companies to differentiate their offerings and capture niche customer segments.
- For instance, Zero Tolerance (ZT Knives) uses CPM-20CV steel in its ZT 0562CF model, with a 92 mm blade length, offering exceptional edge retention and corrosion resistance while incorporating a carbon fiber handle for lightweight performance.
Rising Demand for Customization and Personalization
Consumers are showing increased interest in customizable tactical folding knives that reflect personal preferences in design, blade style, and handle texture. This trend is particularly strong among hobbyists, collectors, and outdoor enthusiasts seeking unique and tailored products. Manufacturers are capitalizing on this opportunity by offering personalized engravings, interchangeable parts, and limited-edition releases. Customization not only enhances consumer satisfaction but also allows companies to command premium pricing, creating a profitable growth avenue within the market.
- For instance, Hogue, Inc. offers custom knife options with precision-machined aluminum handles and blade variations such as the Hogue X5, featuring a 102 mm blade, and allows customers to select from multiple finish and engraving options.
Key Challenges
Regulatory Restrictions and Compliance Requirements
The U.S. tactical folding knives market faces challenges due to varying state-level laws and restrictions regarding the ownership, carry, and sale of certain knife types. Strict compliance with local regulations is mandatory, particularly concerning blade length and assisted opening mechanisms. These legal complexities limit market accessibility in certain regions and can restrict distribution channels. Manufacturers and retailers must navigate a fragmented regulatory landscape, which can increase operational costs and slow market penetration.
Intense Market Competition and Price Sensitivity
The market is highly competitive with the presence of numerous domestic and international players offering a wide range of tactical folding knives. Price sensitivity among consumers, particularly in the entry-level and mid-range segments, intensifies pricing pressure on manufacturers. This competition challenges brands to balance product quality with affordability while maintaining profit margins. Smaller players may find it difficult to sustain operations without strong brand recognition or innovative product features to differentiate themselves.
Product Safety and Counterfeit Concerns
Product safety remains a critical concern in the tactical folding knives market, especially for low-cost imports and counterfeit products that may not meet industry standards. Substandard materials and poor locking mechanisms can pose significant safety risks to users. Additionally, counterfeit knives can damage brand reputation and erode consumer trust. Manufacturers need to invest in quality control, authentication technologies, and consumer education to mitigate these risks and maintain product integrity in the marketplace.
Regional Analysis
West
The Western region holds the largest share in the U.S. Tactical Folding Knives market, accounting for approximately 35% of the total market in 2024. This dominance is driven by the region’s strong military presence, widespread outdoor recreational culture, and high consumer spending on premium tactical gear. States like California and Arizona have a significant base of outdoor enthusiasts, law enforcement agencies, and defense personnel who contribute to the sustained demand. The popularity of hunting, hiking, and camping in this region further supports market growth, making the West a key contributor to overall market expansion.
South
The Southern region captures around 28% of the U.S. Tactical Folding Knives market share in 2024, supported by the region’s large military installations, hunting traditions, and a strong interest in survival gear. States like Texas and Florida are major markets due to their sizable consumer base and active defense procurement. The region also benefits from more lenient knife regulations compared to others, which encourages higher retail sales. Additionally, the Southern consumer preference for outdoor sports and tactical equipment continues to drive steady growth, positioning the South as a vital regional market for tactical folding knives.
Midwest
The Midwest holds approximately 20% of the U.S. Tactical Folding Knives market share in 2024, driven by the region’s well-established hunting culture and a growing interest in outdoor and sporting activities. States like Michigan, Wisconsin, and Ohio contribute significantly to the demand, particularly in rural and semi-urban areas where tactical knives are widely used for recreational and utility purposes. While the region exhibits moderate growth compared to the West and South, the increasing popularity of e-commerce platforms is boosting product accessibility, helping manufacturers expand their reach and tap into smaller yet consistent consumer markets.
Northeast
The Northeastern region represents about 17% of the U.S. Tactical Folding Knives market share in 2024. Growth in this region is somewhat constrained by stricter knife regulations, especially in densely populated urban centers like New York and Massachusetts, where carry restrictions limit product adoption. However, the region still maintains demand from law enforcement agencies and outdoor enthusiasts in less restrictive states. The Northeast shows potential for niche premium segments, particularly through specialty retailers and online platforms targeting collectors and professional users. Despite regulatory challenges, steady demand from security-focused consumers ensures a stable market presence.
Market Segmentations:
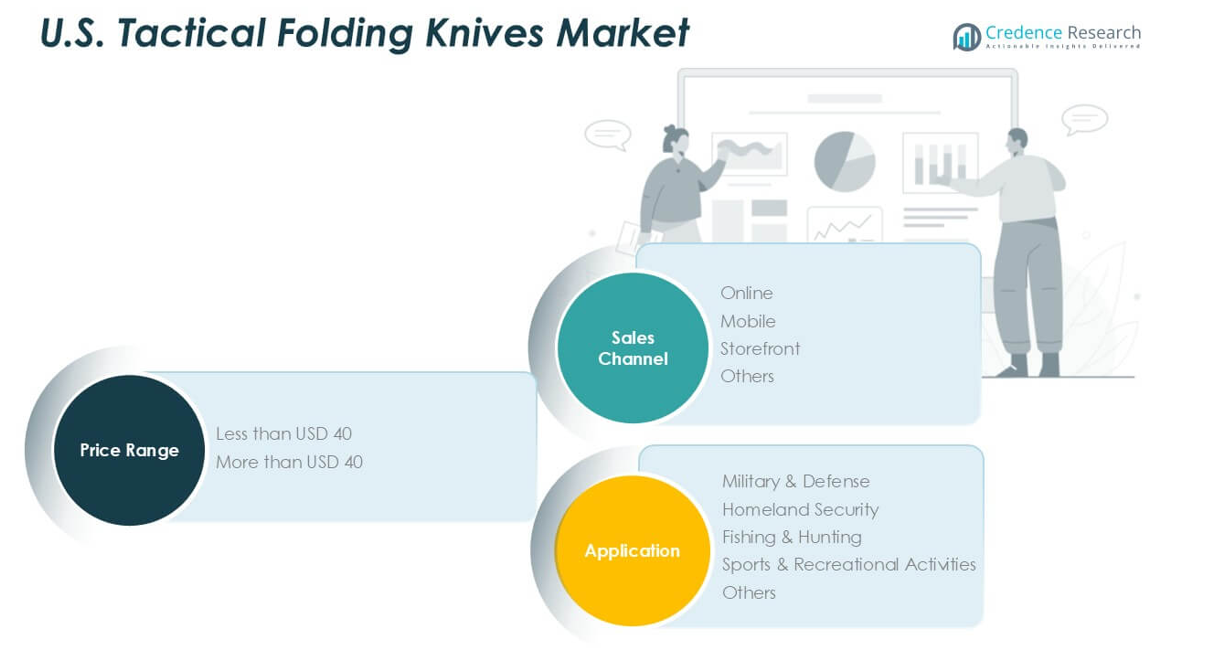
By Price Range
- Less than USD 40
- More than USD 40
By Application
- Military & Defense
- Homeland Security
- Fishing & Hunting
- Sports & Recreational Activities
- Others
By Sales Channel
- Online
- Mobile
- Storefront
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The U.S. Tactical Folding Knives market is highly competitive, with several established players dominating the landscape through product innovation, strong brand reputation, and extensive distribution networks. Key companies such as Benchmade Knife Company, Spyderco, Inc., Gerber Gear, and Buck Knives, Inc. focus on high-performance products that cater to both military professionals and outdoor enthusiasts. Competitive strategies include frequent product launches, customization options, and the use of advanced blade and handle materials to differentiate offerings. Companies like Zero Tolerance (ZT Knives – Kai USA) and Kershaw Knives are leveraging premium designs and precision manufacturing to capture niche, high-value segments. The market also sees strong competition from brands like SOG Specialty Knives, CRKT, and Cold Steel, which offer a diverse product range targeting various price points. Additionally, the increasing importance of online sales channels has intensified competition, as manufacturers aim to strengthen their digital presence and engage directly with consumers to build brand loyalty.
Key Player Analysis
- Benchmade Knife Company
- Spyderco, Inc.
- Gerber Gear
- Buck Knives, Inc.
- Zero Tolerance (ZT Knives – Kai USA)
- Kershaw Knives
- SOG Specialty Knives
- CRKT (Columbia River Knife & Tool)
- Cold Steel, Inc.
- ESEE Knives
- Emerson Knives, Inc.
- Hogue, Inc.
- TOPS Knives
- Ontario Knife Company
Recent Developments
- In June 2025, MAC Knife, Inc. launched the Matsato Knife, a premium control Japanese chef knife. Through advanced ergonomic knife design and traditional Japanese forging techniques, the Matsato Knife sets new standards in culinary precision.
- In July 2024, Yoshikin Global Corporation launched the new color “GLOBAL CAMP Black series” from “GLOBAL CAMP”. The newly added GLOBAL CAMP Black series has two types: Utility Knife and Serrated Knife. GLOBAL CAMP Black series knives use a processing technique called “oxidation coloring” to change the thickness of the stainless steel’s passive film, giving it the black color.
- In February 2024, Victorinox launched the Carving Knife Damast. This knife is made of Damasteel, produced in layers for incredible toughness, and is part of the Victorinox household knives range. With its lively Thor pattern, the Damasteel used for this knife cleverly combines corrosion resistance and superior strength.
Market Concentration & Characteristics
The U.S. Tactical Folding Knives market is shaped by intense competition, product innovation, and a growing focus on direct consumer engagement. Leading players like Benchmade Knife Company, Spyderco, Inc., Gerber Gear, and Buck Knives, Inc. dominate the market with extensive product portfolios, strong brand recognition, and consistent investment in research and development. These companies leverage advanced manufacturing techniques and high-quality materials such as stainless steel, carbon fiber, and titanium to deliver durable, precision-engineered products. Their long-standing partnerships with defense agencies and law enforcement units further strengthen their market presence. Customization and limited-edition releases have become key differentiators, allowing these companies to appeal to niche markets and command higher price points. These companies are particularly successful in reaching recreational users and the growing survivalist community. Their emphasis on ergonomic designs and multi-purpose functionality resonates well with consumers seeking reliable everyday carry (EDC) knives.
Report Coverage
The research report offers an in-depth analysis based on Price Range, Application, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. Tactical Folding Knives market is expected to grow steadily driven by rising demand from military, law enforcement, and outdoor enthusiasts.
- Increasing consumer preference for premium, durable, and customizable tactical knives will support market expansion.
- The growth of e-commerce platforms will continue to improve product accessibility and strengthen direct-to-consumer sales.
- Manufacturers will focus on developing lightweight, corrosion-resistant, and multi-functional knives using advanced materials.
- Customization and limited-edition product offerings will attract hobbyists, collectors, and survivalists seeking unique designs.
- The Western and Southern regions will maintain their dominance due to strong outdoor and defense-driven consumer bases.
- Companies will invest in online branding, customer engagement, and influencer partnerships to increase market share.
- Regulatory challenges at state levels will continue to impact product design, distribution strategies, and market entry.
- The market will face rising competition from counterfeit products, pushing manufacturers to enhance quality assurance and authentication practices.
- Partnerships with tactical sports, hunting communities, and defense training programs will emerge as key growth opportunities for manufacturers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustained Military and Defense Procurement
Consistent demand from military and defense agencies for tactical folding knives as essential field tools drives market growth, supported by modernization programs and increased defense budgets.
Rising Outdoor Recreation and Survivalist Culture
The growing popularity of outdoor activities such as camping, hunting, and hiking has increased consumer demand for durable, multi-functional tactical folding knives, especially in regions with strong outdoor traditions.
Shift Toward Premium Materials and Customization
Consumers are increasingly seeking knives made from advanced materials like high-carbon stainless steel and titanium, as well as customizable features, which supports higher price points and market expansion.
Growth of E-commerce and Direct-to-Consumer Sales
The expansion of online sales channels has improved product accessibility, allowing manufacturers to reach a broader audience, offer customization, and build brand loyalty through direct engagement.
Technological Advancements in Knife Design
Innovations in blade and handle materials, locking mechanisms, and ergonomic designs are enhancing product performance and safety, attracting both professional users and enthusiasts seeking high-quality tactical knives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Tactical Folding Knives Market?
What factors are driving the growth of the U.S. Tactical Folding Knives Market?
What are the key segments within the U.S. Tactical Folding Knives Market?
What are some challenges faced by the U.S. Tactical Folding Knives Market?
Who are the major players in the U.S. Tactical Folding Knives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Military & Defense
- 1.2.2 Homeland Security
- 1.2.3 Fishing & Hunting
- 1.2.4 Sports & Recreational Activities
- 1.2.5 Others
- 1.3 By Price Range
- 1.3.1 Less than USD 40
- 1.3.2 More than USD 40
- 1.4 By Sales Channel
- 1.4.1 Online
- 1.4.2 Mobile
- 1.4.3 Storefront
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,218.9 million → 2032: USD 1,746.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Tactical Folding Knives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Tactical Folding Knives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Tactical Folding Knives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Tactical Folding Knives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Tactical Folding Knives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Tactical Folding Knives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Tactical Folding Knives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Tactical Folding Knives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,218.9 million → 2032: USD 1,746.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Tactical Folding Knives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Military & Defense
- 12.3.7.2 Homeland Security
- 12.3.7.3 Fishing & Hunting
- 12.3.7.4 Sports & Recreational Activities
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price Range - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Less than USD 40
- 12.4.7.2 More than USD 40
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Online
- 12.5.7.2 Mobile
- 12.5.7.3 Storefront
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Tactical Folding Knives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Tactical Folding Knives Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Tactical Folding Knives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Tactical Folding Knives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Benchmade Knife Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Spyderco, Inc.
- 18.4 Gerber Gear
- 18.5 Buck Knives, Inc.
- 18.6 Zero Tolerance (ZT Knives – Kai USA)
- 18.7 Kershaw Knives
- 18.8 SOG Specialty Knives
- 18.9 CRKT (Columbia River Knife & Tool)
- 18.10 Cold Steel, Inc.
- 18.11 Emerson Knives, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

