
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Commercial Amino Acids Market Size 2024 | USD 52.77 Million |
| India Commercial Amino Acids Market, CAGR | 8.51% |
| India Commercial Amino Acids Market Size 2032 | USD 101.44 Million |
Market Overview:
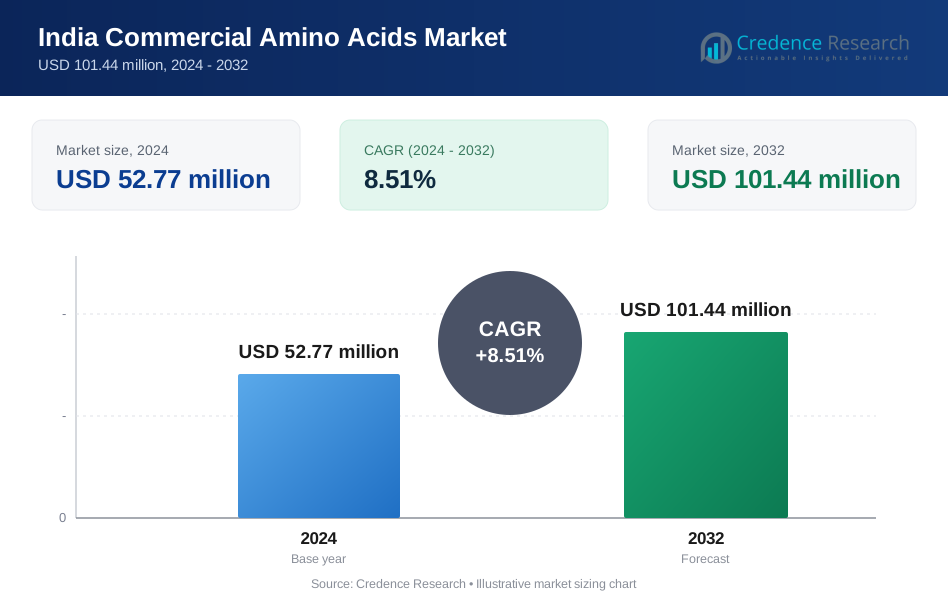
The India Commercial Amino Acids Market is projected to grow from USD 52.77 million in 2024 to an estimated USD 101.44 million by 2032, with a compound annual growth rate (CAGR) of 8.51% from 2024 to 2032.
Several key factors are driving the growth of the India commercial amino acids market. The rising consumer awareness surrounding health and nutrition has spurred a significant increase in demand for protein-rich diets and functional food products. Amino acids like lysine, glutamine, and leucine are integral to these dietary trends, being widely utilized in sports nutrition, dietary supplements, and fortified food items. Furthermore, the booming pharmaceutical sector in India increasingly incorporates amino acids into advanced drug formulations and therapies, particularly in areas such as parenteral nutrition and biopharmaceuticals. The livestock and poultry industries also contribute to this market’s growth, as amino acids are essential in animal feed formulations to improve productivity and efficiency. Additionally, increasing research and development in amino acid-based solutions and expanding applications across cosmetics and personal care products further bolster market demand.
Regionally, Northern and Western India dominate the commercial amino acids market due to the presence of large-scale pharmaceutical and nutraceutical manufacturing facilities and robust agricultural practices supporting animal feed industries. Major urban centers in these regions serve as hubs for health-conscious consumers and high-income groups, driving the demand for functional foods and dietary supplements. Meanwhile, Southern India is witnessing rapid growth, attributed to its thriving poultry industry and increasing investments in biotechnology and pharmaceutical sectors. The Eastern region, though currently a smaller contributor, holds significant potential due to the growing focus on infrastructure development and an increasing awareness of nutritional products in rural areas. The widespread distribution network and ongoing government initiatives supporting agricultural productivity and pharmaceutical research further amplify market growth across the country.
Market Insights:
- The India Commercial Amino Acids Market is projected to grow from USD 52.77 million in 2024 to an estimated USD 101.44 million by 2032, registering a robust CAGR of 8.51% during the forecast period, driven by expanding demand across multiple industries including functional foods, pharmaceuticals, and animal feed.
- Increased consumer awareness about health and nutrition has fueled the demand for amino acid-enriched dietary supplements, particularly among urban populations.
- The pharmaceutical sector is a key driver, with amino acids being extensively used in drug formulations, biopharmaceuticals, and parenteral nutrition.
- Advanced production technologies, such as fermentation and bio-based methods, are enabling cost-effective and sustainable manufacturing of high-purity amino acids.
- Expanding applications in cosmetics and personal care, including skincare and haircare products, are opening new growth avenues, especially in premium and natural product segments.
- Northern and Western India dominate the market due to their robust pharmaceutical and nutraceutical manufacturing facilities, while Southern India shows rapid growth in poultry feed and biotech industries.
- Challenges like price volatility of raw materials and limited awareness in rural areas hinder market penetration, but ongoing investments in infrastructure and marketing strategies aim to address these issues.
Market Drivers:
Growing Demand for Health and Wellness Products
The rising health consciousness among Indian consumers has been a pivotal driver for the commercial amino acids market. Increased awareness of the benefits of amino acids in muscle recovery, immunity enhancement, and overall well-being has led to a surge in demand for dietary supplements and functional foods. Products enriched with amino acids like L-Glutamine and L-Leucine have gained traction, particularly among fitness enthusiasts and health-conscious individuals. For instance, Steadfast Nutrition offers amino acid-enriched supplements like Power Protein and Incredible Whey, which are designed to support muscle recovery, immunity enhancement, and overall well-being. Additionally, the expanding availability of these products through online and offline retail channels has further boosted market growth.
Expansion of the Pharmaceutical Sector
India's booming pharmaceutical industry is significantly contributing to the growth of the commercial amino acids market. Amino acids are extensively used in drug formulations, parenteral nutrition, and biopharmaceutical production. For instance, Albert David Limited extensively uses amino acids in drug formulations, particularly in parenteral nutrition and infusion solutions. Their products, such as Alamin SE Injection and Alamin SN Injection, contain a blend of essential amino acids, which are crucial for treating conditions like cancer cachexia and malnutrition. Their application in therapies for metabolic disorders, critical care, and chronic diseases has made them indispensable in the pharmaceutical sector. Increasing investments in pharmaceutical R&D, coupled with government initiatives promoting local manufacturing under schemes like “Make in India,” have created a favorable environment for the production and application of amino acids.
Rising Demand in Animal Feed Industry
The livestock and poultry industries are key contributors to the growing demand for amino acids in India. For instance, Godrej Agrovet incorporates amino acids in their animal feed formulations to improve livestock productivity and overall health. Amino acids such as L-Lysine and DL-Methionine are essential components in animal feed formulations, improving livestock productivity and overall health. The increasing focus on sustainable agricultural practices and the need for efficient protein sources to support the growing demand for meat and dairy products have further fueled this trend. The adoption of precision feeding practices in livestock management has also driven the incorporation of amino acids in feed formulations.
Advancements in Nutraceuticals and Functional Foods
The rapid growth of the nutraceuticals and functional foods sector has created significant opportunities for the amino acids market. Indian consumers are increasingly turning to fortified foods and beverages as part of their daily diet to address nutritional gaps. For instance, Amway India has introduced amino acid-enriched products that provide essential nutrients and health benefits. Amino acids are a critical component of these products, providing essential nutrients and health benefits. Innovations in nutraceutical formulations, coupled with rising disposable incomes and urbanization, have amplified the demand for amino acid-enriched products. This trend is further supported by an increasing number of product launches targeting specific health conditions and lifestyle requirements, cementing the role of amino acids in India’s evolving food and beverage landscape.
Market Trends:
Rising Adoption of Amino Acids in Functional Foods
The growing emphasis on health and wellness among Indian consumers has driven the adoption of functional foods fortified with amino acids. With increasing awareness of the benefits of amino acids like L-Glutamine and L-Leucine in muscle recovery, immunity enhancement, and overall well-being, the demand for amino acid-enriched products has surged. For instance, a study highlighted that amino acids are essential for various physiological functions, including protein synthesis and tissue repair, making them critical for overall health. Additionally, the rise of plant-based diets has encouraged manufacturers to develop plant-derived amino acid solutions, catering to the evolving preferences of health-conscious consumers.
Technological Advancements in Production
The amino acids market in India is benefiting from advancements in production technologies, particularly in fermentation and extraction processes. These innovations enable the production of high-purity amino acids at lower costs, addressing the growing demand across industries. Research indicates that microbial fermentation techniques are being optimized to enhance amino acid yields significantly. For example, Corynebacterium glutamicum is a key organism used in industrial production due to its efficiency in producing L-glutamate and other essential amino acids. The adoption of bio-based production techniques, which are more sustainable and eco-friendly, has also gained traction. Such technologies are increasingly favored by manufacturers seeking to align with global sustainability goals and meet regulatory standards.
Expanding Applications in Cosmetics and Personal Care
Amino acids are witnessing rising demand in the cosmetics and personal care industry in India. Ingredients like L-Carnitine and L-Tryptophan are increasingly incorporated into skincare and haircare formulations for their hydration and anti-aging properties. For instance, Chicnutrix has developed products like Bounce Biotin Hair Growth Tablets, which include amino acids such as L-Carnitine and L-Tryptophan. These ingredients are incorporated for their hydration and anti-aging properties, enhancing hair health and reducing hair fall. With the Indian beauty market rapidly growing, manufacturers are focusing on amino acid-based innovations to cater to premium and natural beauty product segments, thus unlocking a new avenue for market growth.
Shift Towards Customized Nutrition Solutions
The market is also seeing a significant shift toward personalized nutrition, driven by advancements in genomics and digital health platforms. This trend enables consumers to choose amino acid supplements tailored to their specific health needs, such as fitness goals, dietary requirements, or medical conditions. For instance, companies are developing customized amino acid formulations based on individual metabolic profiles, which enhances consumer engagement and boosts brand loyalty in a competitive market. Indian manufacturers are increasingly investing in research and collaborations to develop customized amino acid formulations, particularly in the nutraceutical sector. This approach not only enhances consumer engagement but also boosts brand loyalty in a competitive market.
Market Challenges Analysis:
Price Volatility of Raw Materials
The India Commercial Amino Acids Market faces significant challenges due to fluctuations in the prices of raw materials used in amino acid production, such as agricultural feedstocks and chemical inputs. Variability in crop yields, geopolitical factors, and supply chain disruptions impact the availability and cost of these raw materials, leading to increased production costs. This volatility poses a challenge for manufacturers striving to maintain competitive pricing and profitability in a price-sensitive market.
Regulatory and Compliance Challenges
Stringent regulatory frameworks governing the production, labeling, and application of amino acids, especially in pharmaceuticals and food products, add to the complexity of market operations. Adhering to international quality standards and certifications requires substantial investment in compliance and monitoring systems. For small and medium enterprises, these regulatory hurdles can act as a barrier to market entry and expansion.
Limited Awareness in Rural Areas
Despite growing demand in urban centers, rural regions of India exhibit limited awareness of amino acid-enriched products, such as dietary supplements and animal feed. This gap in consumer education and accessibility hampers the market's potential to penetrate underserved regions. Overcoming this challenge requires robust marketing strategies and the establishment of efficient distribution networks.
Technological and Infrastructure Limitations
The lack of advanced production technologies and inadequate infrastructure for large-scale manufacturing and storage in certain regions of India limits the market’s growth potential. High initial investment costs associated with setting up state-of-the-art facilities deter new players from entering the market.
Market Opportunities:
The India Commercial Amino Acids Market presents significant growth opportunities driven by expanding applications across industries such as pharmaceuticals, food and beverages, animal feed, and cosmetics. With increasing health consciousness among Indian consumers, the demand for amino acid-enriched dietary supplements and functional foods is rising sharply. The pharmaceutical sector is also witnessing heightened adoption of amino acids for drug formulations, parenteral nutrition, and biopharmaceuticals, creating a lucrative market for pharmaceutical-grade products. Moreover, the livestock industry’s growing focus on productivity and efficiency through amino acid-based feed solutions provides ample opportunities for manufacturers catering to animal nutrition.
Additionally, emerging trends such as plant-based amino acids, sustainable production technologies, and personalized nutrition products open avenues for innovation and market expansion. The cosmetics industry also presents untapped potential, as amino acids are increasingly used in skincare and haircare formulations. Furthermore, government initiatives promoting domestic manufacturing, agricultural productivity, and research and development strengthen the market landscape, creating a favorable environment for both established players and new entrants. Expanding urbanization and rising disposable incomes further boost the demand for premium health and wellness products, ensuring sustained growth across the country.
Market Segmentation Analysis:
The India Commercial Amino Acids Market is segmented by type, application, end-use, and form, reflecting its diverse applications across industries.
By Type, key segments include L-Glutamine, L-Leucine, L-Tryptophan, L-Carnitine, and L-Arginine. Among these, L-Glutamine and L-Leucine hold significant shares due to their widespread use in dietary supplements, muscle recovery products, and pharmaceuticals. L-Tryptophan and L-Arginine are gaining traction for their role in health and wellness formulations.
By Application, the market is dominated by animal feed, food and beverages, and pharmaceuticals, with notable growth in cosmetics and nutraceuticals. Pharmaceuticals leverage amino acids for drug formulations and parenteral nutrition, while food and beverage applications focus on functional foods and protein-rich diets.
By End-Use, segments such as livestock, pet food, human nutrition, personal care, and healthcare showcase the market’s versatility. The livestock segment benefits from amino acid-based feed formulations enhancing productivity, while the human nutrition segment sees high demand for health supplements.
By Form, amino acids are available in powder, liquid, and granule forms. Powdered amino acids dominate the market due to ease of handling, storage, and blending into formulations. Liquid forms cater to specialized applications, while granules are used in animal feed and pharmaceutical products.
Segmentation:
By Type:
- L-Glutamine
- L-Leucine
- L-Tryptophan
- L-Carnitine
- L-Arginine
By Application
- Animal Feed
- FoodBeverage
- Pharmaceuticals
- Cosmetics
- Nutraceuticals
By End-use
- Livestock
- Pet Food
- Human Nutrition
- Personal Care
- Healthcare
By Form
- Powder
- Liquid
- Granules
Regional Analysis:
The India Commercial Amino Acids Market showcases regional variations in demand, driven by industrial activities, consumer preferences, and agricultural practices. Northern, Western, Southern, and Eastern India each contribute uniquely to the market's growth trajectory, with Northern and Western India holding the largest shares.
Northern India, accounting for approximately 35% of the market share, leads due to the presence of major pharmaceutical manufacturing hubs and robust agricultural practices supporting the animal feed industry. Cities like Delhi, Chandigarh, and Lucknow serve as key demand centers for functional foods, dietary supplements, and biopharmaceuticals. The region benefits from a well-established distribution network and government-backed R&D initiatives, further boosting market growth.
Western India, with around 30% of the market share, is another dominant region owing to its strong industrial base in pharmaceuticals, nutraceuticals, and food processing. States like Maharashtra and Gujarat host numerous large-scale production facilities, catering to both domestic and export markets. Additionally, the region’s urbanized population drives the demand for personal care products and fortified foods enriched with amino acids.
Southern India holds an estimated 25% share of the market, fueled by its thriving poultry industry and increasing investments in biotechnology and healthcare. Cities such as Bengaluru, Chennai, and Hyderabad are emerging as innovation hubs for amino acid applications in pharmaceuticals and cosmetics. The region’s growing health-conscious population is also driving demand for nutraceuticals and sports nutrition products.
Eastern India, contributing roughly 10% of the market share, is a smaller but growing segment. The region is witnessing increased adoption of amino acids in rural and semi-urban areas, particularly for livestock and agricultural productivity. States like West Bengal and Odisha are seeing gradual growth in pharmaceutical manufacturing and nutraceutical consumption, indicating untapped potential for market expansion.
Key Player Analysis:
- Bluestar Adisseo Co., Ltd
- Phibro Animal Health Corporation
- Meihua Holdings Group Co., Ltd
- Kemin Industries, Inc
- Ajinomoto
- RSP amino acids
- Biaffin
- AnaSpec
- ChemPep Inc
- IRIS Biotech
- PepTech Corporation
- Synthetech
- Bluestar Adisseo Co
- CJ CheilJedang Corp
- ADM
- Sinopec
- Chunming Agricultural
- Zhejiang Medicine
- Kyowa Hakko Bio
- Nutraceutics
- Evonik Industries
Competitive Analysis:
The India Commercial Amino Acids Market is marked by moderate competition, with a mix of global leaders and domestic players vying for market share. Key international companies leverage advanced production technologies, extensive R&D capabilities, and established supply chains to maintain their dominance. In contrast, domestic manufacturers focus on cost-effective production and catering to regional demand, providing stiff competition in price-sensitive segments. Major players emphasize innovation, offering high-purity and specialty amino acids tailored to diverse applications such as pharmaceuticals, animal feed, and nutraceuticals. Strategic partnerships, mergers, and acquisitions are common, aimed at expanding market presence and enhancing product portfolios. Advanced Enzyme Technologies has formed strategic partnerships and acquisitions to expand its market presence and enhance its product portfolio. For example, their acquisition of JC Biotech has strengthened their position in the amino acids market. Companies are also investing in sustainable and eco-friendly production methods to align with global trends and regulatory demands. Despite the competitive landscape, opportunities exist for new entrants driven by the rising demand for amino acids across sectors, supported by government initiatives promoting local manufacturing and R&D.
Recent Developments:
- In April 2023, Bluestar Adisseo announced plans to construct a new powder methionine plant in Fujian Province, China. This facility is expected to have an annual production capacity of 150,000 tons and aims to consolidate the company's leadership in the methionine industry. The plant is anticipated to start production in 2027, reflecting Adisseo's commitment to sustainable growth in animal nutrition.
- On December 18, 2024, Meihua Holdings announced its agreement to acquire the amino acid and Human Milk Oligosaccharide businesses from Kyowa Hakko Bio Co., Ltd. for ¥10.5 billion. This acquisition is subject to regulatory approval and is expected to significantly enhance Meihua's capabilities in producing essential amino acids and HMOs
- Kemin Industries has recently acquired Archangel Inc., a company specializing in antimicrobial solutions for the biofuel industry. This acquisition, announced on June 25, 2024, aims to expand Kemin's product offerings in bacterial control solutions for biofuel production processes
Market Concentration & Characteristics:
The India Commercial Amino Acids Market exhibits a moderately fragmented structure, with a mix of established multinational companies and emerging domestic players. The market is characterized by intense competition, driven by the growing demand for amino acids across industries such as pharmaceuticals, food and beverages, and animal feed. Leading companies focus on product innovation, cost optimization, and expanding production capacities to maintain a competitive edge. The market demonstrates a high degree of vertical integration, especially among major players who oversee production, distribution, and application-specific customization. Increasing research and development efforts are a hallmark of the industry, aimed at developing high-purity and specialty amino acids for advanced applications. Additionally, strategic collaborations and partnerships are common, fostering innovation and market expansion. The market's growth is supported by robust supply chains and government initiatives promoting domestic production, ensuring a steady supply to meet rising demand.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Application, By End-use and By Form It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is set to witness significant growth, driven by rising demand in pharmaceuticals, functional foods, and animal feed.
- Increasing consumer health awareness will fuel the adoption of amino acids in dietary supplements and protein-rich diets.
- Expansion in biopharmaceuticals and parenteral nutrition will create new opportunities for pharmaceutical-grade amino acids.
- Technological advancements in amino acid production are expected to reduce costs and enhance product quality.
- The livestock and poultry sectors will continue to be major consumers, supporting higher productivity through enriched feed formulations.
- Growing applications of amino acids in cosmetics and personal care products will further diversify market demand.
- Northern and Western India will retain dominance due to industrial infrastructure and agricultural efficiency.
- Rising investments in biotechnology in Southern India will contribute significantly to market expansion.
- Increased focus on R&D will lead to innovative amino acid-based solutions across multiple industries.
- Government initiatives promoting agricultural productivity and pharmaceutical innovation will play a key role in sustaining growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the India Commercial Amino Acids Market?
What factors are driving the growth of this market?
Which regions in India dominate the commercial amino acids market?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Commercial Amino Acids Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Commercial Amino Acids Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 52.77 million → 2032: USD 101.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Commercial Amino Acids Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Commercial Amino Acids Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Commercial Amino Acids Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Commercial Amino Acids Market Drivers
- 3.3 India Commercial Amino Acids Market Restraints & Challenges
- 3.4 India Commercial Amino Acids Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Commercial Amino Acids Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Commercial Amino Acids Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Commercial Amino Acids category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Commercial Amino Acids Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Commercial Amino Acids Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Commercial Amino Acids market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Commercial Amino Acids Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Commercial Amino Acids Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Commercial Amino Acids Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Commercial Amino Acids (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Commercial Amino Acids Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Commercial Amino Acids Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Commercial Amino Acids Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Commercial Amino Acids Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Commercial Amino Acids Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Commercial Amino Acids Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Commercial Amino Acids Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Commercial Amino Acids Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Commercial Amino Acids Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
