
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Feminine Hygiene Products market Size 2023 | USD 676.20 million |
| India Feminine Hygiene Products market, CAGR | 9.28% |
| India Feminine Hygiene Products market Size 2032 | USD 1,504.71 million |
Market Overview:
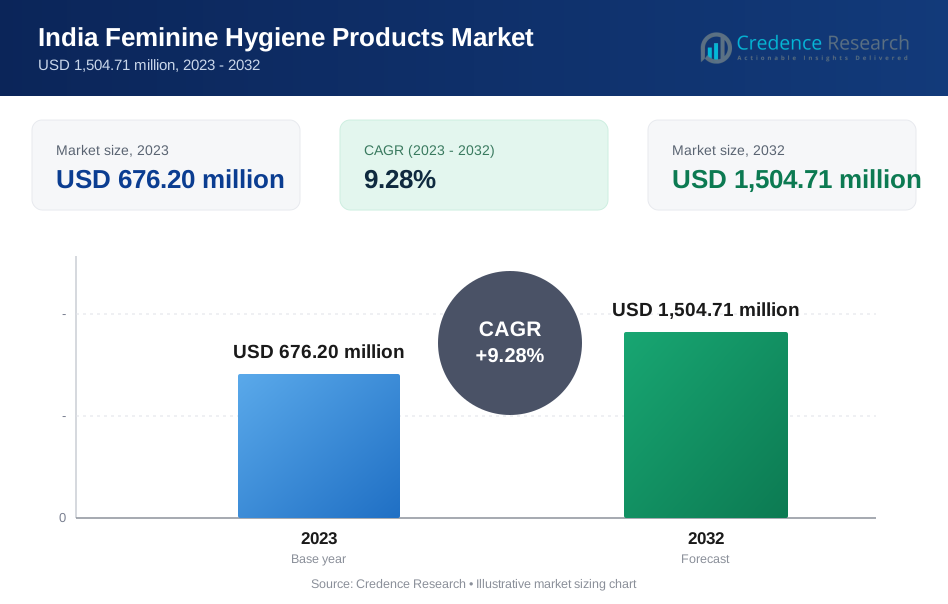
India Feminine Hygiene Products size was valued at USD 676.20 million in 2023 and is anticipated to reach USD 1,504.71 million by 2032, at a CAGR of 9.28% during the forecast period (2023-2032).
The growth of the Indian feminine hygiene products market is driven by several factors. One of the primary drivers is the evolving social norms surrounding menstruation, with reduced stigma and increased openness, allowing more women to adopt hygienic menstrual products. Government initiatives, such as "Beti Bachao, Beti Padhao," have further supported menstrual health education, empowering women and girls with the knowledge to make informed decisions about hygiene products. Additionally, the introduction of innovative and eco-friendly products, combined with better distribution channels, has made feminine hygiene products more accessible to a wider population. The rise of e-commerce platforms also plays a key role in expanding product availability, especially in areas with limited retail infrastructure, with online retail channels expected to grow rapidly in the coming years.
The usage of feminine hygiene products in India varies significantly across regions. Southern states like Tamil Nadu, Kerala, and Karnataka lead in product usage, with Tamil Nadu reaching usage rates of over 90%, supported by better infrastructure, higher literacy rates, and progressive social norms. In the Northern and Western regions, including Uttar Pradesh, Madhya Pradesh, and Gujarat, the adoption rate is moderate, ranging from 65% to 75%, where challenges such as socio-economic factors and traditional beliefs still influence product usage. The Central and Northeastern regions report the lowest usage rates, often below 65%, due to factors like limited access to hygienic products, lower education levels, and entrenched cultural taboos. Efforts to address these regional disparities require localized awareness campaigns, improved distribution networks, and community-based education initiatives to ensure broader product adoption across the country.
Market Insights:
- The Indian feminine hygiene products market was valued at USD 676.20 million in 2023 and is expected to grow to USD 1,504.71 million by 2032, reflecting a strong growth trend.
- The global feminine hygiene products market, valued at USD 23,490.00 million in 2023, is projected to reach USD 43,917.35 million by 2032, growing at a CAGR of 7.2% from 2023 to 2032.
- Evolving social norms and reduced stigma around menstruation have significantly contributed to higher adoption of hygienic menstrual products across India.
- Government initiatives such as "Beti Bachao, Beti Padhao" have played a key role in raising awareness and empowering women and girls with knowledge about menstrual health.
- The rise of e-commerce platforms is expanding the availability of feminine hygiene products, particularly in regions with limited retail infrastructure.
- Southern states like Tamil Nadu, Kerala, and Karnataka have the highest product usage rates, with Tamil Nadu reaching over 90%, due to better infrastructure and progressive social norms.
- Rural and underserved areas face challenges such as cultural taboos, limited access, and affordability, hindering product adoption and requiring targeted awareness campaigns.
- The demand for eco-friendly products like biodegradable sanitary pads and reusable menstrual cups is rising, as consumers increasingly prioritize sustainability in their purchasing decisions.
Report scope
This report segments the India Feminine Hygiene Products Market as follow: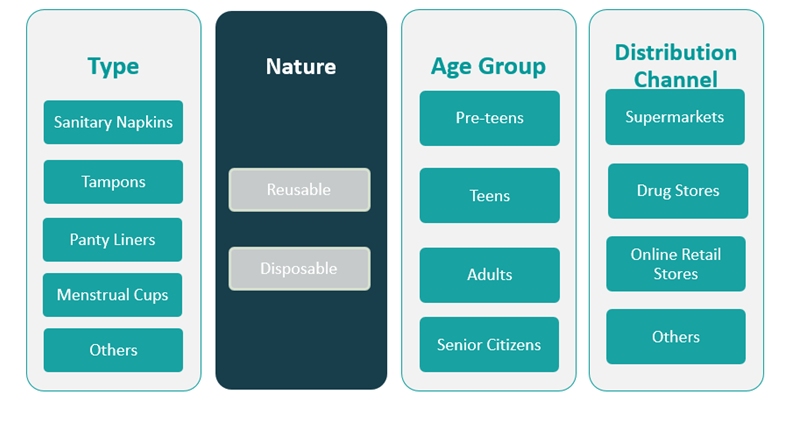
Market Drivers:
Evolving Social Norms and Awareness
A significant driver for the growth of the India feminine hygiene products market is the ongoing shift in social norms regarding menstruation. Traditionally, menstruation has been surrounded by stigma and cultural taboos, which often resulted in poor menstrual hygiene practices. However, over the past few years, there has been a growing openness and awareness surrounding menstrual health. Education programs, media campaigns, and increased social media engagement have played pivotal roles in challenging these traditional beliefs. As a result, more women are openly discussing menstruation and recognizing the importance of using hygienic products, which has directly contributed to a rise in the adoption of sanitary napkins, tampons, and other menstrual hygiene products.
Government Initiatives and Policies
Government initiatives have been a driving force in improving menstrual hygiene awareness across India. Programs such as "Beti Bachao, Beti Padhao" and government-backed campaigns to promote menstrual hygiene have significantly impacted the market. These initiatives aim to educate young girls about menstrual health and the importance of using proper hygiene products. Additionally, efforts to include menstrual hygiene education in school curricula have helped normalize the subject, further reducing stigma. The government’s proactive stance in distributing low-cost sanitary products to rural areas and its support for NGOs working in this space have also created greater access to essential products. These efforts have paved the way for a broader, more inclusive market for feminine hygiene products.
Technological Advancements and Product Innovation
Technological advancements and product innovations have made feminine hygiene products more accessible and diverse, which in turn, has spurred market growth. Manufacturers have introduced various product categories, such as eco-friendly and organic options, catering to a growing consumer base that values sustainability. Innovations like biodegradable sanitary pads and reusable menstrual cups are gaining popularity due to their environmental benefits. Sirona Hygiene, for instance, launched India’s first menstrual cup applicator in September 2023, aiming to make menstrual cups easier to use for first-time users. Furthermore, the availability of smaller, travel-friendly packaging has appealed to young women and those with busy lifestyles. The ongoing innovation in product features, such as odor control, improved absorbency, and added comfort, has helped attract a wider audience and meet the changing needs of consumers, further expanding market reach.
Rising Disposable Incomes and Urbanization
Rising disposable incomes, particularly among urban populations, have fueled the demand for premium-quality feminine hygiene products. As more women in India enter the workforce and experience greater economic independence, they are increasingly able to afford higher-end hygiene products, including organic and imported brands. Additionally, urbanization has led to increased access to a variety of feminine hygiene options, with larger retail outlets and e-commerce platforms offering an extensive range of products. For example, P&G Hygiene reported sales of Rs 4,192 crores in FY24, with femcare products contributing about 70% of the company’s revenue. The growing middle class, coupled with the rise in women’s purchasing power, has encouraged the shift from traditional and often less hygienic alternatives to more modern and convenient menstrual products. As urban populations continue to expand, the demand for superior hygiene products is expected to remain strong, driving further market growth.
Market Trends:
Shift Toward Eco-Friendly Products
A significant trend in the India feminine hygiene products market is the growing demand for eco-friendly and sustainable alternatives. As environmental awareness increases, consumers are becoming more conscious of the impact their purchasing decisions have on the planet. This shift is driving the adoption of biodegradable and reusable menstrual products, such as organic cotton pads, menstrual cups, and washable cloth pads. For instance, SanFe, an IIT Delhi startup, has developed reusable sanitary pads made from composite banana fibre, which can be used for up to two years (about 120 washes), significantly reducing waste compared to disposable pads. Traditional sanitary pads, often made from non-biodegradable materials, have been identified as a major contributor to plastic waste, prompting many to seek more sustainable options. This trend reflects a broader consumer shift towards environmentally friendly products and a growing desire to reduce personal carbon footprints.
E-commerce Growth and Online Shopping
The rapid growth of e-commerce has revolutionized the way Indian consumers purchase feminine hygiene products. Online shopping offers convenience, privacy, and a wide range of options that traditional retail stores may not provide. Consumers, particularly in urban and semi-urban areas, are increasingly turning to online platforms for their menstrual hygiene needs. For instance, Pee Safe retails through over 15,000 physical stores but also maintains a strong online presence, serving more than 700,000 registered online customers and over six million total customers. The ability to discreetly order products and have them delivered directly to one’s doorstep has been a key factor in driving this shift. As internet penetration continues to expand in rural regions, the reach of online shopping is expected to increase, further contributing to the widespread availability of feminine hygiene products.
Growing Preference for Premium and Personalized Products
Another trend shaping the market is the increasing preference for premium feminine hygiene products. As disposable incomes rise and lifestyles change, Indian consumers are increasingly willing to invest in higher-quality products that offer enhanced comfort, better absorbency, and specialized features such as hypoallergenic materials. Additionally, the demand for personalized products is on the rise, with consumers seeking menstrual care kits that cater to their specific needs. Subscription services that deliver customized products based on individual preferences are gaining popularity, as they offer both convenience and tailored solutions. This trend highlights a shift toward greater consumer control over their hygiene choices and a willingness to pay for products that enhance overall well-being.
Health and Wellness Integration
Feminine hygiene products are becoming more closely integrated with broader health and wellness trends. Consumers are increasingly aware of the connection between menstrual health and overall well-being, leading to greater interest in products that align with a holistic approach to health. Many women now prioritize natural, chemical-free options that promote better hygiene and skin health. As a result, brands are emphasizing the health benefits of their products, such as antibacterial properties and dermatologically tested materials. This focus on health-conscious products reflects a wider societal trend toward wellness, where consumers seek products that support both their physical and emotional health. The growing interest in wellness is expected to continue influencing product development and market dynamics in the feminine hygiene sector.
Market Challenges Analysis:
Cultural Taboos and Societal Stigma
Despite increasing awareness, cultural taboos and societal stigma surrounding menstruation remain significant barriers to the widespread adoption of feminine hygiene products in India. In many rural and semi-urban areas, menstruation is still considered a private and shameful subject, leading to reluctance in purchasing or using hygienic products. These cultural norms often result in the use of unhygienic alternatives like cloth, ashes, or sand, which can lead to health complications. Overcoming these deeply ingrained social stigmas requires sustained efforts in education and awareness at the grassroots level to encourage the use of sanitary products.
Limited Access in Rural Areas
Access to feminine hygiene products remains a major challenge, particularly in rural and remote regions of India. While urban centers have better infrastructure and retail outlets, rural areas often face supply chain issues that limit product availability. The lack of retail stores, coupled with financial constraints, means that many women in these areas still have limited access to hygienic menstrual products. Although government initiatives aim to provide low-cost products, distribution challenges persist, hindering widespread adoption. Increased efforts to expand the reach of these products through local vendors and mobile platforms are necessary to address this gap.
Affordability Concerns
The affordability of feminine hygiene products continues to be a challenge for many women in India, particularly in lower-income segments. While there are budget-friendly options available, many women are still unable to afford regular purchases of sanitary pads or other menstrual hygiene products. In rural areas, where economic disparities are more pronounced, the cost remains a significant barrier, even for basic sanitary products. Although low-cost options are being introduced, there is still a need for greater affordability and subsidies to make these products accessible to all socioeconomic groups.
Lack of Proper Menstrual Health Education
The lack of proper menstrual health education, particularly in rural and underserved communities, remains a key restraint. Many women, especially in rural India, are not adequately educated about menstrual hygiene, leading to poor product adoption and unhealthy practices. For instance, over 70% of girls in rural India are unaware of menstruation before their first period, leading to confusion, fear, and unhealthy practices. Without access to reliable information on the importance of menstrual health, women are less likely to make informed choices regarding hygiene products. Therefore, widespread education and awareness campaigns are essential to address this gap and encourage the use of proper menstrual hygiene solutions.
Market Opportunities:
One of the key opportunities in the Indian feminine hygiene products market lies in expanding product availability and improving distribution channels, particularly in rural and underserved regions. As internet penetration continues to increase in India, e-commerce platforms offer a significant opportunity to reach women in remote areas who may have limited access to physical retail outlets. Additionally, enhancing partnerships with local vendors, community-based organizations, and mobile distribution channels can further ensure that feminine hygiene products are accessible to a larger segment of the population. Expanding the reach of products through targeted campaigns, local retail networks, and digital platforms will be crucial in driving higher adoption rates and addressing regional disparities.
Another significant opportunity in the market is the increasing demand for eco-friendly and premium feminine hygiene products. As awareness about sustainability and environmental issues grows, there is a rising preference for organic, biodegradable, and reusable menstrual products, such as menstrual cups and organic cotton pads. This shift offers manufacturers the chance to innovate and cater to a more health-conscious and environmentally aware consumer base. Additionally, as disposable incomes rise, there is an emerging market for premium products that offer enhanced comfort, better absorbency, and hypoallergenic materials. Targeting this segment with high-quality, specialized products can lead to increased market penetration and greater consumer loyalty in the long term.
Market Segmentation Analysis:
The India feminine hygiene products market can be segmented into several categories, including product type, nature, age group, and distribution channel, each exhibiting distinct characteristics and trends.
By Type
Sanitary napkins dominate the market, driven by their widespread availability and convenience, particularly in urban and semi-urban areas. Tampons and menstrual cups, while growing in popularity, still account for a smaller portion of the market due to cultural factors and limited awareness. Panty liners are commonly used by women seeking additional comfort and protection. Other products, such as organic and eco-friendly pads, are gaining traction as more consumers prioritize sustainability.
By Nature
The market is primarily driven by disposable products, which are favored for their convenience and hygiene. However, reusable products, such as menstrual cups and cloth pads, are gradually gaining market share due to increasing environmental awareness and the cost-effectiveness of these products in the long term. The shift toward sustainability is likely to further boost the growth of the reusable segment.
By Age Group
The adult segment constitutes the largest share of the market, with women aged 18 to 45 being the primary consumers of sanitary napkins, tampons, and menstrual cups. The teen segment is growing as awareness about menstrual hygiene improves, while the pre-teen and senior citizen segments remain relatively small but are showing signs of growth due to increased education and targeted product offerings.
By Distribution Channel
Supermarkets and drug stores are the most common retail channels, with online retail stores experiencing rapid growth, particularly in urban areas. The convenience and privacy offered by e-commerce platforms are fueling this trend, making products more accessible to a wider audience. Other distribution channels, such as small local vendors, also play an essential role, particularly in rural regions.
Segmentation:
By Type
- Sanitary Napkins
- Tampons
- Panty Liners
- Menstrual Cups
- Others
By Nature
- Reusable
- Disposable
By Age-Group
- Pre-teens
- Teens
- Adults
- Senior Citizens
By Distribution Channel
- Supermarkets
- Drug Stores
- Online Retail Stores
- Others
Regional Analysis:
The Indian feminine hygiene products market displays notable regional disparities in both product adoption and market share. These variations are influenced by factors such as socio-economic conditions, cultural attitudes, infrastructure development, and consumer awareness. The market’s regional dynamics are crucial for understanding the opportunities and challenges faced by manufacturers and distributors aiming for nationwide penetration.
South India: The Leading Market
South India, particularly states like Tamil Nadu, Kerala, Karnataka, and Andhra Pradesh, leads the market with the highest adoption rates of feminine hygiene products. Tamil Nadu, for example, has one of the highest product usage rates in the country, with over 90% of women using sanitary pads. This region accounts for a significant share of the market, driven by better infrastructure, higher literacy rates, and progressive social attitudes toward menstruation. The state governments’ focus on improving menstrual hygiene awareness, along with increased urbanization, has helped foster widespread acceptance and adoption of sanitary products. South India holds a substantial market share, with the region contributing more than 30% of the total national market.
West India: Strong Market Growth
West India, including Maharashtra, Gujarat, and Rajasthan, also contributes significantly to the market, with Maharashtra being a particularly dominant state. In this region, both urban and semi-urban areas have seen rapid growth in the usage of feminine hygiene products. While there is a growing awareness of menstrual hygiene in urban centers like Mumbai and Pune, rural areas still face challenges in adoption, primarily due to affordability and access. However, with increasing disposable incomes and growing awareness campaigns, the region is experiencing a shift toward more sustainable and premium hygiene product. West India holds a market share of approximately 25%, and this is expected to rise as distribution networks expand into smaller towns and villages.
North India: Moderate Adoption
In North India, which includes states like Uttar Pradesh, Haryana, Punjab, and Delhi, the adoption rate is moderate, with many areas still grappling with cultural taboos and limited awareness. While urban areas such as Delhi and Chandigarh exhibit relatively high adoption rates, rural areas lag in product usage, often due to socio-economic barriers and traditional beliefs. This region accounts for around 20% of the overall market share. However, increasing government initiatives and NGO-led programs aimed at educating women about menstrual hygiene are gradually improving adoption rates. The growth potential in North India is significant as these awareness efforts continue to penetrate deeper into rural areas.
East and Northeast India: Lagging Behind
The Eastern and Northeastern regions of India, including states such as West Bengal, Odisha, Assam, and the seven northeastern states, have the lowest adoption rates. These regions are characterized by relatively low infrastructure development, socio-economic challenges, and cultural norms that hinder the widespread use of hygienic menstrual products. The market share of these regions is estimated to be less than 15%. However, with increased focus on healthcare education and outreach programs, there is a growing opportunity for market growth. In these areas, brands that offer affordable and locally relevant products can tap into an underserved consumer base.
Key Player Analysis:
- Johnson & Johnson
- Procter & Gamble
- Kimberly-Clark
- Essity Aktiebolag
- Kao Corporation
- Daio Paper Corporation
- Unicharm Corporation
- Premier FMCG
- Ontex
- Hengan International Group Company Ltd
- Drylock Technologies
- Natracare LLC
- First Quality Enterprises, Inc
- Sirona Hygiene
Competitive Analysis:
The Indian feminine hygiene products market is highly competitive, with both domestic and international players striving to capture market share. Key players include Procter & Gamble (with its brand Whisper), HUL (with its brand Stayfree), and Kimberly-Clark (with brands like Kotex), which dominate the market through extensive distribution networks and strong brand recognition. These companies focus on product innovation, offering a range of sanitary napkins, tampons, and menstrual cups to cater to diverse consumer needs. In addition to these established brands, numerous regional and local players are gaining ground by offering affordable, eco-friendly, and organic alternatives, appealing to the growing segment of environmentally-conscious consumers. Companies like Sirona and Saathi Pads are carving out niches by focusing on sustainability and tapping into the demand for reusable products. The competition is intensifying, driven by factors such as product differentiation, distribution expansion, and evolving consumer preferences for eco-friendly and premium options.
Recent Developments:
- In January 2025, Pee Safe, a leading Indian hygiene brand, announced a significant partnership as the official “Health & Wellbeing Partner” for the 38th National Games 2025. This collaboration is notable for its emphasis on sustainability and menstrual hygiene, marking the first time menstrual hygiene will be a central focus at the Games. Pee Safe will provide biodegradable sanitary pads, toilet seat sanitizers, and biodegradable tampons in every female athlete’s kit, and will conduct educational workshops to promote menstrual hygiene awareness among women athletes.
- In December 2024, Procter & Gamble’s Whisper brand launched the Curvewear Ultra Pad in India. Developed with feedback from thousands of women, this new product features the world’s first Curvewear Technology, designed to fit the contours of a woman’s body for enhanced comfort and protection. The Curvewear Ultra Pad aims to address common issues like leaks and discomfort, offering a soft, seamless experience. This launch reflects Whisper’s ongoing commitment to innovation and maintaining its leadership in the highly competitive Indian feminine hygiene market, which continues to see robust growth and increased consumer awareness.
Market Concentration & Characteristics:
The Indian feminine hygiene products market exhibits a moderately concentrated structure, dominated by a few multinational corporations, while also accommodating a growing number of domestic and direct-to-consumer (D2C) brands. In 2024, Procter & Gamble's Whisper held a substantial 51% market share, followed by Stayfree with approximately 21%. These leading brands leverage extensive distribution networks, strong brand recognition, and significant marketing budgets to maintain their dominance. Despite the dominance of these multinational players, the market is witnessing an influx of smaller, innovative companies focusing on niche segments such as eco-friendly products and reusable options. Brands like Sirona and Saathi Pads are gaining traction by offering biodegradable sanitary napkins and menstrual cups, catering to the environmentally conscious consumer. This diversification is indicative of a dynamic market landscape where consumer preferences are evolving towards sustainability and personalization. The market is also characterized by a high degree of regional variation in product adoption and usage patterns. Urban areas, particularly Tier 1 cities, exhibit higher penetration rates due to better infrastructure, increased awareness, and higher disposable incomes. In contrast, rural regions face challenges such as cultural taboos, limited access, and affordability issues, resulting in lower adoption rates. This disparity presents both challenges and opportunities for market expansion and tailored marketing strategies.
Report Coverage:
The research report offers an in-depth analysis based on Type, Nature, Age-Group and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The India feminine hygiene products market will continue to expand as awareness of menstrual health improves.
- Eco-friendly and sustainable product demand will increase, driven by growing environmental concerns.
- Government initiatives and NGO efforts will enhance product accessibility in rural and underserved areas.
- E-commerce will be a major growth driver, making products more accessible to women across the country.
- Premium and organic hygiene products will see rising demand as disposable incomes increase.
- Menstrual cups and reusable pads will gain traction as consumers seek more sustainable options.
- The rural market will grow significantly as awareness campaigns and distribution networks reach deeper into these regions.
- Innovation in product features such as odor control and enhanced comfort will cater to evolving consumer needs.
- Brands focusing on regional customization will capture a broader share of the market.
- Digital marketing and influencer campaigns will play a critical role in shaping consumer behavior and preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Feminine Hygiene Products Market?
What factors are driving the growth of the India Feminine Hygiene Products market?
What are the key segments within the India Feminine Hygiene Products market?
What are some challenges faced by the India Feminine Hygiene Products market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Feminine Hygiene Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Feminine Hygiene Products Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 676.20 million → 2032: USD 1,504.71 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Feminine Hygiene Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Feminine Hygiene Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Feminine Hygiene Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Feminine Hygiene Products Market Drivers
- 3.3 India Feminine Hygiene Products Market Restraints & Challenges
- 3.4 India Feminine Hygiene Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Feminine Hygiene Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Feminine Hygiene Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Feminine Hygiene Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Feminine Hygiene Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Feminine Hygiene Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Feminine Hygiene Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Feminine Hygiene Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Feminine Hygiene Products Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Feminine Hygiene Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Feminine Hygiene Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Feminine Hygiene Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Feminine Hygiene Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Feminine Hygiene Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Feminine Hygiene Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Feminine Hygiene Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Feminine Hygiene Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Feminine Hygiene Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Feminine Hygiene Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Feminine Hygiene Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
