
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Data Center Liquid Cooling Market Size 2024 | USD 247.57 Million |
| Japan Data Center Liquid Cooling Market, CAGR | 25.05% |
| Japan Data Center Liquid Cooling Market Size 2032 | USD 1480.25 Million |
Market Overview:
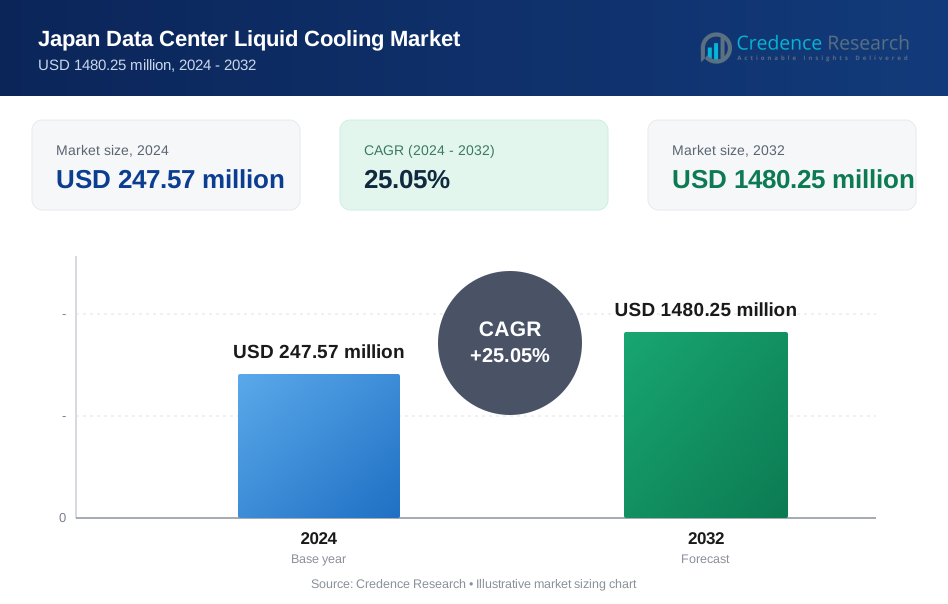
The Japan Data Center Liquid Cooling Market is projected to grow from USD 247.57 million in 2024 to an estimated USD 1480.25 million by 2032, with a compound annual growth rate (CAGR) of 25.05% from 2024 to 2032.
Key drivers fueling the growth of the Japan Data Center Liquid Cooling Market include the rising demand for efficient energy management, the increasing need for data centers to scale up operations, and the growing emphasis on reducing the environmental impact of traditional cooling methods. Liquid cooling solutions, known for their ability to manage higher heat loads compared to traditional air cooling, are particularly beneficial in addressing the thermal challenges posed by modern, high-performance computing systems. The surge in digitalization, along with government incentives promoting energy efficiency in data centers, has also played a pivotal role in pushing for the adoption of liquid cooling technologies. Additionally, the rapid advancements in liquid cooling solutions, such as immersion and direct-to-chip cooling, make them increasingly viable for diverse data center environments.
Regionally, Japan stands at the forefront of technological advancements in the Asia-Pacific region, with its robust data center infrastructure and the presence of key market players. The country’s highly developed IT industry, along with the increasing adoption of cloud computing and the Internet of Things (IoT), necessitates cutting-edge cooling solutions. Moreover, Japan is witnessing a growing trend in eco-conscious initiatives, prompting data center operators to adopt sustainable technologies, including liquid cooling systems. The Japanese government’s efforts to promote green IT practices and encourage energy-efficient data center operations are further enhancing market growth. In addition, Japan's data centers are being modernized to accommodate next-generation technologies, such as 5G, which require innovative and efficient cooling solutions. This trend is expected to drive continued demand for liquid cooling technologies in the coming years.
Market Insights:
- The Japan Data Center Liquid Cooling Market is projected to grow from USD 247.57 million in 2024 to USD 1480.25 million by 2032, with a CAGR of 25.05%.
- Key growth drivers include the increasing demand for energy-efficient solutions and the growing need for data centers to scale operations efficiently.
- Rising digitalization, high-performance computing, and AI applications are intensifying the demand for advanced cooling technologies.
- Government regulations and incentives promoting energy efficiency and sustainability are encouraging the adoption of liquid cooling solutions.
- Technological advancements in immersion and direct-to-chip cooling systems are enhancing the effectiveness and cost-effectiveness of liquid cooling.
- Japan’s highly developed IT infrastructure and growing eco-conscious initiatives are driving the regional adoption of liquid cooling systems.
- Despite growth potential, challenges such as high initial investment costs, technical expertise requirements, and compatibility with legacy systems may limit adoption in some sectors.
Market Drivers:
Increasing Demand for Energy-Efficient Cooling Solutions
One of the key drivers behind the growth of the Japan Data Center Liquid Cooling Market is the escalating demand for energy-efficient cooling solutions. As data centers continue to expand and handle more computational tasks, the need to manage the significant amount of heat generated becomes paramount. Traditional air cooling methods are reaching their limits in terms of efficiency, particularly as servers and IT infrastructure become more powerful and densely packed. Liquid cooling systems, which offer better heat dissipation, are increasingly seen as the ideal solution for meeting the rising demand for energy efficiency while also improving cooling performance. For instance, immersion cooling can reduce cooling energy use by up to 95%, significantly impacting data center energy consumption, where cooling typically accounts for about 40% of total energy use. With energy consumption becoming a focal point in global sustainability efforts, liquid cooling systems help data centers achieve better power usage effectiveness (PUE), making them an attractive alternative.
Growth in High-Performance Computing and Digitalization
The rapid advancement of high-performance computing (HPC), cloud computing, artificial intelligence (AI), and big data analytics has significantly contributed to the growth of the Japan Data Center Liquid Cooling Market. These technologies place higher demands on data centers, not just in terms of processing power but also with respect to their cooling requirements. As the heat generated by densely packed high-performance servers increases, traditional cooling systems often fall short in effectively managing such loads. Liquid cooling systems, which can handle higher heat levels more efficiently, are thus becoming indispensable for data centers focused on emerging technologies. The expanding adoption of cloud-based services, data storage solutions, and digital transformation initiatives further drives the need for efficient and sustainable cooling methods in data centers.
Government Regulations and Environmental Incentives
Government regulations and environmental incentives play a crucial role in promoting the adoption of liquid cooling solutions in Japan's data center sector. Japan has been at the forefront of pushing for greener technology, and its regulatory landscape encourages businesses to adopt energy-efficient solutions. The government's emphasis on reducing carbon footprints and enhancing sustainability across industries has led to the introduction of policies that directly impact data center operations. For instance, the Japanese Government’s Green Growth Strategy, introduced in 2021, mandates a 30% reduction in energy consumption for data centers by 2030. These policies often require data centers to adopt more environmentally friendly technologies, including advanced cooling solutions. Liquid cooling systems, with their reduced energy consumption and lower environmental impact, are well-aligned with these regulations, prompting data center operators to transition to such solutions to comply with regulatory requirements and reduce their ecological footprint.
Technological Advancements in Liquid Cooling Systems
Technological advancements in liquid cooling systems are also driving their adoption in Japan’s data center market. Over the years, liquid cooling solutions have evolved significantly, with innovations such as immersion cooling and direct-to-chip cooling becoming more viable for large-scale data centers. These advancements have not only improved the efficiency and effectiveness of liquid cooling but have also made it more cost-effective and adaptable to a broader range of data center environments. As the performance and scalability of liquid cooling systems improve, data center operators are increasingly turning to these solutions to enhance their infrastructure. The continuous development of new cooling techniques is expected to support the ongoing growth of the market, providing operators with flexible and efficient options to meet their cooling needs.
Market Trends:
Adoption of Immersion Cooling Technology
A prominent trend in the Japan Data Center Liquid Cooling Market is the growing adoption of immersion cooling technology. This technique involves submerging servers or other computing hardware in a dielectric liquid that absorbs and dissipates heat more efficiently than air. For instance, KDDI Corporation has developed a "container-type immersion cooling small data center" that employs single-phase immersion cooling, reducing power consumption by 43% and lowering the Power Usage Effectiveness (PUE) below 1.07. Immersion cooling is gaining traction due to its ability to handle extremely high heat densities, which is becoming increasingly common with the rise of high-performance computing (HPC) and artificial intelligence workloads. Japan, with its focus on technological innovation and sustainability, is seeing a shift towards immersion cooling solutions in both new and retrofitted data centers. This technology offers not only superior cooling efficiency but also space savings, as it reduces the need for large, traditional air-based cooling units.
Integration of Liquid Cooling with Renewable Energy Sources
A growing trend in Japan’s data center liquid cooling market is the integration of cooling systems with renewable energy sources. As Japan moves towards carbon neutrality and adopts more sustainable business practices, the use of green energy is becoming increasingly important for data centers. Many data center operators are now looking to integrate liquid cooling systems with renewable energy sources such as solar or wind power. Liquid cooling systems, known for their energy efficiency, can further optimize the energy use when paired with renewable energy, resulting in a significant reduction in carbon emissions. This integration aligns with Japan’s commitment to sustainability and allows data centers to run with minimal environmental impact, making it an attractive proposition for businesses looking to meet global environmental standards.
Shift Towards Edge Computing and Distributed Data Centers
Another notable trend is the shift towards edge computing and distributed data centers, which is influencing the demand for liquid cooling solutions in Japan. Edge computing, which involves processing data closer to the source of generation rather than in centralized data centers, requires efficient cooling systems to manage heat dissipation in smaller, decentralized facilities. As edge computing becomes more prevalent in industries such as autonomous vehicles, Internet of Things (IoT), and 5G, there is a rising need for compact and highly efficient cooling solutions. Liquid cooling systems, particularly direct-to-chip and immersion cooling technologies, are proving to be ideal solutions for edge data centers due to their ability to manage heat effectively in space-constrained environments.
Development of Hybrid Cooling Solutions
The development of hybrid cooling solutions, which combine both liquid and air cooling methods, is gaining popularity in the Japan Data Center Liquid Cooling Market. Hybrid systems offer the flexibility to use both cooling technologies depending on the operational needs of the data center. These systems can optimize the use of liquid cooling during high-density workloads or warmer conditions while relying on traditional air cooling when temperatures are lower or during off-peak times. For example, Mitsubishi Heavy Industries has developed a hybrid cooling system capable of housing servers using immersion, air, and water-cooling methods simultaneously. This trend provides data center operators with a cost-effective solution that adapts to fluctuating needs, offering both energy efficiency and scalability. As data centers seek more adaptable and versatile cooling options, hybrid systems are increasingly being viewed as a solution that balances performance with operational flexibility.
Market Challenges Analysis:
High Initial Investment Costs
One of the primary restraints in the Japan Data Center Liquid Cooling Market is the high initial investment required for implementing liquid cooling systems. Compared to traditional air cooling systems, liquid cooling solutions, particularly immersion cooling, demand significant upfront costs in terms of hardware, installation, and maintenance. These systems often require specialized infrastructure and trained personnel, which can increase both the capital expenditure and operational expenses for data center operators. For smaller businesses or those with limited budgets, the adoption of liquid cooling systems may be viewed as cost-prohibitive, thereby limiting market penetration.
Technical Expertise and Training
Another challenge in the Japan Data Center Liquid Cooling Market is the requirement for specialized technical expertise and training. Liquid cooling systems are more complex to manage and maintain than traditional air-based cooling methods. The successful operation of these systems demands skilled personnel who are well-versed in both the installation and ongoing maintenance processes. For example, NTT Data has established a verification facility to promote the use of liquid cooling technology, which includes training for maintenance workers to address the need for skilled personnel. Additionally, as liquid cooling technologies such as immersion cooling and direct-to-chip solutions evolve, data center operators must invest in continuous training and development for their staff. The shortage of professionals with the necessary expertise can hinder the adoption and efficient operation of liquid cooling systems, especially for smaller or less technologically advanced data centers.
Compatibility with Existing Infrastructure
The integration of liquid cooling solutions into existing data center infrastructures presents another significant challenge. Many legacy data centers are equipped with air cooling systems that may not be easily adaptable to liquid cooling technologies. Retrofitting these facilities to accommodate liquid cooling requires substantial changes to the existing layout, cooling units, and even server hardware. This can result in downtime and additional costs, discouraging data center operators from making the switch to liquid cooling solutions. The complexity of retrofitting existing facilities may thus slow the widespread adoption of liquid cooling technologies in the market.
Market Awareness and Perception
A lack of awareness and understanding of the benefits and functionality of liquid cooling systems is another challenge. Many businesses are still unfamiliar with the advantages of liquid cooling over traditional air-based methods, such as energy efficiency and better heat management. Misconceptions about the complexity and reliability of liquid cooling solutions can hinder decision-makers from making the transition. Increasing market education and providing case studies demonstrating the benefits of liquid cooling technologies are essential to overcoming this perception barrier and encouraging wider adoption.
Market Opportunities:
The Japan Data Center Liquid Cooling Market presents significant opportunities driven by the increasing demand for energy-efficient, high-performance cooling solutions. As Japan’s data centers continue to evolve, the need for advanced cooling technologies that can support high-density servers and modern computing workloads is growing. Liquid cooling systems, particularly immersion and direct-to-chip solutions, offer superior efficiency in heat dissipation compared to traditional air cooling methods. This creates a substantial market opportunity for businesses to adopt liquid cooling solutions to enhance energy efficiency, reduce operational costs, and comply with stringent sustainability regulations. Moreover, Japan’s push toward carbon neutrality and the adoption of green energy initiatives provides an excellent opportunity for liquid cooling providers to offer sustainable solutions that align with both environmental goals and energy-saving objectives.
Additionally, the increasing shift toward edge computing and distributed data centers in Japan further expands the market opportunities for liquid cooling solutions. As businesses embrace edge computing to process data closer to its source, smaller, decentralized data centers will require compact and efficient cooling technologies. Liquid cooling systems are ideal for these types of environments due to their ability to efficiently manage heat in space-constrained areas. As Japan continues to invest in 5G networks, IoT devices, and other digital infrastructures, the demand for edge data centers will continue to rise, creating new opportunities for liquid cooling providers to meet the evolving needs of the market. This shift to edge computing, combined with the growing focus on sustainability, positions liquid cooling technologies as a key enabler of future data center growth in Japan.
Market Segmentation Analysis:
The Japan Data Center Liquid Cooling Market is segmented across various dimensions, offering a comprehensive view of its dynamics.
By Type Segment:
The market is divided into Direct Liquid Cooling and Indirect Liquid Cooling. Direct Liquid Cooling systems, which involve directly cooling the IT components, are gaining popularity due to their higher efficiency in managing heat loads. They are commonly used in high-performance computing environments. Indirect Liquid Cooling, on the other hand, is more widely deployed in traditional data centers, where the cooling system does not directly contact the IT equipment but instead cools the environment, offering a more cost-effective solution for standard applications.
By Application Segment:
The market also sees differentiation in terms of applications, including IT Equipment Cooling, Power Supply Cooling, UPS Cooling, and others. IT Equipment Cooling holds the largest share, as effective cooling of servers and processors is crucial for ensuring optimal performance and reliability. Power Supply Cooling and UPS Cooling are essential in maintaining uninterrupted power supply and minimizing downtime in data centers.
By Component Segment:
The components segment includes Chillers, Cooling Distribution Units, Heat Exchangers, Pumps, and others. Chillers dominate this segment, as they are integral to regulating temperature in large data centers. Heat Exchangers and Cooling Distribution Units also play crucial roles in managing and distributing cooling across the facility.
By Industry Vertical Segment:
In terms of industry verticals, the IT and Telecom sector is the largest user of data center liquid cooling solutions, driven by the significant infrastructure requirements of cloud services and telecommunications. The BFSI, Government, and Healthcare sectors are also significant contributors, as they require highly secure and efficient data storage and processing capabilities. The demand from these sectors is expected to grow as data security and regulatory requirements become more stringent.
Segmentation:
By Type Segment:
- Direct Liquid Cooling
- Indirect Liquid Cooling
By Application Segment:
- IT Equipment Cooling
- Power Supply Cooling
- UPS Cooling
- Others
By Component Segment:
- Chillers
- Cooling Distribution Units
- Heat Exchangers
- Pumps
- Others
By Industry Vertical Segment:
- BFSI
- IT and Telecom
- Government
- Healthcare
- Others
Regional Analysis:
The Japan Data Center Liquid Cooling Market is primarily driven by the country's robust technological infrastructure and the increasing demand for energy-efficient and sustainable solutions in data centers. Japan, being one of the leading markets for high-performance computing, cloud services, and digital transformation, has seen substantial growth in the adoption of advanced cooling technologies. As of 2024, Japan holds a significant share of the overall Asia-Pacific (APAC) Data Center Liquid Cooling Market, with a market share of approximately 22%. This dominant position is supported by Japan’s large number of data centers, the country’s focus on energy efficiency, and the government's strong regulatory push for sustainable practices across industries.
Japan's urban areas, including Tokyo, Osaka, and Yokohama, serve as the major hubs for data center operations, driving the demand for liquid cooling systems in these regions. Tokyo, being the country's technological and economic center, accounts for the largest portion of market demand. The city’s dense concentration of data centers, coupled with the need for high-density computing solutions, has accelerated the shift toward liquid cooling technologies. The Japanese government’s proactive stance on climate change and energy efficiency, which includes incentives for adopting greener technologies, further supports market growth in these metropolitan areas. As a result, the demand for liquid cooling systems in Tokyo and other urban centers is expected to remain strong throughout the forecast period.
Outside of Tokyo, regions such as Osaka and Fukuoka are also experiencing increased investments in data center infrastructure. These areas are benefiting from the growth of regional cloud and edge computing centers, which require efficient cooling solutions to manage the higher heat loads of localized computing. Although these regions contribute less to the market share compared to Tokyo, they represent significant growth opportunities due to the expansion of digital infrastructure outside major metropolitan areas. By 2030, these regions are anticipated to account for roughly 25% of the total Japan Data Center Liquid Cooling Market, reflecting the continued growth of distributed computing technologies.
Key Player Analysis:
- Huawei Technologies
- Vertiv
- Schneider Electric
- LiquidCool Solutions
- CoolIT Systems
- Rittal
- Asetek
- Stulz
- Fujitsu
- Inspur Systems
Competitive Analysis:
The Japan Data Center Liquid Cooling Market is highly competitive, with several key players driving innovation and market expansion. Prominent companies such as Vertiv, Asetek, Schneider Electric, and Rittal are at the forefront, offering advanced liquid cooling solutions tailored to the growing demands of data center operators. These companies focus on developing energy-efficient and sustainable cooling systems, including immersion and direct-to-chip cooling technologies, which are gaining traction in Japan due to their superior performance and environmental benefits. Additionally, local players like Fujitsu and NEC are also expanding their presence by integrating liquid cooling solutions into their data center offerings, aligning with Japan’s emphasis on energy efficiency and sustainability. As competition intensifies, companies are increasingly differentiating themselves through technological advancements, cost-efficiency, and compliance with environmental regulations. The market is also witnessing strategic partnerships and acquisitions as companies look to strengthen their position in the growing demand for liquid cooling technologies.
Recent Developments:
- In November 2024, NTTlaunched two significant liquid cooling deployments in Japan. NTT Data established a demonstration data center, known as the Data Center Trial Field, in Noda City, Chiba Prefecture, to verify the design and deployment of liquid cooling systems. Meanwhile, NTT Communications began testing two-phase direct-to-chip cooling in an existing air-cooled facility. This initiative aims to enhance the efficiency and interoperability of liquid cooling technologies in data centers.
- In March 2023, Interactive, a managed service provider, introduced its Immersion Data Center Cooling solution in collaboration with Vertiv. This solution integrates green revolution cooling tanks that use a single-phase, non-conductive coolant, enhancing high-performance computing capabilities for clients.
Market Concentration & Characteristics:
The Japan Data Center Liquid Cooling Market exhibits moderate concentration, with a mix of global players and regional companies competing for market share. Key international companies such as Vertiv, Schneider Electric, and Asetek dominate the market, leveraging their technological expertise and global presence. These players lead the innovation in high-performance cooling solutions, such as immersion cooling and direct-to-chip cooling, positioning themselves as market leaders. In addition to global players, local companies like Fujitsu and NEC contribute to the market, offering tailored solutions that cater to Japan's specific regulatory and environmental requirements. The market is characterized by a high degree of technological differentiation, with a focus on energy-efficient, sustainable cooling solutions. Given the country’s emphasis on sustainability and energy efficiency, companies must continually innovate to meet evolving demand. Strategic partnerships, acquisitions, and localized service offerings are common strategies to enhance competitiveness in this growing market.
Report Coverage:
The research report offers an in-depth analysis based on Type Segment, By Application Segment, By Component Segment and By Industry Vertical Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Japan Data Center Liquid Cooling Market is expected to continue growing at a robust CAGR, driven by increasing energy efficiency demands.
- Adoption of high-performance computing technologies like AI and big data will further increase the need for advanced cooling systems.
- Government incentives promoting sustainability will boost the transition to eco-friendly cooling solutions.
- The rise of edge computing and distributed data centers will create new opportunities for liquid cooling technologies in smaller, decentralized locations.
- Technological advancements in immersion and direct-to-chip cooling will enhance cooling efficiency, reducing operational costs.
- Increased data privacy regulations will prompt sectors like BFSI and government to invest in advanced cooling solutions to meet compliance.
- The growing shift towards renewable energy sources will drive the integration of liquid cooling with green energy solutions.
- Key market players will focus on strategic partnerships and acquisitions to expand their market presence and technological capabilities.
- Regional players will increasingly cater to local requirements with customized solutions tailored to Japan's unique needs.
- By 2030, liquid cooling technologies are expected to become a standard feature in data centers across Japan due to their long-term cost benefits.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Data Center Liquid Cooling Market?
What factors are driving the growth of the Japan Data Center Liquid Cooling Market?
What are the key segments within the Japan Data Center Liquid Cooling Market?
What are some challenges faced by the Japan Data Center Liquid Cooling Market?
Who are the major players in the Japan Data Center Liquid Cooling Market?
Which segment is leading the Japan Data Center Liquid Cooling Market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Data Center Liquid Cooling Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Data Center Liquid Cooling Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 247.57 million → 2032: USD 1480.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Data Center Liquid Cooling Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Data Center Liquid Cooling Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Data Center Liquid Cooling Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Data Center Liquid Cooling Market Drivers
- 3.3 Japan Data Center Liquid Cooling Market Restraints & Challenges
- 3.4 Japan Data Center Liquid Cooling Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Data Center Liquid Cooling Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Data Center Liquid Cooling Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Data Center Liquid Cooling category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Data Center Liquid Cooling Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Data Center Liquid Cooling Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Data Center Liquid Cooling market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Data Center Liquid Cooling Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Data Center Liquid Cooling Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Data Center Liquid Cooling Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Data Center Liquid Cooling (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Data Center Liquid Cooling Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Data Center Liquid Cooling Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Data Center Liquid Cooling Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Data Center Liquid Cooling Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Data Center Liquid Cooling Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Data Center Liquid Cooling Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Data Center Liquid Cooling Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Data Center Liquid Cooling Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Data Center Liquid Cooling Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
