
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Safety Eyewear Market Size 2024 | USD 199.38 million |
| Japan Safety Eyewear Market, CAGR | 6.69% |
| Japan Safety Eyewear Market Size 2032 | USD 334.66 million |
Market Overview
The Japan Safety Eyewear market size was valued at USD 199.38 million in 2024 and is anticipated to reach USD 334.66 million by 2032, at a CAGR of 6.69% during the forecast period (2024-2032).
[Japan Safety Eyewear] market drivers include stringent workplace safety regulations imposed by the Industrial Safety and Health Act, rising manufacturing and construction activity, and heightened awareness of occupational hazards among employers. Rapid growth in sectors such as automotive and electronics propels demand for advanced protective eyewear with anti-fog, scratch-resistant, and impact-resistant coatings. An ageing workforce drives the adoption of ergonomically designed frames that deliver comfort during prolonged use. Manufacturers leverage digitalization by integrating heads-up displays, sensor-based hazard alerts, and augmented reality features to enhance real-time safety monitoring. Meanwhile, online sales channels and B2B e-procurement platforms streamline procurement processes for small and medium enterprises. Sustainability initiatives encourage the use of eco-friendly materials and reusable designs, aligning with government targets for waste reduction. Strategic collaborations between global brands and domestic distributors foster product innovation. Looking ahead, increasing investment in smart safety solutions and virtual fitting tools will further shape market trends.
Industrial clusters in Japan, including Kanto around Tokyo-Yokohama, Kansai spanning Osaka-Kobe, and Chubu centered on Nagoya, form the backbone of regional demand for protective eyewear, supported by heavy manufacturing, automotive assembly, and electronics production. Kyushu’s shipbuilding and semiconductor sectors sustain consistent orders for high-performance lenses, while Tohoku’s mining and rural construction projects drive demand for impact-resistant and anti-fog designs. Hokkaido’s cold-climate operations require specialized treatments to prevent lens fogging, and Shikoku’s agricultural and chemical industries prefer splash-resistant frames. Key players such as MCR Safety, Honeywell International Inc., 3M, Scott Safety (Tyco), DEWALT, and Radians maintain extensive distribution networks and regional sales offices to address these diverse needs. The Japan Safety Eyewear Market benefits from partnerships with local distributors and e-commerce platforms that serve hard-to-reach areas. Emerging tech hubs in northern zones also pilot augmented-reality eyewear solutions. It fosters on-site fitting services and targeted product training to ensure compliance with region-specific safety protocols and workplace environments.
Market Insights
- The Japan Safety Eyewear market size was valued at USD 199.38 million in 2024 and is anticipated to reach USD 334.66 million by 2032.
- The Global Safety Eyewear Market was valued at USD 4,244.64 million in 2024 and is projected to reach USD 6,806.27 million by 2032, growing at a CAGR of 6.08% during the forecast period.
- Strict Industrial Safety and Health Act requirements drive broad adoption of anti-fog, scratch-resistant, and impact-resistant eyewear across manufacturing, construction, and automotive sectors, compelling suppliers to enhance quality control processes, secure compliance certifications, and drive product innovation efforts.
- Integration of heads-up displays, augmented reality overlays, and sensor-enabled hazard alerts delivers real-time safety monitoring on the shop floor, supports predictive risk management, promotes proactive intervention in automated assembly and high-risk tasks, and reduces workplace incidents significantly.
- Expansion of e-commerce portals and B2B digital procurement platforms accelerates order processing for small and medium enterprises, improves inventory visibility, extends market reach into remote industrial parks and emerging regional clusters, and negotiates bulk pricing with suppliers.
- Intense price competition from low-cost imports challenges domestic brands, forcing them to differentiate through advanced material technologies, ergonomic design features, bundled after-sales services, localized customer support, and leverage R&D partnerships for differentiation.
- High compliance costs for repeated certification testing, frequent regulatory updates, and complex audit procedures constrain new product introductions by smaller suppliers, boosting consolidation among established players, encouraging strategic partnerships to share compliance burdens, and trigger consolidation in niche segments.
- Kanto, Kansai, and Chubu regions drive over two-thirds of demand due to concentrated electronics, automotive, and precision manufacturing hubs; Kyushu, Tohoku, and other regions show niche growth in shipbuilding, semiconductor, agriculture, and remote construction applications, and attract OEM partnerships for specialized applications.
Report Scope
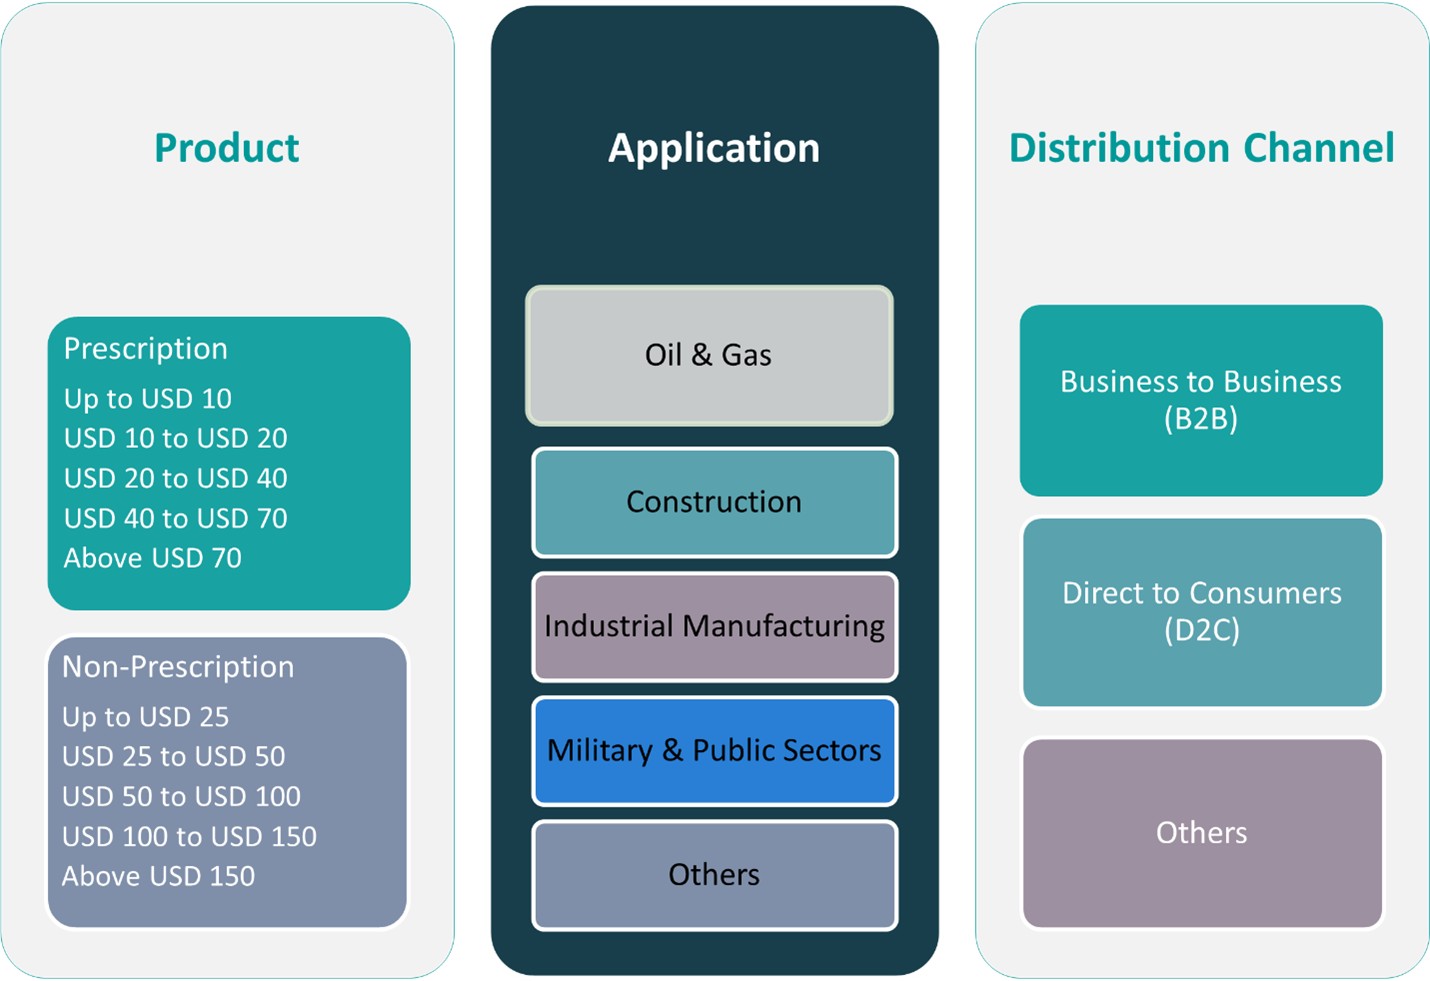
This report segments the Japan Safety Eyewear Market as follows:
Market Drivers
Regulatory Requirements and Compliance Driving Market Growth
Government mandates under the Industrial Safety and Health Act drive demand for certified protective eyewear across various sectors. The Japan Safety Eyewear Market responds by aligning product portfolios with strict standards for impact resistance and lens clarity. Manufacturers invest in quality control processes to meet frequent inspections by regulatory bodies. Companies seek certifications to ensure compliance across production lines. It improves buyer confidence among large enterprises and small businesses alike. Increased audit frequencies prompt providers to maintain rigorous documentation and traceability. Industry associations collaborate with suppliers to update compliance guidelines.
- For instance, Japan's Industrial Safety and Health Act mandates strict workplace safety measures, leading to increased adoption of certified protective eyewear.
Industrial Expansion Fueling Protective Eyewear Demand
Rapid growth in manufacturing and automotive production drives higher demand for safety eyewear in Japan. The Japan Safety Eyewear Market records increased orders from electronics, automotive, and metal fabrication firms. Company procurement teams prioritize anti-fog and scratch-resistant lenses to maintain productivity under harsh operating conditions. It compels suppliers to diversify material sourcing to meet large-volume requirements. Construction projects and plant expansions generate steady procurement cycles. OEM partnerships ensure streamlined product integration in industrial safety programs. Market players develop tiered product lines to serve both large corporations and small enterprises.
- For instance, Japan's expanding industrial sector, particularly in automotive and electronics manufacturing, is driving demand for high-performance safety eyewear.
Adoption of Smart Features Enhancing User Safety
Sensor-enabled hazard alerts and heads-up displays deliver real-time safety monitoring for users in high-risk environments. The Japan Safety Eyewear Market integrates augmented reality overlays that highlight operational hazards. Engineers configure embedded electronics to trigger visual and auditory warnings when safety thresholds breach. It supports proactive risk management and reduces incident rates at manufacturing plants. Updates permit feature enhancements without hardware replacement. Distributors offer virtual fitting tools to optimize lens selection and frame adjustments. Collaborative R&D efforts between tech firms and eyewear manufacturers accelerate feature rollout.
Ergonomic Comfort and Sustainable Material Adoption
Ergonomic frame designs reduce fatigue during extended shifts in manufacturing and construction settings. The Japan Safety Eyewear Market introduces lightweight polymers and flexible hinges to deliver improved fit. Companies test multiple form factors to address facial variability across the workforce. It encourages prolonged wear and enhances user compliance with safety protocols. Suppliers adopt recycled plastics and biodegradable components to meet sustainability targets. Design teams work with material scientists to verify durability under stress. Market participants publish environmental impact reports to inform corporate buyers.
Market Trends
Digital Transformation and E-Commerce Expansion
Industry participants deploy online platforms to reach customers and distributors directly. Japan Safety Eyewear Market players launch integrated web portals for both B2B and B2C transactions. They refine user interfaces to support virtual product demonstrations and accurate fittings. It improves order accuracy and reduces procurement cycle times. Companies adopt real-time inventory tracking to enhance supply chain visibility. Distributors publish digital catalogs that highlight new lens coatings and frame technologies. This shift accelerates market penetration in remote regions.
- For instance, the Japanese government is actively promoting digitalization, incentivizing the development of leading-edge technologies to enhance e-commerce accessibility.
Integration of Smart Technologies for Enhanced Safety
Innovators embed sensors into frames to detect impacts and issue on-the-spot alerts. The Japan Safety Eyewear Market responds with augmented reality overlays that highlight machinery status and workspace hazards in real time. It delivers live data feeds to maintenance technicians and assembly-line operators. Manufacturers partner with software developers to refine alert algorithms and minimize false positives. Companies conduct rigorous testing under extreme temperature and humidity conditions. Supply partners facilitate firmware updates and calibration procedures. Industry conferences feature prototypes with voice-activated controls for hands-free operation.
Shift toward Sustainable and Eco-Friendly Materials
Leading brands adopt recycled polymers and biodegradable components to meet environmental targets. Japan Safety Eyewear Market stakeholders introduce frames made from post-consumer plastics and plant-based resins. It undergoes durability testing to ensure performance under workplace stress. R&D teams collaborate with material scientists to validate component life cycles and recyclability. Buyers review environmental impact reports to guide procurement decisions. Certification bodies recognize eco-friendly products with green labeling. Sustainable practices foster brand loyalty among corporations with corporate social responsibility goals.
- For instance, Japan has pledged to reduce its emissions significantly by 2030, emphasizing the importance of sustainable consumption.
Growth of Customization and Ergonomic Design Offerings
Manufacturers offer modular frame systems that adapt to various facial contours and head sizes. Japan Safety Eyewear Market leaders integrate adjustable nose pads and flexible hinges for extended comfort. It encourages wearers to comply with safety protocols throughout long shifts. Companies invest in 3D-scanning tools to create bespoke fit programs for workforces. Distribution centers provide on-site fitting services to major industrial clients. Design teams focus on reducing weight without compromising impact resistance. Customized solutions drive higher adoption rates in specialized industries such as electronics and pharmaceuticals.
Market Challenges Analysis
High Compliance Costs and Regulatory Complexity
Frequent updates to lens performance and frame durability standards drive up production costs for protective eyewear. The Japan Safety Eyewear Market struggles to keep pace with changes from national and industry regulators. Manufacturers must allocate resources to repeated testing and certification audits. It forces small suppliers to scale back product lines or exit niche segments. Companies face pressure to invest in advanced testing facilities and skilled personnel. Buyers often delay procurement until fresh certifications arrive, creating order volatility. Suppliers negotiate long-term contracts to stabilize cash flow.
- For instance, Japan's safety eyewear market is heavily influenced by stringent regulatory frameworks, requiring manufacturers to comply with evolving safety standards and frequent audits.
Price Competition and Market Fragmentation
Low-cost imports from neighboring countries undercut domestic producers on price and delivery speed. The Japan Safety Eyewear Market faces margin compression from suppliers offering basic protective glasses at minimal cost. It compels local brands to improve value propositions through technology or service bundles. Retailers demand volume discounts that erode profit margins further. Fragmented distribution channels create inconsistent product availability across regions. Companies struggle to build direct relationships with end users in remote industrial parks. Sustained investment in brand-building and after-sales support proves essential to withstand price pressures.
Market Opportunities
Seamless Integration with Industry 4.0 and Robotics Workflows
The Japan Safety Eyewear Market can leverage the rapid adoption of automation and robotic assembly lines to introduce sensor-enabled eyewear that communicates with factory control systems. It empowers operators to receive hazard alerts directly in their field of view, which shortens response times. Manufacturers can partner with automation providers to certify eyewear for specific robotic environments. It opens channels for bundled safety solutions that combine PPE and system diagnostics. Companies can develop software APIs that integrate eyewear data into centralized safety dashboards. It creates a recurring revenue model through firmware updates and analytics services. Industry conferences provide platforms to showcase collaborative prototypes to prospective clients.
Expansion into Healthcare and Emerging Specialized Sectors
Rising demand for precision in pharmaceuticals, diagnostics, and research labs presents a significant opportunity for advanced protective eyewear. The Japan Safety Eyewear Market gains traction by offering lens coatings that resist chemical splashes and sterilization cycles. It supports compliance with stringent hygiene protocols through antimicrobial frame materials. Providers can tailor products for medical device manufacturers, biotech firms, and academic institutions. It diversifies revenue streams and builds cross-industry partnerships. Companies deploy bespoke fit programs for laboratory technicians to enhance comfort during extended procedures. It elevates brand credibility in highly regulated environments and drives long-term contract agreements.
Market Segmentation Analysis:
By Product:
The Japan Safety Eyewear Market is segmented by product type, application, and distribution channel, offering a detailed view of consumer and industry preferences. Within product types, prescription safety eyewear dominates in industrial environments, with the USD 20 to USD 40 and USD 40 to USD 70 segments seeing the highest demand. These ranges offer a balance between durability and affordability, appealing to manufacturing and construction workers. Non-prescription eyewear sees strong traction in the USD 25 to USD 50 and USD 50 to USD 100 categories, reflecting demand from users seeking quality protective features without vision correction.
By Application:
By application, industrial manufacturing leads the market due to Japan's advanced and safety-conscious production facilities. Construction and oil & gas sectors also contribute notably, driven by strict workplace safety compliance. Military and public sectors maintain steady demand, supported by procurement policies focused on employee safety. The “others” segment includes healthcare and laboratories, which continue to adopt safety eyewear to meet hygiene and protection standards.
By Distribution Channel:
Distribution in the Japan Safety Eyewear Market is largely driven by business-to-business (B2B) channels, especially for large-scale procurement by industrial clients. Direct-to-consumer (D2C) sales are growing, supported by digital platforms and retail expansion. Other channels include partnerships with occupational safety providers and institutional buyers.
Segments:
Based on Product:
- Prescription
- Up to USD 10
- USD 10 to USD 20
- USD 20 to USD 40
- USD 40 to USD 70
- Above USD 70
- Non-Prescription
- Up to USD 25
- USD 25 to USD 50
- USD 50 to USD 100
- USD 100 to USD 150
- Above USD 150
Based on Application:
- Oil & Gas
- Construction
- Industrial Manufacturing
- Military & Public Sectors
- Others
Based on Distribution Channel:
- Business to Business (B2B)
- Direct to Consumers (D2C)
- Others
Based on the Geography:
- Kanto Region
- Kansai Region
- Chubu Region
- Kyushu Region
- Other Regions
Regional Analysis
Kanto and Kansai The Japan Safety Eyewear Market in the Kanto region generates roughly 30% of total industry revenue. The region hosts major electronics, automotive, and precision manufacturing hubs that demand high-performance protective eyewear. Factories in Tokyo, Yokohama, and surrounding areas drive orders for anti-fog and impact-resistant lenses. Corporate procurement teams leverage direct contracts with leading suppliers to meet rigorous safety standards. It attracts investments in local distribution centers to reduce lead times. The Kansai region follows with about 20% market share. Osaka and Kobe project steady growth driven by infrastructure upgrades and factory expansions.
Chubu and Kyushu Market The Japan Safety Eyewear Market achieves nearly 18% share in the Chubu region. Nagoya and surrounding prefectures maintain strong demand from automotive assembly and aerospace component manufacturers. Production facilities require specialized frames that withstand high-temperature processes and chemical exposure. Direct partnerships between suppliers and plant safety managers ensure consistent product quality. It supports annual safety audits and equipment upgrades at large-scale production sites. The Kyushu region captures 12% of national sales led by shipbuilding yards and semiconductor fabs. Fukuoka and Kitakyushu report increased orders for ergonomic designs that enhance user compliance.
Other Regions The Japan Safety Eyewear Market records the remaining 20% share across other regions such as Tohoku, Hokkaido, and Shikoku. Rural construction and mining projects in Tohoku drive demand for durable frames and wide-field lenses. Hokkaido’s cold-climate operations require anti-fog treatments that withstand rapid temperature changes. It prompts distributors to stock region-specific product lines. Shikoku chemicals and agriculture sectors add stable orders for splash-resistant eyewear. B2C channels grow through e-commerce platforms that serve remote locations. Local safety retailers combine in-store consultations with virtual fittings to boost adoption.
Key Player Analysis
- MCR Safety
- Honeywell International, Inc.
- 3M
- Scott Safety (Tyco)
- DEWALT
- Radians
Competitive Analysis
The Japan Safety Eyewear Market is competitive, with leading players such as Honeywell International Inc., 3M, MCR Safety, Uvex Group, and Yamamoto Kogaku Co., Ltd. These companies maintain strong market positions through high-quality products, compliance with Japanese Industrial Standards (JIS), and long-standing relationships with industrial clients. They offer a wide range of safety eyewear tailored for various applications, including manufacturing, construction, and public sector use. Companies compete by offering safety eyewear that aligns with Japanese Industrial Standards (JIS) and meets the specific needs of sectors such as manufacturing, construction, and public safety. Product quality, durability, and wearer comfort remain top priorities in purchasing decisions, particularly for industries requiring prolonged use of protective gear. Competition focuses on technological advancements, with emphasis on features like anti-fog coatings, impact resistance, UV protection, and lightweight materials. Many manufacturers invest in continuous product development to meet changing safety regulations and workplace requirements. Customization options and ergonomic designs also play a key role in market differentiation. Strong distribution networks, both through industrial procurement and retail, enhance visibility and market penetration. Business-to-business (B2B) supply chains remain dominant, though direct-to-consumer (D2C) channels are gaining traction through online platforms and specialty stores. Companies that offer consistent quality, fast delivery, and responsive customer service gain an advantage. With Japan’s emphasis on workplace safety and regulatory compliance, the competitive landscape remains active, pushing participants to innovate and respond to evolving industry demands.
Recent Developments
- In April 2024, Popticals, a premium eyewear brand, launched the POPZULU Ops Edition, a line of ballistic glasses and safety eyewear. POPZULU is designed for tactical and industrial environments, offering full-scale defense with lenses engineered to shield and a frame that can collapse into a pocket-sized hard-shell case. The POPZULU sunglasses feature an innovative frame design and patented FL2 Micro-Rail System technology for collapsibility. They are crafted using high-quality materials like Hydrophobic Ri-Pel coating, Grilamid TR90 for lightweight and durability, and Impacto lenses from Carl Zeiss Vision that are 5X more resistant to hits and stresses than polycarbonate.
- In April 2024, Innovative Eyewear, Inc. announced filing two new U.S. patent applications related to its new Lucyd Armor smart safety glasses product, which is planned for introduction in mid-2024. The utility patent application covers the product's functional aspects, while the design patent application covers its ornamental design.
- In March 2024, Protective Industrial Products (PIP), a leader in personal protective equipment, acquired Scope Optics Pty Ltd., a safety eyewear company based in Australia. By incorporating Scope Optics' safety eyewear into its existing portfolio of eye protection brands, PIP is adding a wider selection of premium designs, advanced lens technologies, and exceptional value to serve its customers better. The acquisition of Scope Optics is another example of PIP's proven acquisition strategy to strengthen its portfolio of head-to-toe PPE solutions.
Market Concentration & Characteristics
The Japan Safety Eyewear Market exhibits moderate concentration, with a handful of global leaders and domestic specialists controlling a majority of premium and value segments. It features distinct tiers ranging from basic non-prescription glasses to advanced prescription models equipped with smart sensors and AR overlays. A small group of vendors leverages expansive distribution networks in key regions to secure long-term contracts with automotive, electronics, and construction firms. It balances innovation in lens coatings and frame ergonomics against cost pressures from low-priced imports. Niche players address specialized requirements in healthcare and robotics workflows. It maintains high entry barriers through stringent certification processes and established supplier relationships. Diverse channel strategies-direct corporate sales, B2C e-commerce portals, and specialty distributors-ensure broad market coverage while reinforcing competitive stability.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan Safety Eyewear Market will integrate AI-driven hazard detection features into protective eyewear to enhance worker safety.
- Manufacturers will deploy e-commerce platforms offering personalized frame fittings and rapid delivery.
- Companies will adopt sustainable materials in lenses and frames to meet eco-friendly standards.
- Suppliers will enable wireless connectivity for real-time monitoring of lens performance and usage.
- Augmented reality overlays will assist technicians with step-by-step instructions during high-risk tasks.
- Partnerships with automation providers will customize eyewear for seamless integration into robotic workflows.
- Virtual fitting tools will decrease return rates and improve procurement efficiency for corporate buyers.
- Subscription models will cover firmware upgrades and lens maintenance services on an ongoing basis.
- Regional distributors will expand into remote industrial zones with tailored product assortments.
- Enhanced certification requirements will drive continuous improvements in impact resistance and scratch protection.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Regulatory Compliance
Japan’s Industrial Safety and Health Act enforces rigorous workplace safety standards, compelling companies to adopt certified safety eyewear and driving consistent demand across manufacturing, construction, and public sectors.
Industrial Expansion and Modernization
Growth in automotive, electronics, and heavy manufacturing sectors increases the need for advanced protective eyewear, especially as new facilities and automation technologies are introduced.
Technological Advancements in Eyewear
Integration of smart features such as heads-up displays, sensor-based hazard alerts, and augmented reality overlays enhances real-time safety monitoring and risk management, making advanced eyewear more attractive to employers.
Digitalization and E-Commerce Growth
The expansion of online procurement platforms and B2B e-commerce streamlines purchasing for SMEs and large enterprises, improving accessibility and accelerating market penetration, especially in remote and regional industrial clusters.
Sustainability and Ergonomic Design
Rising corporate and governmental focus on sustainability drives adoption of eco-friendly materials and reusable designs, while ergonomic innovations address the needs of an aging workforce and improve compliance with safety protocols.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Safety Eyewear market?
What factors are driving the growth of the Japan Safety Eyewear market?
What are some challenges faced by the Japan Safety Eyewear market?
Who are the major players in the Japan Safety Eyewear market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Prescription (Up to USD 10)
- 1.2.2 Prescription (USD 10 to USD 20)
- 1.2.3 Prescription (USD 20 to USD 40)
- 1.2.4 Prescription (USD 40 to USD 70)
- 1.2.5 Prescription (Above USD 70)
- 1.2.6 Non-Prescription (Up to USD 25)
- 1.2.7 Non-Prescription (USD 25 to USD 50)
- 1.2.8 Non-Prescription (USD 50 to USD 100)
- 1.2.9 Non-Prescription (USD 100 to USD 150)
- 1.2.10 Non-Prescription (Above USD 150)
- 1.3 By Application
- 1.3.1 Industrial Manufacturing
- 1.3.2 Construction
- 1.3.3 Oil & Gas
- 1.3.4 Military & Public Sectors
- 1.3.5 Others (Healthcare, Laboratories)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 199.38 million → 2032: USD 334.66 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Safety Eyewear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Safety Eyewear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Safety Eyewear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Safety Eyewear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Safety Eyewear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Safety Eyewear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Safety Eyewear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Safety Eyewear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 199.38 million → 2032: USD 334.66 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Safety Eyewear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Prescription (Up to USD 10)
- 12.3.7.2 Prescription (USD 10 to USD 20)
- 12.3.7.3 Prescription (USD 20 to USD 40)
- 12.3.7.4 Prescription (USD 40 to USD 70)
- 12.3.7.5 Prescription (Above USD 70)
- 12.3.7.6 Non-Prescription (Up to USD 25)
- 12.3.7.7 Non-Prescription (USD 25 to USD 50)
- 12.3.7.8 Non-Prescription (USD 50 to USD 100)
- 12.3.7.9 Non-Prescription (USD 100 to USD 150)
- 12.3.7.10 Non-Prescription (Above USD 150)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial Manufacturing
- 12.4.7.2 Construction
- 12.4.7.3 Oil & Gas
- 12.4.7.4 Military & Public Sectors
- 12.4.7.5 Others (Healthcare, Laboratories)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Safety Eyewear End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Japan Safety Eyewear Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Japan Safety Eyewear Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Japan Safety Eyewear Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 3M
- 18.4 MCR Safety
- 18.5 Scott Safety (Tyco)
- 18.6 DEWALT
- 18.7 Radians
- 18.8 Uvex Group
- 18.9 Yamamoto Kogaku Co., Ltd.
- 18.10 Popticals
- 18.11 Protective Industrial Products (PIP)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

