
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Japan Premium Bottled Water MarketSize 2023 | USD 4,238.18 Million |
| Japan Premium Bottled Water Market, CAGR | 4.50% |
| Japan Premium Bottled Water Market Size 2032 | USD 6,298.34 Million |
Market Overview
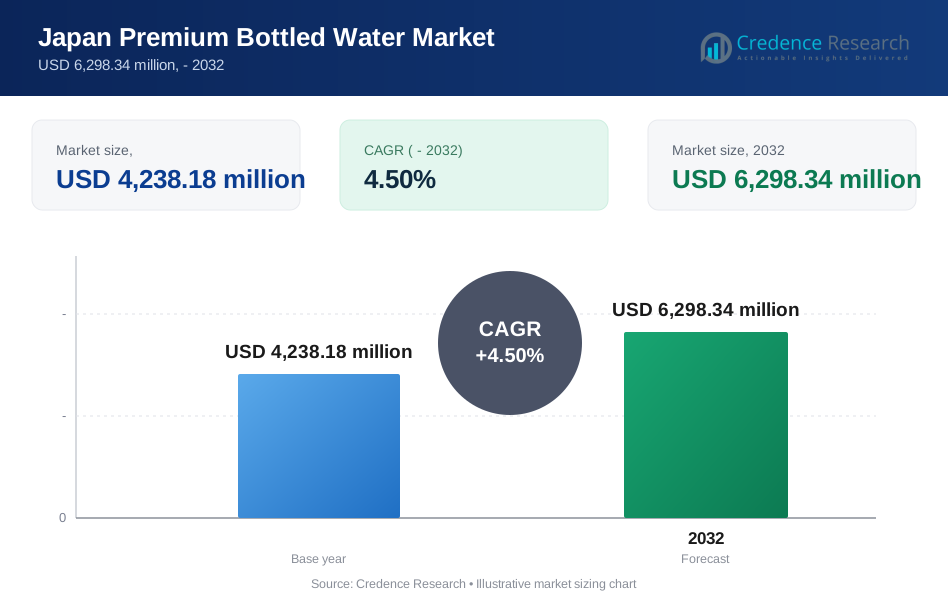
The Japan Premium Bottled Water Market is projected to grow from USD 4,238.18 million in 2023 to USD 6,298.34 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.50%.
The Japan Premium Bottled Water Market is propelled by growing health consciousness among consumers and a rising preference for premium, mineral-enriched water varieties. Trends such as the increasing demand for sustainably sourced and packaged products are also significant, as eco-friendly practices become a priority for both producers and consumers. Additionally, the market benefits from innovative packaging designs that enhance convenience and appeal, coupled with strategic marketing campaigns that emphasize the health and lifestyle benefits associated with premium bottled water. These drivers are shaping a dynamic market landscape, with evolving consumer preferences steering the demand upward.
The Japan Premium Bottled Water Market is geographically dispersed, with major urban centers like Tokyo, Osaka, and Yokohama driving significant consumption due to higher income levels and greater health consciousness among residents. Key players influencing the market include global giants such as The Coca-Cola Company and Evian, alongside prominent local firms like Suntory Holdings Limited and Asahi Group Holdings, Ltd. These companies are pivotal in shaping market dynamics through innovative product offerings and extensive distribution networks. Their strategic presence is bolstered by Japan's robust retail infrastructure, facilitating widespread access to premium bottled water across the nation.
Market Drivers
Growing Health Consciousness Drives Premium Bottled Water Demand
In Japan, the demand for premium bottled water is significantly influenced by growing health consciousness among consumers. For instance, there has been a noticeable shift in consumer preferences towards healthier beverage options, including bottled water. Despite the general safety of tap water, many opt for bottled water due to perceived health and safety benefits. This preference is bolstered by an increasing awareness of the nutritional value of mineral water, which offers essential hydration, electrolyte balance, and potential digestive benefits. Such health considerations are becoming paramount in consumer choices, steering them towards premium bottled water options that promise added health advantages.
Sustainability and Natural Purity Influence Consumer Choices
Environmental awareness is another critical driver in the Japan Premium Bottled Water Market. For instance, recognizing the environmental impact of plastic, premium brands are adopting sustainable packaging solutions, from recycled materials to biodegradable alternatives. Modern consumers are increasingly attracted to brands that adopt sustainable packaging and water sourcing practices, reflecting their commitment to environmental conservation. Additionally, there is a strong preference for products perceived as natural and devoid of artificial additives, which resonates with the broader consumer inclination towards health and eco-friendliness. These environmental and health considerations are reshaping purchasing behaviors, encouraging companies to innovate in both product and process.
Convenience and Lifestyle Preferences Shape Market Dynamics
The fast-paced lifestyles led by many Japanese consumers and the popularity of outdoor activities have heightened the demand for convenient and portable beverage solutions. Premium bottled water fits well into this dynamic, providing a practical hydration solution on the go. Furthermore, there is a growing trend of premiumization within the market, where consumers show a willingness to invest in high-quality, branded products that not only meet their practical needs but also align with their lifestyle aspirations. This trend is a testament to the evolving consumer preferences that prioritize both quality and convenience.
Cultural and Economic Factors Further Propel Market Growth
Cultural influences also play a significant role in the market dynamics. Bottled water is commonly selected as a gift during special occasions or as corporate gifts, embedded within Japan’s gift-giving tradition. Moreover, premium bottled water is increasingly viewed as a status symbol among certain consumer segments, highlighting discerning taste and an upscale lifestyle. Economic growth has led to rising disposable incomes, allowing consumers to spend more on luxury and health-oriented products. This economic upturn, combined with a heightened focus on health and wellness, is boosting expenditures on premium beverages, solidifying the market’s expansion trajectory.
Market Trends
Emphasis on Natural Ingredients and Advanced Packaging Innovations
Consumers in the Japan Premium Bottled Water Market are increasingly drawn to products that offer clear health benefits, which is evident in the rising demand for bottled water with a high mineral content and natural properties. For instance, the demand for bottled water with a high mineral content and natural properties is on the rise. These waters, often sourced from geologically unique regions, are marketed for their purity and the health advantages they provide, such as improved hydration and electrolyte balance. Additionally, there is a strong movement toward sustainable packaging within the market. Brands are adopting eco-friendly materials that are either recyclable or biodegradable, reflecting a commitment to environmental stewardship. This trend is coupled with investments in sleek, modern designs that cater to aesthetically minded consumers, making water not just a beverage but a part of a lifestyle choice.
Strategic Premiumization and Digital Expansion Shape Market Frontiers
The market is witnessing a significant trend toward premiumization, with luxury brands introducing high-end bottled water products that cater to affluent consumers. These premium offerings are complemented by niche products tailored to specific consumer preferences, such as alkaline, flavored, or naturally infused waters. This strategy not only diversifies the market but also enhances the appeal of bottled water as a versatile and health-oriented option. Concurrently, digital marketing and e-commerce are becoming vital components of the industry’s strategy. Brands are increasingly leveraging online platforms to enhance their visibility and engage with a broader audience. The growth in e-commerce platforms has particularly revolutionized access to premium bottled water, making it easier for consumers to explore and purchase a wide range of products from the comfort of their homes. Additionally, the market is also experiencing a push towards international expansion. Both global and Japanese bottled water brands are aggressively exploring opportunities abroad, promoting their premium products in new markets and taking advantage of Japan’s reputation for quality and innovation in bottled water production.
Market Challenges Analysis
Navigating Competition and Environmental Impact Concerns
In the Japan Premium Bottled Water Market, competition from tap water poses significant challenges. Japanese tap water is recognized for its safety and high quality, reducing the perceived necessity for bottled water among consumers. For instance, in Japan, over 98 percent of the population has access to drinkable tap water. The average daily water consumption per capita stands at around 262 liters, which indicates a high reliance on tap water for daily consumption. This poses a significant challenge for the premium bottled water market as consumers may find it hard to justify the higher cost of bottled water for daily use. Moreover, the environmental impact of bottled water consumption is substantial. The production of plastic bottles in Japan has jumped to a staggering 23.2 billion per year. Despite the country’s advanced recycling technology, approximately 2.6 billion bottles are incinerated, sent to landfills, or lost to waterways and oceans annually. Additionally, the transportation of bottled water, from production to retail, extends its carbon footprint, conflicting with growing consumer demand for environmentally friendly products. These factors create a pressing need for bottled water companies to adopt more sustainable practices and mitigate their environmental impact to maintain consumer trust and market relevance.
Economic Sensitivities and Regulatory Hurdles Impact Market Dynamics
Economic fluctuations significantly influence consumer behavior in the premium bottled water sector. During economic downturns, discretionary spending on premium products, including bottled water, often decreases as consumers become more price-sensitive. This sensitivity affects demand dynamics, posing a challenge for brands that command higher prices based on quality or branding. Additionally, the market faces regulatory challenges that can impact operations and marketing. Ensuring compliance with Japan’s stringent food safety standards requires meticulous management and can impose significant costs. Similarly, restrictions on labeling and advertising limit how brands can communicate benefits and differentiate their products, which is crucial in a saturated market. The challenge of standing out is exacerbated by the difficulty in building and maintaining consumer loyalty. With numerous options available, consumers may switch brands based on price, convenience, or perceived quality, making it difficult for companies to sustain a loyal customer base. These factors necessitate strategic adaptations, focusing on value demonstration and engagement to secure a competitive edge in a challenging economic and regulatory landscape.
Market Segmentation Analysis:
By Product:
The Japan Premium Bottled Water Market is segmented by product into spring water, sparkling water, mineral water, and others. Spring water, sourced directly from natural springs, is favored for its purity and natural filtration qualities, making it a popular choice among health-conscious consumers. Sparkling water, infused with carbon dioxide to create effervescence, caters to those seeking a refreshing alternative to sugary soft drinks. Mineral water, rich in natural minerals and often touted for its health benefits, attracts a niche market that prioritizes wellness and natural products. The 'others' category encompasses various innovative water products that may include flavored or fortified options, catering to diverse consumer preferences. This segmentation highlights the variety and depth of products available, each meeting specific consumer needs and lifestyle choices, thereby driving differentiated market growth strategies.
By Distribution Channel:
In terms of distribution channels, the Japan Premium Bottled Water Market includes supermarkets & hypermarkets, specialty stores, online platforms, and others. Supermarkets and hypermarkets dominate due to their widespread availability and convenience, offering a broad range of premium bottled water brands under one roof. Specialty stores provide curated selections, often focusing on higher-end products or unique water varieties, which appeal to discerning customers. Online sales channels are rapidly growing, driven by the convenience of home delivery and the increasing penetration of e-commerce in consumer shopping habits. The 'others' segment includes various alternative retail outlets such as convenience stores and vending machines, which complement the main channels by catering to on-the-go consumption and impulse buying behaviors. This diversified distribution network ensures comprehensive market coverage and accessibility to different consumer segments, supporting the overall growth of the premium bottled water industry in Japan.
Segments:
Based on Product:
- Spring Water
- Sparkling Water
- Mineral Water
- Others
Based on Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Stores
- Online
- Others
Based on the Geography:
- Kanto region
- Chubu region
- Kansai region
- Kyushu region
- Tohoku
- Chugoku
- Shikoku
Regional Analysis
Kanto region
The Kanto region, encompassing Tokyo and its surrounding prefectures, commands a dominant 45% market share in Japan's premium bottled water market. This region's leadership position is largely attributed to its high concentration of affluent consumers, international businesses, and luxury hotels. Tokyo, as the nation's economic and cultural hub, drives significant demand for premium bottled water across various sectors, including high-end restaurants, corporate offices, and upscale retail outlets. The region's health-conscious urban population, coupled with a strong preference for quality and brand prestige, fuels the consumption of premium bottled water brands. Additionally, the Kanto region's frequent hosting of international events and conferences contributes to the steady demand for premium bottled water in the hospitality industry. The region's retailers and e-commerce platforms also play a crucial role in making a wide variety of domestic and imported premium water brands accessible to consumers, further solidifying its market dominance.
Kansai region
The Kansai region, centered around major cities like Osaka, Kyoto, and Kobe, holds a substantial 28% share of Japan's premium bottled water market. This region's significant market presence is rooted in its rich cultural heritage, thriving tourism industry, and discerning consumer base. Kansai's famous natural water sources, particularly those in the mountainous areas of Kyoto and Hyogo prefectures, contribute to the production of several highly regarded local premium water brands. The region's renowned hospitality sector, including traditional ryokans and high-end hotels, drives consistent demand for premium bottled water. Osaka's vibrant food culture and upscale dining scene also contribute significantly to the market, with restaurants and bars offering a curated selection of premium waters to complement their culinary offerings.
Key Player Analysis
- The Coca-Cola Company
- FamilyMart Co., Ltd.
- Aqua Clara
- DrSilica Sdn Bhd
- Suntory Holdings Limited
- Asahi Group Holdings, Ltd.
- Evian
- Otsuka Foods
- FIJI Water
- Fillico
Competitive Analysis
The Japan Premium Bottled Water market is fiercely competitive, featuring prominent companies such as The Coca-Cola Company, Suntory Holdings Limited, Asahi Group Holdings, Ltd., and Evian. These players are distinguished by their robust product innovations and aggressive marketing strategies. Each company leverages its unique strengths ranging from extensive global supply chains to deep local market understanding to cater to Japan’s discerning consumers. Innovations in packaging, alongside commitments to sustainability, help these companies appeal to environmentally conscious consumers. Furthermore, strategic partnerships and advertising campaigns targeted at health-aware demographics allow them to expand their market presence. Overall, the competitive landscape is marked by efforts to balance product quality with sustainability and consumer engagement, driving each brand to enhance its offerings continuously.
Recent Developments
- In August 2024, Suntory Holdings announced its financial results for the first half of the year.
- In August 2023, Otsuka Foods announced a price revision for its CRYSTAL GEYSER ALPINE SPRING WATER 700ml PET bottle product, effective from October 1, 2023. This decision was made due to rising costs of packaging materials, raw materials, and logistics.
- In August 2023, Coca-Cola Bottlers Japan Holdings Inc. launched a new corporate message: “We bottle happy moments.”
Market Concentration & Characteristics
The Japan Premium Bottled Water Market exhibits a moderate to high level of market concentration, with a few major players holding significant shares. These leading companies have cemented their market positions through extensive branding, high-quality product offerings, and robust distribution networks that ensure widespread availability. The market is characterized by a strong focus on product differentiation, as brands compete on aspects such as mineral content, packaging innovation, and added health benefits. Premium bottled water brands in Japan are increasingly leveraging advanced filtration and bottling technologies to enhance product purity and appeal. Additionally, the market's characteristics are shaped by a growing consumer preference for products that combine luxury with health and sustainability, prompting companies to innovate continuously to meet these evolving demands. This competitive environment drives a dynamic market landscape where companies must adapt quickly to consumer trends and regulatory changes to maintain and grow their market presence.
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increase in health-conscious consumers driving demand for mineral-rich and naturally sourced waters.
- Expansion of product lines to include eco-friendly and biodegradable packaging options.
- Growth in partnerships between water brands and luxury lifestyle products to enhance brand image.
- Enhanced focus on marketing campaigns that emphasize the health benefits and premium nature of products.
- Adoption of advanced filtration and purification technologies to ensure superior water quality.
- Strategic expansions into untapped regional markets within Japan to increase market penetration.
- Introduction of functional waters with added health benefits such as vitamins and antioxidants.
- Increased investment in digital marketing and e-commerce platforms to reach a broader audience.
- Stronger emphasis on sustainability and reduction of carbon footprint in production and distribution processes.
- Development of niche products tailored to specific consumer segments, such as flavored or sparkling mineral waters.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Health Consciousness
Japanese consumers are increasingly prioritizing health and wellness, leading to a preference for premium bottled water perceived as safer and more beneficial than tap water, especially mineral-rich and naturally sourced varieties.
Sustainability and Eco-Friendly Packaging
Rising environmental awareness is pushing brands to adopt sustainable packaging and responsible sourcing, which resonates with consumers seeking products that align with their values on environmental conservation.
Premiumization and Lifestyle Aspirations
Consumers are willing to pay more for high-quality, branded bottled water that reflects their lifestyle and status, with premium bottled water often chosen for gifting and as a symbol of sophistication.
Convenience and Urban Lifestyles
Busy urban populations and the popularity of outdoor activities drive demand for portable, convenient hydration solutions, making premium bottled water a preferred choice for on-the-go consumption.
Innovative Product Offerings and Marketing
Brands are differentiating through advanced packaging, functional water variants, and targeted marketing campaigns that emphasize health, purity, and luxury, further stimulating market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Premium Bottled Water Market?
What factors are driving the growth of the Japan Premium Bottled Water Market?
What are the key segments within the Japan Premium Bottled Water Market?
What are some challenges faced by the Japan Premium Bottled Water Market?
Who are the major players in the Japan Premium Bottled Water Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Spring Water
- 1.2.2 Sparkling Water
- 1.2.3 Mineral Water
- 1.2.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 4,238.18 million → 2032: USD 6,298.34 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Premium Bottled Water Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Premium Bottled Water Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Premium Bottled Water Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Premium Bottled Water Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Premium Bottled Water Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Premium Bottled Water Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Premium Bottled Water Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Premium Bottled Water Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 4,238.18 million → 2032: USD 6,298.34 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Premium Bottled Water Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Spring Water
- 12.3.7.2 Sparkling Water
- 12.3.7.3 Mineral Water
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Premium Bottled Water Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Premium Bottled Water Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Premium Bottled Water Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 The Coca-Cola Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Suntory Holdings Limited
- 17.4 Asahi Group Holdings, Ltd.
- 17.5 Evian
- 17.6 Otsuka Foods
- 17.7 FIJI Water
- 17.8 FamilyMart Co., Ltd.
- 17.9 Aqua Clara
- 17.10 DrSilica Sdn Bhd
- 17.11 Fillico
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

