
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Internet Data Center (IDC) Market Size 2024 | USD 2,986.77 million |
| Japan Internet Data Center (IDC) Market, CAGR | 12.43% |
| Japan Internet Data Center (IDC) Market Size 2032 | USD 7,626.57 million |
Market Overview
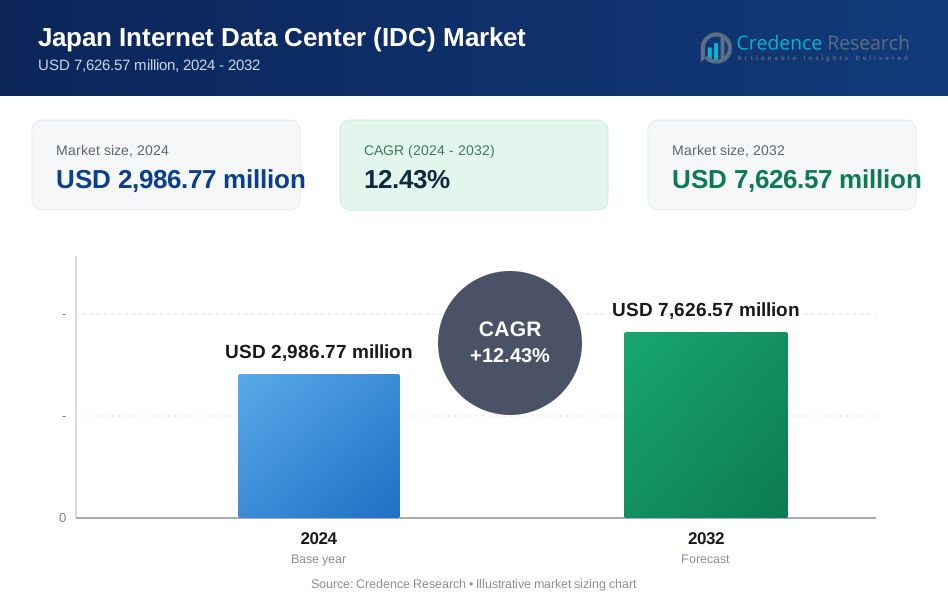
The Japan Internet Data Center (IDC) market size was valued at USD 2,986.77 million in 2024 and is anticipated to reach USD 7,626.57 million by 2032, at a CAGR of 12.43% during the forecast period (2024-2032).
Strong enterprise digital transformation and surging cloud adoption drive demand for scalable, low-latency data center infrastructure in Japan. Strict data sovereignty and cybersecurity regulations compel organizations to invest in local facilities, while global hyperscaler expansions in Tokyo and Osaka meet growing storage and compute needs. Rapid 5G network roll-out and proliferation of IoT and edge computing use cases push operators to deploy decentralized micro data centers closer to end users. Enterprises embrace hybrid and multi-cloud strategies to balance performance, cost efficiency and compliance, boosting growth of colocation and managed services. The rising adoption of AI and big data analytics workloads fuels demand for high-density racks and advanced cooling solutions. Sustainability emerges as a critical trend, with leading operators integrating renewable energy sources, green financing mechanisms, prefabricated modular builds and energy-efficient cooling solutions to reduce carbon footprints. These converging forces underpin robust growth in the Japan IDC market.
The Japan Internet Data Center (IDC) market displays a geographic hierarchy anchored by Kanto, where Tokyo and Yokohama account for the highest concentration of hyperscale and enterprise facilities, supported by dense fiber routes and reliable power infrastructure. The Kansai cluster around Osaka and Kyoto serves commercial and manufacturing workloads, while the Chubu corridor near Nagoya and the Kyushu region around Fukuoka address regional enterprise and edge computing requirements. Operators prioritize sites with stable power grids, low seismic risk and proximity to submarine cable landings to ensure disaster resilience and international connectivity. Emerging zones in Hokkaido and Tohoku benefit from streamlined permits and regional incentives that attract modular facility investments. Leading providers NTT Communications Corporation, KDDI Corporation, Internet Initiative Japan Inc., Fujitsu Limited and Equinix Japan drive capacity expansions through sustainable energy integration, advanced cooling solutions and managed service portfolios, reinforcing Japan’s strategic role in Asia-Pacific digital infrastructure.
Market Insights
- The Japan Internet Data Center (IDC) market size was valued at USD 2,986.77 million in 2024 projected to reach USD 7,626.57 million by 2032 at a CAGR of 12.43%.
- The global Internet Data Center (IDC) market was valued at USD 61,521.80 million in 2024 and is projected to reach USD 150,594.58 million by 2032, growing at a CAGR of 11.84% during the forecast period.
- Rapid enterprise cloud adoption within the Japan Internet Data Center (IDC) market increases demand for scalable, low-latency data center solutions and drives growth in colocation, hosting and managed services for hybrid IT deployments.
- Hyperscale cloud providers in the Japan Internet Data Center (IDC) market expand multi-megawatt facilities in Tokyo, Osaka and regional hubs to meet surging enterprise workloads and optimize modular design, cooling efficiency and high-density power delivery.
- Sustainability gains momentum within the Japan Internet Data Center (IDC) market as operators integrate renewable energy, implement liquid cooling and heat-reuse systems to reduce power usage effectiveness and comply with environmental regulations.
- Established leaders in the Japan Internet Data Center (IDC) market such as NTT Communications, KDDI, Fujitsu, Internet Initiative Japan and Equinix drive competition through service diversification, strategic partnerships and targeted geographic expansion.
- The Japan Internet Data Center (IDC) market faces high capital expenditure for land, power infrastructure and cooling technology, coupled with stringent regulatory compliance and complex permitting processes that limit new entrants and extend deployment timelines, increasing operational risk.
- The Japan Internet Data Center (IDC) market’s regional dynamics feature Kanto leading demand for hyperscale and enterprise data centers, followed by Kansai and Chubu hubs supporting commercial and manufacturing workloads, while Kyushu, Hokkaido and Tohoku emerge for edge deployments due to incentives and lower land costs.
Report Scope
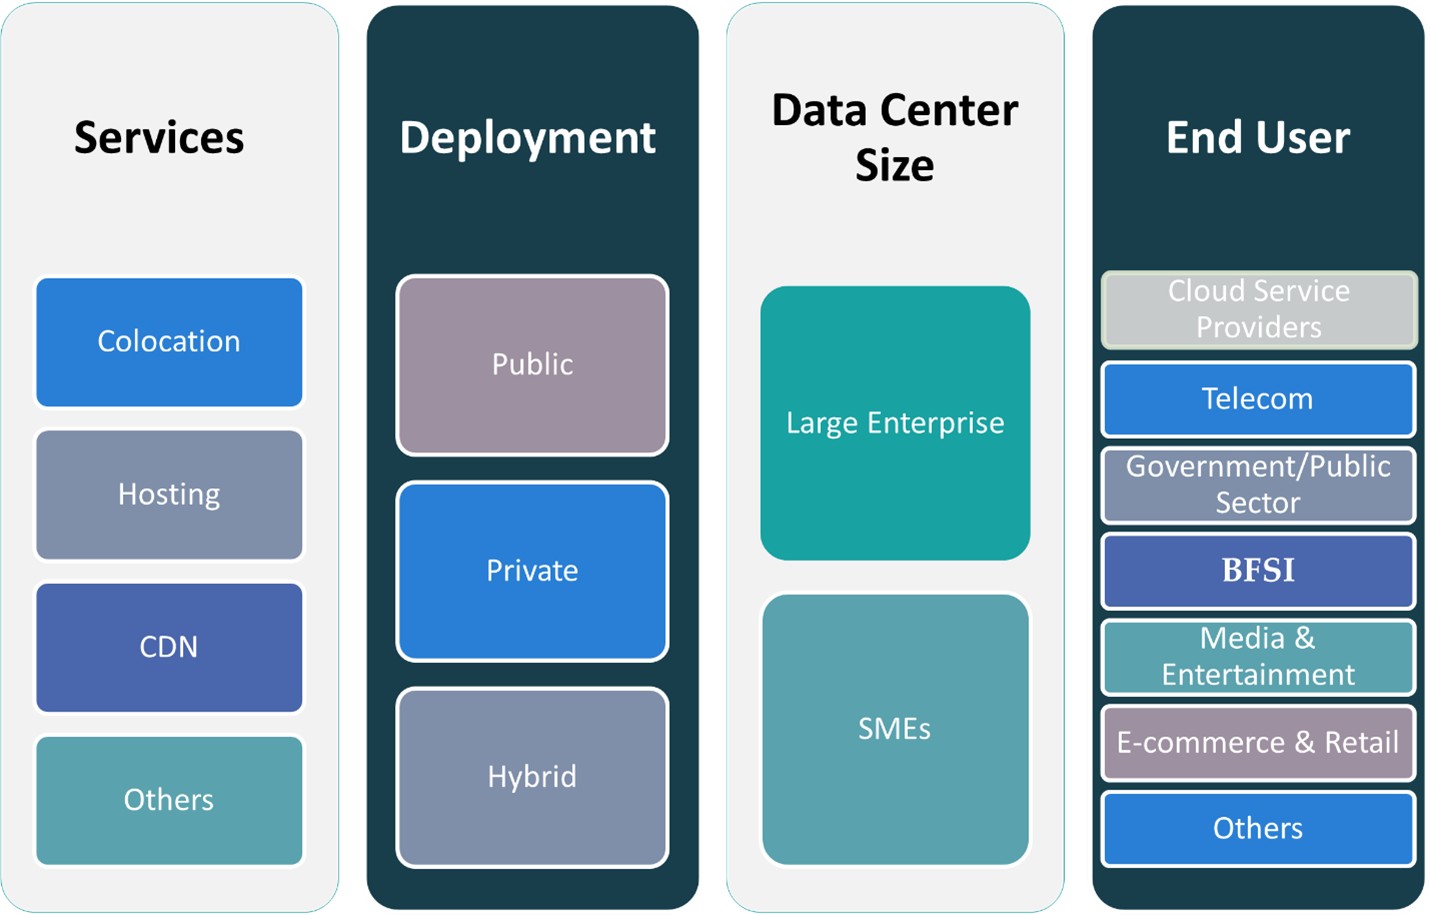
This report segments the Japan Internet Data Center (IDC) Market as follows:
Market Drivers
Surge in Enterprise Cloud Adoption
The Japan Internet Data Center (IDC) Market grows due to rapid enterprise cloud adoption. Organizations migrate workloads to scalable infrastructure that handles variable demand. It reduces capital expense and improves resource utilization across IT environments. Businesses use colocation services to supplement private data centers with flexible capacity. Leading hyperscale providers expand local facilities in Tokyo and Osaka to meet demand. This trend drives investments in network, power and security upgrades in data centers.
- For instance, Japan’s data center market is experiencing significant growth, driven by increasing demand for cloud services, big data analytics, and AI integration.
Strict Data Sovereignty and Security Regulations
The Japan Internet Data Center (IDC) Market responds to strict data sovereignty and security regulations. Companies must store sensitive data within national borders to comply with local laws. It raises demand for domestic data center capacity and specialized secure facilities. Operators deploy advanced threat detection and encryption tools to meet compliance standards. Regulators enforce guidelines that cover physical security, access control and audit processes. Firms invest in regular risk assessments and staff training to maintain compliance.
- For instance, Japan was a pioneer in data privacy legislation with its 2003 Act on the Protection of Personal Information (APPI), which has undergone revisions to strengthen data sovereignty.
Growth of 5G Networks and Edge Computing Infrastructure
The Japan Internet Data Center (IDC) Market benefits from growth of 5G networks and edge computing infrastructure. High-speed mobile connectivity enables real-time data processing at the network edge. It supports low-latency applications such as autonomous systems and AR/VR services. Providers establish micro data centers near urban hubs to reduce latency and congestion. Telecom operators partner with data center firms to deliver integrated edge solutions. This driver boosts demand for decentralized facilities and specialized equipment.
Focus on Sustainability and Energy Efficiency Practices
The Japan Internet Data Center (IDC) Market adopts sustainability and energy efficiency practices. Operators integrate renewable energy sources into power supply portfolios. It lowers carbon footprint and meets corporate environmental targets. Data centers use advanced cooling methods that cut energy consumption. Providers pursue green financing to fund eco friendly infrastructure upgrades. Stakeholders track performance metrics to optimize resource use and report progress.
Market Trends
Rapid Expansion of Hyperscale Facilities Across Urban Hubs
The Japan Internet Data Center (IDC) Market sees rapid expansion of hyperscale sites to serve growing enterprise demand. Leading cloud providers launch multi-megawatt facilities in Tokyo and Osaka to increase capacity. This move secures high-density rack power and boosts network performance near major hubs. Companies invest in robust electrical and cooling infrastructure to support compute-intensive tasks. Competition for land and power drives providers to innovate in facility design and operations. It fosters diverse service offerings, including managed private cloud and custom deployment bundles.
- For instance, Japan’s hyperscale market has surpassed 1GW, with planned expansions expected to more than double capacity.
Surge in Sustainable and Energy-Efficient Data Center Designs
The Japan Internet Data Center (IDC) Market prioritizes sustainable power and cooling solutions. Operators adopt renewable energy contracts and install onsite solar arrays to lower emissions. It upgrades chillers and airflow systems to reduce energy consumption. Facilities track efficiency metrics such as PUE to optimize resource usage. Regulators reward projects that meet strict environmental and energy guidelines. Providers use modular construction to speed eco-friendly facility deployment.
- For instance, Japan’s green data center market is expanding, with operators integrating renewable energy sources and advanced cooling technologies.
Edge Computing Growth Fueled by 5G Network Roll-Out
The Japan Internet Data Center (IDC) Market drives deployment of micro data centers at network edges. Telecom firms partner with data center operators to host compute nodes near 5G base stations. It enables low-latency support for applications like autonomous vehicles and AR platforms. Edge sites integrate virtualization and container orchestration for distributed workloads. Demand for edge services prompts build-to-suit projects in regional areas. Providers deliver localized processing and storage capacity to meet specific use cases.
Widespread Adoption of Hybrid and Multi-Cloud Architectures
The Japan Internet Data Center (IDC) Market shows broad shift toward hybrid and multi-cloud networks. Enterprises combine private data centers with public clouds to balance cost and performance. It leverages interconnection platforms for secure, high-bandwidth links between environments. Providers expand cross-connect and peering options to support diverse cloud configurations. Firms adopt unified management tools to orchestrate resources across sites. Growth in cloud-native services and API connectivity accelerates application deployment.
Market Challenges Analysis
High Infrastructure and Operational Cost Constraints
The Japan Internet Data Center (IDC) Market faces high infrastructure and operational cost constraints. Providers invest heavily in land, power and cooling equipment. They must secure reliable electricity supply to support dense compute racks. It drives capital outlay and extends project timelines. Energy tariffs remain elevated and introduce unpredictable expense fluctuations. Operators implement cost control measures and negotiate long-term utility contracts. Service pricing pressure reduces margin and discourages smaller entrants.
- For instance, Tokyo ranks as the most expensive city globally for data center construction, surpassing previous leaders due to rising land and energy costs.
Complex Regulatory Compliance and Land Scarcity Issues
The Japan Internet Data Center (IDC) Market must navigate complex regulatory compliance and land scarcity issues. Operators comply with stringent data sovereignty and environmental standards. It increases planning requirements and extends approval cycles. Urban land scarcity drives competition for suitable facility sites. Developers adapt to zonal restrictions and noise and emissions limits. They explore modular builds and retrofit projects to optimize space. Delayed permits and community objections slow new site launches.
Market Opportunities
Rising Demand for Cloud-Native and AI-Driven Services
Growth in data-intensive applications drives need for advanced hosting solutions. The Japan Internet Data Center (IDC) Market can leverage growth in AI and machine learning workloads. It enables providers to offer GPU-accelerated infrastructure that meets enterprise performance requirements. Edge computing requirements create demand for micro data center deployments near urban and industrial zones. Providers design modular facilities that scale capacity rapidly to match client needs. It draws global cloud vendors seeking local presence under tight data sovereignty rules. Strategic partnerships with AI platform firms strengthen service portfolios and revenue streams.
Emphasis on Sustainable Energy and Modular Facility Designs
Corporate renewable energy commitments open avenues for green power procurement. The Japan Internet Data Center (IDC) Market can capitalize on demand for low-carbon operations. It supports investment in onsite solar arrays and energy storage systems. Prefabricated modular builds allow swift deployment in limited urban spaces. Colocation providers integrate liquid cooling and heat reuse methods to boost efficiency. It encourages creation of specialized centers for high-performance computing and blockchain networks. Alliances with renewable energy firms and equipment vendors will expand market share.
Market Segmentation Analysis:
By Services:
The Japan Internet Data Center (IDC) market segments into colocation, hosting, CDN and others. Colocation leads thanks to enterprises seeking scalable rack space and managed power. It attracts clients looking to shift capex into predictable opex. Hosting services follow with dedicated and virtual server offerings that suit diverse workload needs. CDN uptake grows on rising demand for high-performance content delivery across mobile and web applications. Other services, such as disaster recovery and managed security, gain traction among firms prioritizing resilience.
By Deployment: Public deployment commands significant share through cost-effective, on-demand infrastructure. It appeals to organizations without legacy data centers and those driving digital initiatives rapidly. Private deployment retains strong relevance among highly regulated industries requiring full control over data and compliance. It supports sensitive workloads and proprietary applications. Hybrid models bridge both worlds by linking on-premises facilities with public clouds. It enables workload mobility and high availability for dynamic business requirements.
By Data Center Size: Large enterprise installations dominate capacity investments due to massive compute and storage demands. They benefit from custom facility design, advanced security and dedicated support teams. It suits corporations running AI, big data analytics and global services. SMEs drive growth in smaller racks and modular deployments that balance cost and performance. They choose pay-as-you-grow models to avoid overprovisioning. This segment offers opportunities for niche providers offering tailored packages and technical assistance.
Segments:
Based on Services:
- Colocation
- Hosting
- CDN
- Others
Based on Deployment:
- Public
- Private
- Hybrid
Based on Data Center Size:
- Large Enterprise
- SMEs
Based on End- User:
- Cloud Service Providers
- Telecom
- Government/Public Sector
- BFSI
- Media & Entertainment
- E-commerce & Retail
- Others
Based on the Geography:
- Kanto Region
- Kansai Region
- Chubu Region
- Kyushu Region
- Other Regions
Regional Analysis
Kansai Regions The Japan Internet Data Center (IDC) Market allocates the majority of capacity to the Kanto region, which holds approximately 55% market share. Tokyo and Yokohama serve as primary hubs for hyperscale and enterprise data centers. Companies value proximity to financial and technology firms based in the region. It offers robust power and network infrastructure that supports high-density builds. The Kansai region ranks second with roughly 18% share. Osaka and Kyoto data centers support manufacturing and e-commerce applications. Providers invest in new facilities to meet demand for low-latency services.
Chubu and Kyushu Regions The Japan Internet Data Center (IDC) Market devotes around 12% share to the Chubu region. Nagoya and surrounding prefectures host data centers that support automotive and logistics sectors. It benefits from stable power supply and a central position on major fiber routes. The Kyushu region captures near 8% share, driven by Fujitsu and local operators. Providers deploy modular facility designs to expand capacity with tight cost control. It attracts clients seeking disaster resilience near geothermal power sources. Regional incentives and lower land costs further boost construction activity.
Other Regions The Japan Internet Data Center (IDC) Market allocates the remaining 7% share to other regions in Tohoku, Shikoku and Hokkaido. Cities like Sapporo and Sendai serve emerging colocation and edge sites. It provides options for redundancy and geographic diversity. Smaller markets exhibit steady growth with specialized services for local industries. Providers partner with regional governments to secure sites and reduce approval times. It opens new avenues for content delivery and disaster recovery solutions.
Key Player Analysis
- NTT Communications Corporation
- Internet Initiative Japan Inc.
- KDDI Corporation
- Fujitsu Limited
- Equinix Japan
Competitive Analysis
The Japan Internet Data Center (IDC) Market features a competitive landscape shaped by domestic technology firms and global cloud service providers. Key players focus on enhancing service portfolios through infrastructure expansion, strategic alliances, and high-performance computing capabilities. Leading companies such as NTT Communications, KDDI Corporation, and SoftBank maintain strong market presence through their extensive network coverage and advanced facilities. It reflects a shift toward high-density computing and edge data center deployments. Companies actively invest in energy-efficient technologies to reduce operational costs and meet sustainability goals. Security remains a critical competitive differentiator, pushing providers to upgrade cybersecurity frameworks and disaster recovery solutions. Demand for colocation services and hybrid cloud platforms continues to rise, intensifying competition across multiple service segments. Market participants aim to offer scalable and customizable solutions to serve diverse business needs, particularly from sectors such as finance, manufacturing, and e-commerce. Continuous innovation, compliance with Japan’s regulatory standards, and customer-centric service delivery define the key competitive strategies in this evolving market.
Recent Developments
- In 2025, Microsoft plans to invest about $80 billion in AI-enabled data centers, significantly increasing its investment from previous years. Over half of this investment will be directed towards the United States, supporting AI model training and the development of cloud-based applications globally. This investment is part of Microsoft's broader strategy to advance AI technology and infrastructure.
- In September 2023, Google, Microsoft, Schneider Electric, and Danfoss jointly unveiled a collaborative initiative known as the Net Zero Innovation Hub for Data Center. This groundbreaking project is developed in partnership with the Danish Data Center Industry. The proposed location for this innovative center is Fredericia, Denmark.
Market Concentration & Characteristics
The Japan Internet Data Center (IDC)Market demonstrates high concentration among a handful of dominant operators such as NTT Communications, KDDI, Fujitsu, Internet Initiative Japan and Equinix Japan, which control the majority of rack capacity and interconnection points. It features substantial entry barriers due to large capital investments in land, power and cooling infrastructure and rigorous regulatory compliance requirements. Providers leverage scale to negotiate favorable power rates and network peering agreements that yield cost advantages and premium service offerings. Smaller regional players carve out niches by providing localized support, specialized security solutions and rapid modular facility deployment. High reliability standards and stringent uptime commitments define service characteristics that drive continuous investments in redundancy, automation and eco-efficient designs. Market dynamics reward firms that deliver integrated hybrid cloud solutions, sustainable energy initiatives and robust interconnection ecosystems, reinforce the oligopolistic nature and shape future growth trajectories
Report Coverage
The research report offers an in-depth analysis based on Services, Deployment, Data Center Size, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Japan will witness increased demand for hyperscale data centers driven by cloud adoption and digital transformation.
- Edge computing will gain traction to support low-latency applications and 5G deployment.
- Colocation services will grow as enterprises seek cost-effective and scalable IT infrastructure.
- Domestic and international players will invest in green data centers to meet sustainability goals.
- AI and machine learning workloads will drive the need for high-performance computing capacity.
- Data privacy and regulatory compliance will influence data center design and operations.
- Strategic partnerships between telecom providers and data center operators will enhance connectivity.
- Demand from fintech, e-commerce, and gaming sectors will accelerate market expansion.
- Tokyo and Osaka will continue to be the primary hubs, but secondary cities will see growing interest.
- Technological advancements in cooling and power efficiency will become central to competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Internet Data Center (IDC) market?
What factors are driving the growth of the Japan Internet Data Center (IDC) market?
What are the key segments within the Japan Internet Data Center (IDC) market?
Who are the major players in the Japan Internet Data Center (IDC) market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Internet Data Center (IDC) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Internet Data Center (IDC) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,986.77 million → 2032: USD 7,626.57 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Internet Data Center (IDC) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Internet Data Center (IDC) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Internet Data Center (IDC) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Internet Data Center (IDC) Market Drivers
- 3.3 Japan Internet Data Center (IDC) Market Restraints & Challenges
- 3.4 Japan Internet Data Center (IDC) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Internet Data Center (IDC) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Internet Data Center (IDC) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Internet Data Center (IDC) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Internet Data Center (IDC) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Internet Data Center (IDC) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Internet Data Center (IDC) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Internet Data Center (IDC) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Internet Data Center (IDC) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Internet Data Center (IDC) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Internet Data Center (IDC) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Internet Data Center (IDC) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Internet Data Center (IDC) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Internet Data Center (IDC) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Internet Data Center (IDC) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Internet Data Center (IDC) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Internet Data Center (IDC) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Internet Data Center (IDC) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Internet Data Center (IDC) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Internet Data Center (IDC) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
