
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| ULatin America Construction Aggregates Market Size 2024 | USD 20,690.81 million |
| Latin America Construction Aggregates Market , CAGR | 3.81% |
| Latin America Construction Aggregates Market Size 2032 | USD 27,900.60 million |
Market Overview
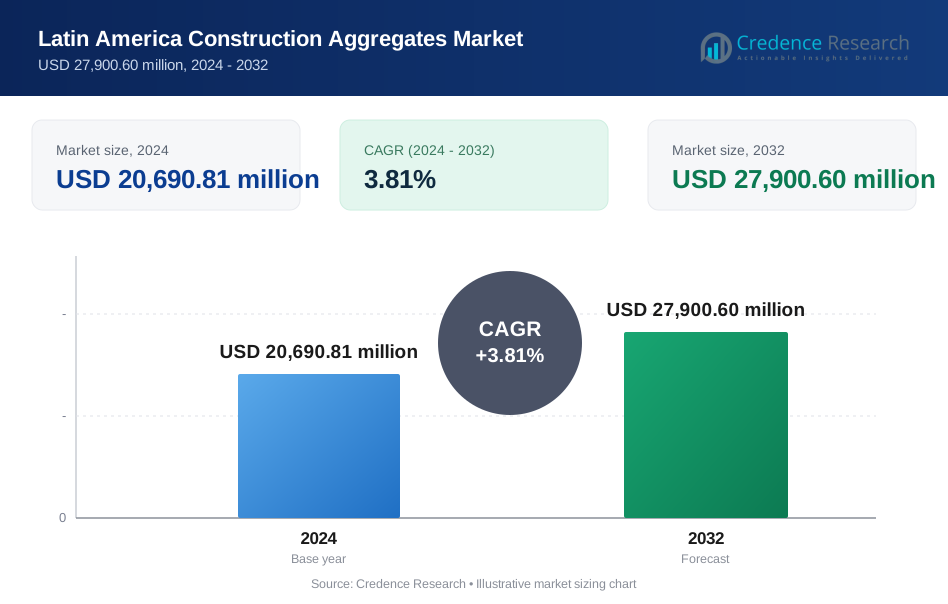
Latin America Construction Aggregates market size was valued at USD 20,690.81 million in 2024 and is anticipated to reach USD 27,900.60 million by 2032, at a CAGR of 3.81% during the forecast period (2024-2032).
The Latin America construction aggregates market is driven by rapid urbanization, infrastructure development, and increasing government investments in transportation and residential projects. Rising demand for sustainable and recycled aggregates, along with technological advancements in mining and processing, is shaping market growth. The region's growing population and expanding middle class fuel the need for commercial and housing developments, further boosting aggregate consumption. Additionally, public-private partnerships (PPPs) and foreign direct investments (FDIs) are accelerating large-scale infrastructure projects, such as highways, bridges, and rail networks. Trends indicate a shift toward eco-friendly aggregates, driven by stringent environmental regulations and sustainability goals. Advancements in automation and digitalization within the mining sector are enhancing efficiency and reducing operational costs. However, market growth may face challenges due to fluctuating raw material prices and regulatory constraints. Despite these hurdles, the sector is poised for steady expansion, supported by strong economic growth and increasing construction activities.
The Latin America construction aggregates market is geographically diverse, with significant demand driven by infrastructure projects, urbanization, and industrial expansion across countries like Brazil, Argentina, Peru, Chile, and Colombia. Rapid urban growth and government investments in transportation, housing, and commercial developments are key factors influencing aggregate consumption. Brazil and Mexico lead in infrastructure development, while countries like Peru and Chile focus on earthquake-resistant construction, increasing demand for high-quality aggregates. The market is highly competitive, with key players such as CRH plc, CEMEX S.A.B. de C.V., Heidelberg Materials AG, Vulcan Materials Company, and Martin Marietta Materials Inc. dominating the industry. These companies focus on technological advancements, sustainability, and strategic acquisitions to expand their market presence. Additionally, local and regional players contribute significantly to aggregate supply, catering to growing construction demands. As sustainability concerns rise, major companies are investing in eco-friendly and recycled aggregates to align with evolving environmental regulations and industry trends.
Market Insights
- The Latin America construction aggregates market was valued at USD 20,690.81 million in 2024 and is projected to reach USD 27,900.60 million by 2032, growing at a CAGR of 3.81%.
- Rapid urbanization and infrastructure investments, including roads, bridges, and residential projects, are driving market growth.
- Sustainable and recycled aggregates are gaining popularity due to strict environmental regulations and growing demand for eco-friendly construction materials.
- Leading players such as CRH plc, CEMEX S.A.B. de C.V., and Heidelberg Materials AG are expanding through acquisitions and technological advancements.
- Regulatory restrictions, fluctuating raw material prices, and supply chain disruptions pose challenges to market expansion.
- Brazil, Argentina, Peru, Chile, and Colombia are major contributors, with government-backed infrastructure projects fueling aggregate demand.
- Increasing adoption of automation, digital monitoring, and innovative processing technologies is enhancing production efficiency and cost-effectiveness in the sector.
Report scope
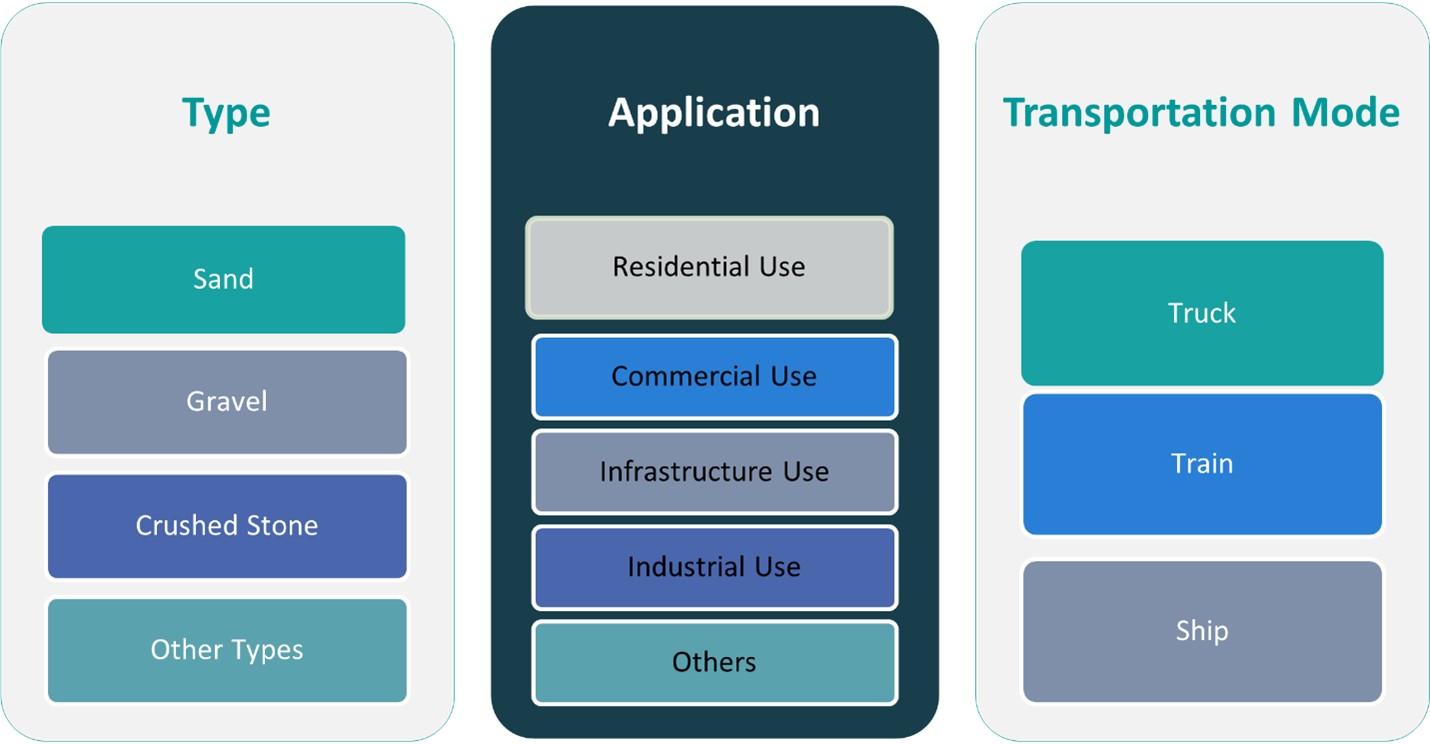
This report segments the Latin America Construction Aggregates Market as follows:
Market Drivers
Rapid Urbanization and Infrastructure Development
Latin America’s construction aggregates market is primarily driven by rapid urbanization and the increasing need for infrastructure development. With a growing population and expanding urban centers, governments across the region are heavily investing in roads, bridges, airports, and housing projects to meet rising demand. For instance, Brazil's Ministry of Infrastructure has launched initiatives to modernize highways and expand airport facilities, while Mexico's Secretariat of Communications and Transportation is focusing on large-scale railway projects to enhance connectivity. Public-private partnerships (PPPs) and government-led initiatives further accelerate construction activities, increasing the consumption of aggregates such as sand, gravel, and crushed stone. This surge in infrastructure investments significantly contributes to market expansion.
Rising Demand for Sustainable and Recycled Aggregates
Sustainability concerns and environmental regulations are reshaping the construction aggregates industry in Latin America. Governments and industry players are increasingly promoting the use of recycled and eco-friendly aggregates to minimize environmental impact. For instance, Argentina's National Institute of Industrial Technology has been actively researching methods to recycle construction waste into usable aggregates, while Chile's Ministry of Environment has implemented policies encouraging the use of low-carbon materials in public projects. The adoption of sustainable construction practices, such as green buildings and low-carbon materials, is driving demand for alternative aggregates like recycled concrete and slag. Additionally, strict mining regulations and land use policies are pushing companies to develop efficient recycling methods, reducing reliance on natural resources. This trend aligns with global sustainability goals and enhances the long-term viability of the aggregates market.
Growth in the Residential and Commercial Construction Sectors
The expanding middle class and increasing disposable incomes in Latin America are fueling demand for residential and commercial construction. Countries such as Colombia, Chile, and Peru are witnessing a surge in housing projects, commercial buildings, and retail spaces, driving aggregate consumption. Government-backed affordable housing initiatives and real estate investments are further boosting the market. The rise of smart cities and urban renewal programs is also accelerating the need for high-quality aggregates, reinforcing the sector’s positive growth outlook. Moreover, tourism-driven commercial infrastructure, such as hotels and resorts, is contributing to market expansion.
Technological Advancements in Mining and Processing
Technological innovations in mining and aggregate processing are playing a crucial role in improving efficiency and reducing costs. Advanced machinery, automation, and digitalization are streamlining extraction and production processes, ensuring higher output with minimal environmental impact. The adoption of artificial intelligence (AI) and data analytics is optimizing supply chain management, leading to better demand forecasting and inventory control. Additionally, innovations in crushing and screening equipment are enhancing the quality and durability of aggregates, making them more suitable for modern construction needs. These advancements not only drive market growth but also improve sustainability and operational efficiency.
Market Trends
Shift Toward Sustainable and Recycled Aggregates
Sustainability is a key trend shaping the Latin America construction aggregates market. Governments and industry players are increasingly adopting eco-friendly alternatives, such as recycled concrete, slag, and manufactured sand, to reduce environmental impact. Stricter environmental regulations are driving the shift toward sustainable mining practices and waste reduction strategies. Companies are investing in advanced recycling technologies to enhance material reuse, minimizing dependency on natural resources. As green building certifications and carbon footprint reduction goals gain traction, the demand for sustainable aggregates continues to rise, fostering long-term market growth.
Increasing Adoption of Advanced Mining and Processing Technologies
Technological advancements are transforming aggregate extraction and processing, improving efficiency and cost-effectiveness. For instance, mining companies in Mexico are utilizing AI-driven quality control systems to enhance material grading, while Brazil's Geological Survey has adopted drones and remote sensing technologies for resource exploration and site monitoring. Innovations in crushing and screening equipment allow for better material grading and quality, meeting the evolving demands of modern construction. Additionally, the use of drones and remote sensing technologies is optimizing resource exploration and site monitoring, reducing labor costs and improving safety. These advancements enable producers to meet growing demand while maintaining high-quality standards in aggregate production.
Growing Infrastructure Investments and Public-Private Partnerships (PPPs)
Latin America's governments are prioritizing infrastructure development to support economic growth, leading to increased investments in transportation, energy, and urban development projects. For instance, Brazil's Ministry of Infrastructure has launched extensive highway modernization projects under PPP frameworks, while Colombia's National Infrastructure Agency is spearheading railway development initiatives to improve connectivity. Countries like Brazil, Mexico, and Colombia are witnessing a surge in infrastructure spending, driving aggregate demand. Additionally, foreign direct investment (FDI) in the construction sector is facilitating the development of smart cities and sustainable urban planning initiatives. These infrastructure projects are expected to sustain long-term growth in the construction aggregates market.
Rising Demand for High-Performance and Specialty Aggregates
As construction projects become more complex, the demand for high-performance and specialty aggregates is increasing. Builders and contractors are seeking aggregates with superior durability, strength, and resistance to extreme weather conditions. Specialty aggregates, such as lightweight aggregates for high-rise buildings and skid-resistant materials for road construction, are gaining traction. Additionally, the growing emphasis on seismic-resistant infrastructure in earthquake-prone regions of Latin America is driving demand for high-quality aggregates. This trend is encouraging manufacturers to develop innovative aggregate solutions that meet the evolving needs of the construction industry.
Market Challenges Analysis
Regulatory and Environmental Constraints
The Latin America construction aggregates market faces significant challenges due to stringent regulatory frameworks and environmental concerns. Governments across the region are implementing stricter mining and land-use policies to mitigate the environmental impact of aggregate extraction. Compliance with these regulations increases operational costs for mining companies, as they must invest in sustainable extraction techniques and environmental impact assessments. Additionally, restrictions on quarrying in environmentally sensitive areas limit access to high-quality raw materials, affecting supply stability. Lengthy approval processes for new mining projects further delay expansion efforts, creating supply chain disruptions and potential project delays in the construction sector.
Fluctuating Raw Material Costs and Supply Chain Disruptions
Price volatility in raw materials, transportation, and energy costs poses a challenge for the construction aggregates industry. For instance, Mexico's National Institute of Statistics and Geography has reported fluctuations in fuel and machinery costs due to inflation, impacting profit margins for aggregate producers. Additionally, supply chain disruptions caused by inadequate infrastructure, political instability, and trade restrictions can affect the timely delivery of aggregates to construction sites. Limited transportation networks in rural and remote areas further exacerbate logistical challenges, increasing costs and reducing market efficiency.
Market Opportunities
The Latin America construction aggregates market presents significant growth opportunities driven by increasing infrastructure investments and urbanization. Governments across the region are prioritizing large-scale infrastructure projects, including roads, bridges, rail networks, and ports, to support economic development. Public-private partnerships (PPPs) and foreign direct investment (FDI) are fueling the expansion of construction activities, creating a steady demand for aggregates. Additionally, the rapid growth of urban centers and rising population density are accelerating the need for residential and commercial real estate development. This surge in construction projects offers a lucrative opportunity for aggregate producers to expand their operations and meet the growing demand for high-quality materials.
Technological advancements in aggregate processing and mining efficiency are further unlocking market potential. The adoption of automated machinery, digital monitoring systems, and advanced crushing and screening technologies is enhancing productivity and reducing operational costs. Furthermore, the increasing emphasis on sustainability is opening new opportunities for recycled and eco-friendly aggregates, as governments and construction firms seek environmentally responsible alternatives. Innovations in material processing, such as the use of industrial by-products and waste materials in aggregate production, are helping companies meet regulatory requirements while improving cost efficiency. As sustainability-driven policies and smart city initiatives gain momentum, aggregate producers that invest in green solutions and advanced technologies will gain a competitive edge in the evolving market landscape.
Market Segmentation Analysis:
By Type:
The Latin America construction aggregates market is categorized into sand, gravel, crushed stone, and other types, each serving distinct construction needs. Sand is a fundamental material used in concrete production, plastering, and brick manufacturing, making it a highly demanded aggregate in both residential and commercial projects. The rising construction of housing developments and office spaces continues to drive sand consumption. Gravel is widely used in road construction, drainage systems, and foundation work due to its durability and permeability. The expansion of transportation networks and infrastructure projects across Latin America fuels demand for high-quality gravel. Crushed stone is essential for heavy construction, including highways, bridges, and large-scale commercial developments, due to its superior strength and load-bearing capacity. Increasing investments in urban infrastructure and industrial zones are boosting the consumption of crushed stone. Other aggregates, including recycled and artificial aggregates, are gaining traction as sustainability concerns push the industry toward eco-friendly alternatives, presenting new opportunities for manufacturers.
By Application:
The application-based segmentation of the Latin America construction aggregates market includes residential, commercial, infrastructure, and industrial use, each playing a crucial role in market dynamics. The residential sector is a key driver of aggregate demand, with growing urbanization and government initiatives promoting affordable housing projects. The increasing middle-class population and demand for modern housing developments contribute to sustained growth in this segment. Commercial construction, including office buildings, shopping centers, and hotels, also drives aggregate consumption, fueled by foreign investments and tourism expansion. Infrastructure projects, such as roads, highways, railways, and airports, represent a major segment, with governments prioritizing transportation improvements and smart city initiatives. The industrial sector, including manufacturing facilities and logistics hubs, relies on high-quality aggregates for site development and structural foundations. With ongoing industrialization and economic growth, the demand for durable construction materials continues to rise, solidifying the market's long-term expansion across all application segments.
Segments:
Based on Type:
- Sand
- Gravel
- Crushed Stone
- Other Types
Based on Application:
- Residential Use
- Commercial Use
- Infrastructure Use
- Industrial Use
Based on End- User:
- Truck
- Train
- Ship
Based on the Geography:
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
Regional Analysis
Brazil
Brazil holds the largest market share, accounting for approximately 35% of the total regional market. The country’s strong construction sector, driven by large-scale infrastructure projects, urban housing developments, and industrial expansion, fuels the demand for aggregates. The Brazilian government’s investments in transportation networks, such as roads, railways, and ports, along with preparations for international events and economic recovery initiatives, continue to drive market growth. Additionally, public-private partnerships (PPPs) and foreign direct investments (FDI) in commercial and residential real estate further boost the demand for sand, gravel, and crushed stone.
Argentina
Argentina contributes around 15% of the Latin America construction aggregates market, driven by growing investments in road construction, urban infrastructure, and commercial projects. Government-backed infrastructure programs, including highway expansion and smart city initiatives, are key factors supporting market growth. The demand for high-quality aggregates, especially crushed stone, is rising due to Argentina’s focus on strengthening transportation and industrial infrastructure. However, economic fluctuations and regulatory challenges sometimes hinder steady growth in the sector. Despite these challenges, the ongoing modernization of urban centers and increasing foreign investment in construction projects are expected to support the market's long-term expansion.
Peru and Chile
Peru and Chile collectively account for 20% of the Latin American market, with Peru contributing 12% and Chile 8%. Peru’s construction sector benefits from strong government spending on infrastructure, including roadways, bridges, and public housing projects, boosting demand for aggregates. The country’s mining industry also plays a vital role in aggregate consumption, as large-scale mining projects require high-quality materials for site development and processing plants. Meanwhile, Chile’s market is driven by urbanization, seismic-resistant infrastructure development, and growing demand for sustainable aggregates. Chile’s emphasis on earthquake-resistant buildings has increased the demand for specialty aggregates that enhance structural durability and safety.
Colombia and the Rest of Latin America
Colombia and the Rest of Latin America together hold 30% of the market share, with Colombia contributing 10% and the remaining countries accounting for 20%. Colombia's growing urban infrastructure, highway expansion projects, and residential construction boom are key drivers of the aggregates market. The government’s focus on improving transportation networks and increasing housing availability continues to boost demand for sand, gravel, and crushed stone. In other Latin American nations, such as Ecuador, Bolivia, and Central American countries, the construction sector is expanding due to economic growth, urban migration, and increasing government investment in infrastructure. These regions present significant opportunities for aggregate suppliers as construction demand rises across diverse sectors.
Key Player Analysis
- CRH plc
- CEMEX S.A.B. de C.V.
- Heidelberg Materials AG
- Vulcan Materials Company
- Martin Marietta Materials Inc.
- Adbri Limited
- Eagle Materials Inc.
- SRC Group
- Tarmac
- Sika AG
- Boral Limited
Competitive Analysis
The Latin America construction aggregates market is highly competitive, with both global and regional players striving to strengthen their market presence through innovation, expansion, and acquisitions. Leading companies such as CRH plc, CEMEX S.A.B. de C.V., Heidelberg Materials AG, Vulcan Materials Company, and Martin Marietta Materials Inc. dominate the industry by leveraging advanced technologies, sustainable solutions, and strategic partnerships. These players focus on enhancing operational efficiency, adopting automated mining techniques, and investing in digital monitoring systems to optimize production and supply chain management. Sustainability is a key differentiator, with major companies increasingly investing in eco-friendly aggregates and recycled materials to align with environmental regulations and market trends. Additionally, mergers and acquisitions have been instrumental in consolidating market positions, enabling firms to expand their geographic reach and customer base. While global players hold significant market share, regional companies remain competitive by offering cost-effective solutions and catering to local construction demands. As infrastructure development continues across Latin America, competition among key players is expected to intensify, driving further innovation and market growth.
Recent Developments
- In September 2024, Holcim started the Holcim Sustainable Construction Academy. This is a free online training program that teaches about eco-friendly building methods. It helps people who work in construction learn new skills. The program offers both online classes and face-to-face training.
- In October 2024, CRH Ventures launched the Sustainable Building Materials accelerator to scale up creative climate and build technology firms that specialize in CO2-mineralized materials and sustainable binder solutions.
- In July 2024, Heidelberg Materials launched a recycling plant in Katowice, Poland, using a patented ReConcrete process to recycle demolition concrete and replace virgin material.
- In July 2024, Cemex USA formed a joint venture with Couch Aggregates and Premier Holdings for the production and distribution of aggregates in the Mid-South region. Cemex USA already had a strategic partnership with Couch Aggregates. The company stated that this vertical integration, combined with Premier Holdings' Gulf Coast marine terminals, would accelerate its regional growth.
- In April 2024, Rogers Group joined The Road Forward initiative to advance sustainable asphalt production and paving practices.
- In January 2024, Heidelberg Materials launched Evo Build, its new global brand for low-carbon and circular products. This initiative aims to provide sustainable solutions for the construction industry, focusing on reducing carbon emissions and promoting circular economy principles.
Market Concentration & Characteristics
The Latin America construction aggregates market is moderately concentrated, with a mix of global industry leaders and regional suppliers competing to meet the growing demand for construction materials. Major players such as CRH plc, CEMEX S.A.B. de C.V., and Heidelberg Materials AG dominate the market through large-scale production, technological advancements, and strategic acquisitions. These companies benefit from extensive distribution networks, advanced mining techniques, and sustainability initiatives, giving them a competitive edge. However, local and mid-sized producers play a crucial role in catering to region-specific demands, offering cost-effective solutions and flexible supply chains. The market is characterized by increasing investment in automation, digitalization, and eco-friendly aggregates, as sustainability regulations become more stringent. Infrastructure development, urbanization, and rising residential and commercial construction drive market expansion. Despite challenges such as raw material price fluctuations and regulatory constraints, the industry remains dynamic, with ongoing innovations shaping the competitive landscape.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Transportation Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Latin America construction aggregates market will continue to grow due to increasing infrastructure investments and urbanization.
- Governments will prioritize road, bridge, and residential construction, driving aggregate demand.
- Sustainability regulations will encourage the use of recycled and eco-friendly aggregates.
- Technological advancements in automation and digital monitoring will enhance production efficiency.
- Public-private partnerships will play a crucial role in funding large-scale construction projects.
- Market consolidation through mergers and acquisitions will strengthen the position of key players.
- Rising construction costs and fluctuating raw material prices may pose challenges to profitability.
- Demand for high-performance aggregates will increase as construction projects become more complex.
- Countries like Brazil, Mexico, and Colombia will remain key contributors to market expansion.
- Innovation in material processing and alternative aggregates will shape the future of the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urbanization and Infrastructure Development
The surge in urban population and government investments in transportation, housing, and commercial projects across Latin America are significantly increasing the demand for construction aggregates, as new roads, bridges, and buildings require large volumes of materials like sand, gravel, and crushed stone.
Rising Demand for Sustainable and Recycled Aggregates
Stricter environmental regulations and a growing focus on sustainability are driving the adoption of recycled and eco-friendly aggregates, with governments and industry players investing in technologies and policies that promote the use of alternative materials to reduce environmental impact.
Growth in Residential and Commercial Construction
An expanding middle class and rising disposable incomes are fueling a boom in residential and commercial construction, with countries like Colombia, Chile, and Peru experiencing increased demand for aggregates due to new housing developments, office buildings, and tourism-related infrastructure.
Technological Advancements in Mining and Processing
The adoption of automation, digital monitoring, and advanced crushing and screening technologies is improving production efficiency, reducing operational costs, and enabling the supply of higher-quality aggregates to meet the evolving needs of modern construction projects.
Public-Private Partnerships and Foreign Direct Investment
Large-scale infrastructure projects are increasingly funded through public-private partnerships and foreign direct investment, accelerating construction activity and aggregate consumption, particularly in countries prioritizing economic development through improved transportation and urban infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Latin America Construction Aggregates?
What factors are driving the growth of the Latin America Construction Aggregates?
What are some challenges faced by the Latin America Construction Aggregates?
Who are the major players in the Latin America Construction Aggregates?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sand
- 1.2.2 Gravel
- 1.2.3 Crushed Stone
- 1.2.4 Other Types
- 1.3 By Application
- 1.3.1 Residential Use
- 1.3.2 Commercial Use
- 1.3.3 Infrastructure Use
- 1.3.4 Industrial Use
- 1.4 By Transportation Mode
- 1.4.1 Truck
- 1.4.2 Train
- 1.4.3 Ship
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20,690.81 million → 2032: USD 27,900.60 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Latin America Construction Aggregates Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Latin America Construction Aggregates Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Latin America Construction Aggregates Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Latin America Construction Aggregates Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Latin America Construction Aggregates Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Latin America Construction Aggregates Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Latin America Construction Aggregates Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Latin America Construction Aggregates Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20,690.81 million → 2032: USD 27,900.60 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Latin America Construction Aggregates Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sand
- 12.3.7.2 Gravel
- 12.3.7.3 Crushed Stone
- 12.3.7.4 Other Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential Use
- 12.4.7.2 Commercial Use
- 12.4.7.3 Infrastructure Use
- 12.4.7.4 Industrial Use
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Transportation Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Truck
- 12.5.7.2 Train
- 12.5.7.3 Ship
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Latin America Construction Aggregates End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Latin America Construction Aggregates Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Latin America Construction Aggregates Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Latin America Construction Aggregates Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CRH plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CEMEX S.A.B. de C.V.
- 18.4 Heidelberg Materials AG
- 18.5 Vulcan Materials Company
- 18.6 Martin Marietta Materials Inc.
- 18.7 Adbri Limited
- 18.8 Eagle Materials Inc.
- 18.9 SRC Group
- 18.10 Tarmac
- 18.11 Sika AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

