
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Latin America Mega Data Centers Market Size 2024 | USD 1,297.30 Million |
| Latin America Mega Data Centers Market, CAGR | 5.35% |
| Latin America Mega Data Centers Market Size 2032 | USD 2,054.79 Million |
Market Overview
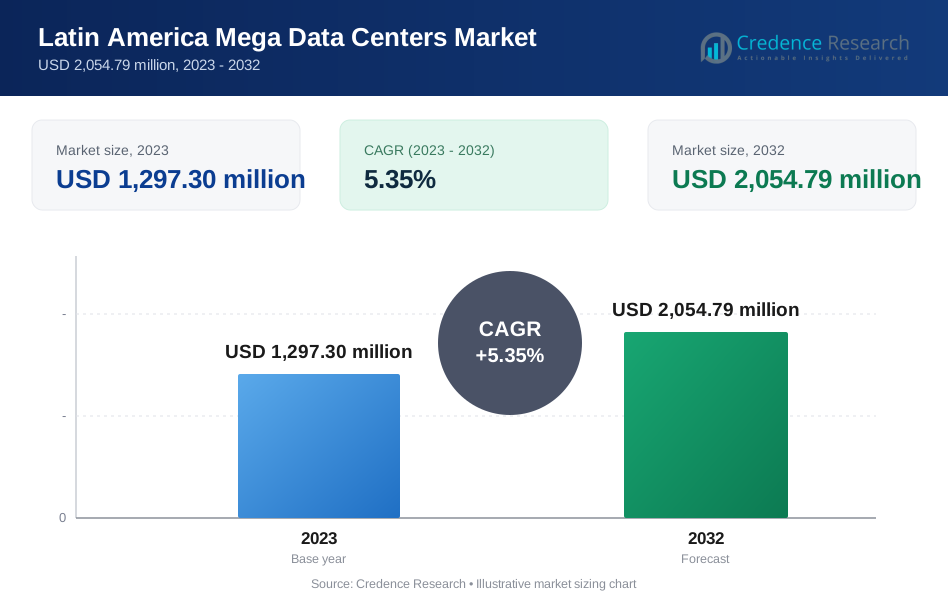
The Latin America Mega Data Centers Market is projected to grow from USD 1,297.30 million in 2023 to an estimated USD 2,054.79 million by 2032, with a compound annual growth rate (CAGR) of 5.35% from 2024 to 2032. This substantial growth is driven by the increasing demand for cloud computing, big data analytics, and the proliferation of internet services across the region.
Market drivers include the surge in digital infrastructure investments, the expansion of 5G networks, and the need for scalable and resilient data management solutions. Emerging trends such as edge computing, sustainable and energy-efficient data center designs, and the integration of advanced technologies like artificial intelligence and machine learning are also shaping the market landscape. These factors collectively contribute to the robust growth and innovation within the Latin America Mega Data Centers sector.
Geographically, Brazil dominates the Latin America Mega Data Centers Market, followed by key markets in Mexico and Chile, driven by their advanced technological infrastructure and supportive regulatory frameworks. The region's strategic emphasis on improving connectivity and reducing latency further enhances market growth. Prominent key players in the market include Equinix, Google, Amazon Web Services (AWS), Microsoft Azure, and IBM, each investing heavily in expanding their data center footprints to cater to the increasing regional demand. These companies leverage their global expertise and local presence to establish state-of-the-art facilities, ensuring high performance and reliability for their clients across Latin America.
Market Drivers
Surge in Digital Infrastructure Investments
One of the foremost drivers propelling the Latin America Mega Data Centers Market is the significant surge in investments towards digital infrastructure across the region. As businesses and governments recognize the critical importance of robust digital frameworks, substantial capital is being allocated to establish and expand data center facilities. For instance, Brazil, Chile, Argentina, and Paraguay are actively developing green data centers through collaborative efforts between operators and governments. This influx of investment is fueled by the escalating demand for reliable data storage, processing capabilities, and high-speed connectivity. Moreover, multinational corporations are increasingly setting up local data centers to enhance their service delivery and ensure compliance with data sovereignty regulations. These investments are not only aimed at meeting current demand but also at future-proofing the infrastructure to accommodate anticipated growth in data generation and consumption. The commitment to building state-of-the-art data centers underscores the region's strategic focus on becoming a pivotal hub for digital services in Latin America, thereby driving market expansion and innovation.
Proliferation of Cloud Computing and Digital Transformation Initiatives
The rapid proliferation of cloud computing services and comprehensive digital transformation initiatives constitutes a significant market driver for mega data centers in Latin America. Organizations across various sectors are increasingly migrating their operations to cloud platforms to leverage scalability, flexibility, and cost-efficiency. Latin America requires investments exceeding USD 2,220,736 million by 2030 in sectors including telecommunications to meet Sustainable Development Goals. This shift necessitates the establishment of large-scale data centers capable of supporting extensive cloud infrastructures and delivering seamless service performance. Additionally, digital transformation efforts, encompassing the adoption of advanced technologies such as artificial intelligence (AI), machine learning (ML), and big data analytics, require substantial data processing and storage capabilities. Mega data centers provide the essential backbone for these technologies, enabling businesses to harness data-driven insights and enhance operational efficiencies. The synergistic relationship between cloud computing adoption and digital transformation initiatives fosters a robust demand for mega data centers, thereby driving sustained growth in the Latin America market.
Expansion of 5G Networks and Edge Computing
The deployment and expansion of 5G networks across Latin America significantly influence the demand for mega data centers. 5G technology promises ultra-fast connectivity, low latency, and the ability to support a vast number of connected devices, which are critical for applications such as the Internet of Things (IoT), autonomous vehicles, and smart cities. In Mexico, a groundbreaking project involves deploying a private 5G-ready network across 3 underground copper mines reaching depths of nearly 1km. To fully leverage the benefits of 5G, extensive data processing and real-time analytics are required, which can be effectively managed by large-scale data centers. Additionally, the rise of edge computing complements 5G by enabling data processing closer to the source of data generation, thereby reducing latency and enhancing performance. Mega data centers play a pivotal role in supporting edge computing infrastructures by providing the necessary computational power and storage solutions. The combined impact of 5G expansion and the adoption of edge computing drives the need for more sophisticated and expansive data center facilities, thereby serving as a crucial market driver in the region.
Increasing Demand for Scalable and Resilient Data Management Solutions
The escalating need for scalable and resilient data management solutions is a critical driver for the growth of mega data centers in Latin America. As businesses generate and accumulate vast amounts of data, the requirement for efficient data storage, management, and security becomes paramount. Mega data centers offer scalable solutions that can accommodate growing data volumes and provide the flexibility to expand resources as needed. Furthermore, the emphasis on data resilience and disaster recovery ensures that critical business operations remain uninterrupted in the event of system failures or cyber-attacks. Advanced data management technologies, including virtualization, automation, and robust cybersecurity measures, are integral components of modern mega data centers, enhancing their ability to deliver reliable and secure data services. Additionally, regulatory compliance and data protection laws in Latin America necessitate robust data management infrastructures, further driving the demand for large-scale data centers. The focus on scalability and resilience not only meets current business needs but also supports future technological advancements, thereby fostering sustained growth in the mega data centers market.
Market Trends
Market Restraints and Challenges
High Capital Expenditure and Operational Costs
One of the primary restraints facing the Latin America Mega Data Centers Market is the substantial capital expenditure and ongoing operational costs associated with establishing and maintaining large-scale data center facilities. Building mega data centers requires significant investment in advanced infrastructure, including high-capacity power supply systems, state-of-the-art cooling technologies, and robust security measures. Additionally, the procurement of cutting-edge hardware and software to ensure optimal performance and scalability further escalates initial costs. Operational expenses, such as energy consumption, especially in regions with high electricity costs, contribute significantly to the financial burden. Energy-efficient solutions can mitigate some costs, but the initial investment in such technologies is often prohibitive. Furthermore, maintaining continuous operations necessitates a skilled workforce, which is in limited supply in many Latin American countries, leading to increased labor costs. These financial challenges can deter potential investors and slow the expansion of mega data centers in the region, limiting market growth despite rising demand.
Regulatory and Geopolitical Uncertainties
Regulatory and geopolitical uncertainties present significant challenges to the growth of the Latin America Mega Data Centers Market. The region comprises diverse countries, each with its own set of regulations regarding data sovereignty, privacy laws, and environmental standards. Navigating these varying regulatory landscapes can be complex and time-consuming for data center operators, potentially delaying project timelines and increasing compliance costs. Additionally, political instability and fluctuating economic conditions in certain Latin American countries can create an unpredictable business environment, discouraging long-term investments. Changes in government policies or regulations can impact operational licenses, taxation, and foreign investment rules, adding another layer of risk for investors. Moreover, concerns over data protection and cross-border data flows necessitate stringent adherence to local laws, complicating the establishment and management of data centers. These regulatory and geopolitical factors can hinder the seamless expansion of mega data centers, posing significant obstacles to market growth and stability in the Latin American region.
Market Segmentation Analysis
By Component
The "By Component" segmentation of the Latin America Mega Data Centers Market is divided into Solutions and Services. Solutions refer to comprehensive packages that encompass hardware, software, and integrated services necessary for the seamless operation of data centers. These solutions are designed to ensure efficient and scalable infrastructure. On the other hand, Services include ongoing maintenance, consulting, and support, all of which are crucial for maintaining the optimal performance and reliability of data center infrastructure, ensuring its long-term functionality and resilience.
By Solution Type
By solution type, the Latin America Mega Data Centers Market is categorized into several key areas. IT Infrastructure Solutions comprise essential components like servers, storage systems, networking equipment, and virtualization technologies, forming the foundation of data center operations. Support Infrastructure Solutions include facilities management, security systems, and disaster recovery solutions that ensure the smooth functioning of the core IT infrastructure. Power Solutions cover critical equipment such as uninterruptible power supplies (UPS), backup generators, and power distribution units (PDUs), ensuring continuous operations. Cooling Solutions focus on advanced technologies like liquid cooling, free-air cooling, and HVAC systems to maintain optimal temperature and humidity levels. Lastly, Others include ancillary components such as fire suppression systems, cabling infrastructure, and monitoring tools, all of which enhance the overall functionality and safety of data centers.
Segments
Based on Component
- Solutions
- Services
Based on Solution Type
- IT Infrastructure Solutions
- Support Infrastructure Solutions
- Power Solutions
- Cooling Solutions
- Others
Based on End User
- Cloud Providers
- Collocation Providers
- Enterprises
Based on Service Type
- System Integration
- Monitoring Services
- Professional Services
Based on Enterprise Size
- Small & Medium Enterprises (SMEs)
- Large Enterprises
Based on Industry Vertical
- Banking, Financial Services & Insurance (BFSI)
- Telecom & IT
- Media & Entertainment
- Government & Public Sector
- Others
Based on Region
- Brazil
- Mexico
- Chile
- Other Latin American Countries
Regional Analysis
Brazil (40%):
Brazil is the leading country in the Latin America Mega Data Centers Market, holding approximately 40% of the market share. This dominance is due to the country’s advanced technological infrastructure, large population base, and strategic importance for global cloud providers and enterprises. Brazil has seen substantial investments from international players such as Microsoft Azure, Google, and Amazon Web Services (AWS), which have established significant data center operations in the country. Moreover, the Brazilian government’s focus on digital transformation and smart city initiatives further boosts demand for large-scale data centers. The country’s strong regulatory environment and focus on data sovereignty make it an attractive location for global players looking to expand their footprint in Latin America.
Mexico (25%):
Mexico is the second-largest market, accounting for around 25% of the Latin America Mega Data Centers Market. Mexico’s geographic proximity to the United States and its growing digital economy make it a strategic location for data center investments. Global cloud service providers and colocation companies are increasingly choosing Mexico to establish their mega data centers, particularly in cities like Querétaro, which is becoming a major data center hub. The Mexican government’s efforts to improve internet penetration and 5G network rollouts further contribute to the growth of the data center market. The country’s regulatory reforms and incentives for foreign investments also encourage the development of digital infrastructure.
Key players
- IBM Corporation
- Dell Software Inc.
- Cisco Systems Inc.
- Intel Corporation
- Schneider Electric
- Vertiv Group Corp.
- Amazon Web Services (AWS)
- Global Switch
- Digital Realty
- Microsoft
Competitive Analysis
The Latin America Mega Data Centers Market is highly competitive, with key players like IBM, Cisco, Intel, and Microsoft establishing a strong presence through their extensive product portfolios and strategic investments in the region. These companies, along with cloud giants such as Amazon Web Services (AWS) and Google, dominate the market by leveraging their global expertise in cloud services, data management, and IT infrastructure solutions. Companies like Schneider Electric and Vertiv Group Corp. provide critical support in power and cooling solutions, enabling efficient and sustainable data center operations. Dell and Digital Realty focus on offering flexible, scalable solutions to meet the growing demand for cloud and colocation services. This competitive landscape is characterized by continuous innovation, with players investing in sustainable practices, advanced technologies like AI and automation, and expanding their regional footprints to capture market share and meet the rising demand for data center services in Latin America.
Recent Developments
- In September 2024, Google announced $850 million investment for new data center (Teros facility) in Uruguay's Parque de las Ciencias Free Trade Zone, Canelones. The facility will employ 300In400 workers during construction, peaking at 800, with 50 permanent positions once operational.
- In May 2024, Microsoft launched its first data center region (Mexico Central) in Queretaro, Mexico. The project is part of Microsoft's commitment to create over 300,000 jobs across different industries in Mexico.
- In March 2024, AWS announced plans to invest $5 billion over 15 years to launch three data centers in Queretaro, Mexico by early 2025. This will be AWS's second region in Latin America, joining the existing South America (São Paulo) region.
Market Concentration and Characteristics
The Latin America Mega Data Centers Market exhibits a moderately concentrated structure, with a few dominant global players such as Amazon Web Services (AWS), Microsoft, Google, and IBM leading the market, alongside regional providers like Digital Realty and Global Switch. These companies possess significant resources and expertise, allowing them to invest heavily in infrastructure, innovation, and sustainability initiatives, which creates high entry barriers for smaller players. The market is characterized by high demand for cloud services, colocation facilities, and scalable IT solutions, driven by digital transformation efforts, the expansion of 5G networks, and increasing data consumption. The presence of both multinational corporations and local firms fosters a competitive environment where technological advancements, energy efficiency, and compliance with regional data protection laws are crucial for maintaining market share and longInterm growth.
Report Coverage
The research report offers an inIndepth analysis based on Component, Solution Type, End User, Service Type, Enterprise Size, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Latin America Mega Data Centers Market is expected to maintain steady growth, with projections of reaching USD 2,054.79 million by 2032, driven by increasing demand for data storage and processing solutions.
- Cloud services will continue to be a key driver, as businesses and governments accelerate their migration to cloud platforms to enhance scalability, flexibility, and costInefficiency.
- Major global players and regional firms will keep investing heavily in expanding data center capacities, particularly in Brazil, Mexico, and Chile, to support growing data demands.
- There will be a growing focus on sustainable data center operations, with companies adopting renewable energy sources and innovative cooling technologies to reduce their environmental impact.
- The growth of 5G networks will drive the need for edge computing solutions, prompting the establishment of more localized mega data centers to reduce latency and improve data processing speeds.
- As data privacy concerns increase, especially with new regulations, data centers will focus on improving cybersecurity measures and ensuring compliance with regional and global data protection standards.
- Demand for colocation services is expected to rise as small and medium enterprises (SMEs) seek costIneffective ways to access highInperformance infrastructure without owning their own data centers.
- The integration of artificial intelligence (AI), machine learning (ML), and automation will become more prevalent, optimizing data center operations and enhancing efficiency.
- Countries like Argentina, Colombia, and Peru will see increased investments, becoming important emerging markets for mega data centers as their digital economies expand.
- Major companies such as AWS, Google, and Microsoft will continue to dominate the market, leveraging their expertise and resources to expand their regional presence and meet growing demand for cloud and data services.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Latin America Mega Data Centers Market in 2023 and 2032, and what is the CAGR?
What are the primary factors driving the growth of the Latin America Mega Data Centers Market?
How is cloud computing influencing the Latin America Mega Data Centers Market?
Which countries are leading the market for mega data centers in Latin America?
What role do emerging technologies like AI and edge computing play in the market?
Who are the key players in the Latin America Mega Data Centers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Latin America Mega Data Centers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Latin America Mega Data Centers Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,297.30 million → 2032: USD 2,054.79 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Latin America Mega Data Centers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Latin America Mega Data Centers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Latin America Mega Data Centers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Latin America Mega Data Centers Market Drivers
- 3.3 Latin America Mega Data Centers Market Restraints & Challenges
- 3.4 Latin America Mega Data Centers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Latin America Mega Data Centers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Latin America Mega Data Centers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Latin America Mega Data Centers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Latin America Mega Data Centers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Latin America Mega Data Centers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Latin America Mega Data Centers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Latin America Mega Data Centers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Latin America Mega Data Centers Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Latin America Mega Data Centers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Latin America Mega Data Centers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Latin America Mega Data Centers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Latin America Mega Data Centers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Latin America Mega Data Centers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Latin America Mega Data Centers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Latin America Mega Data Centers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Latin America Mega Data Centers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Latin America Mega Data Centers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Latin America Mega Data Centers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Latin America Mega Data Centers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
