
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
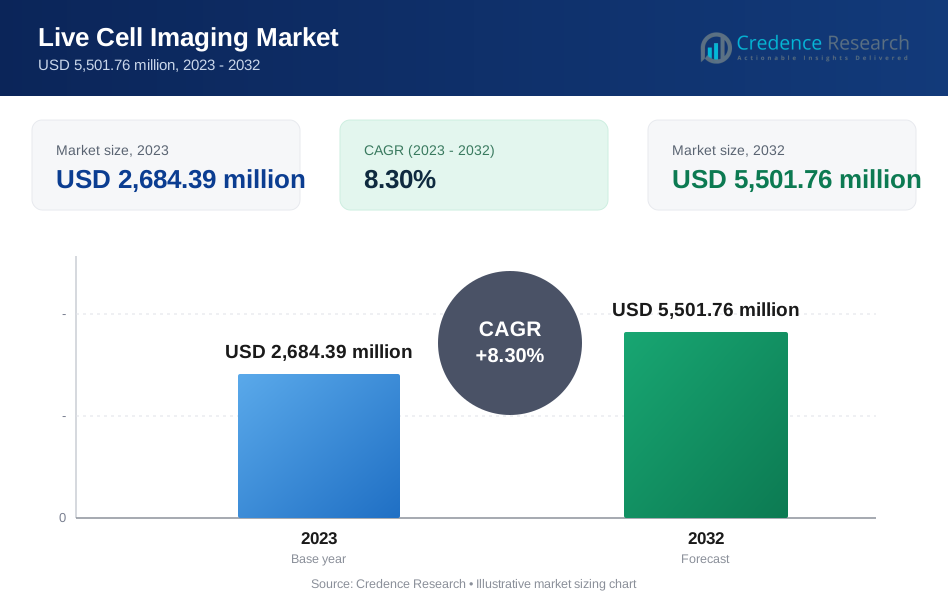
| Live Cell Imaging Market Size 2023 | USD 2,684.39 Million |
| Live Cell Imaging Market, CAGR | 8.30% |
| Live Cell Imaging Market Size 2032 | USD 5,501.76 Million |
Market Overview
The Live Cell Imaging Market is projected to grow from USD 2,684.39 million in 2023 to an estimated USD 5,501.76 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.30% from 2024 to 2032. This substantial growth is driven by advancements in imaging technologies, increasing adoption of live cell imaging in drug discovery, and rising demand for research in cell biology and cancer studies.
Key market drivers include the growing emphasis on personalized medicine, advancements in high-resolution imaging techniques, and increasing investments in healthcare research. The integration of artificial intelligence (AI) and machine learning into imaging technologies is also significantly enhancing the capabilities of live cell imaging, enabling more precise and real-time cellular analysis. Furthermore, the rise in chronic diseases, including cancer, is driving the demand for live cell imaging for early diagnosis and treatment development.
Geographically, North America dominates the Live Cell Imaging Market due to the presence of advanced healthcare infrastructure, leading pharmaceutical companies, and ongoing research activities. Europe follows closely, supported by a growing focus on biotechnology and life sciences. The Asia Pacific region is anticipated to witness the highest growth during the forecast period, driven by increasing investments in healthcare and research. Key players in the market include Carl Zeiss AG, Leica Microsystems, Nikon Corporation, Thermo Fisher Scientific, and Becton, Dickinson, and Company.
Market Drivers
Advancements in Imaging Technologies
Advancements in imaging technologies are one of the primary drivers of the live cell imaging market. Over the past decade, technological innovations have transformed the field of cell biology, enabling researchers to observe cellular processes in real-time with higher precision and clarity. High-resolution imaging systems such as confocal microscopy, multi-photon imaging, and fluorescence resonance energy transfer (FRET) have revolutionized live cell imaging by offering improved depth and spatial resolution. These technologies provide deeper insights into cellular dynamics, allowing scientists to study complex cellular processes such as cell signaling, motility, and interactions within their native environment. For instance, Yokogawa has developed high-speed confocal microscopes like the CSU10, which enable real-time imaging of living cells with high signal-to-noise ratios. Additionally, advancements in time-lapse imaging techniques enable researchers to observe and record cellular changes over time, thus enhancing the understanding of cellular behavior. The integration of artificial intelligence (AI) and machine learning (ML) with imaging platforms is another significant development, providing automated image analysis and data interpretation. This not only accelerates the research process but also improves the accuracy of experimental outcomes. As these technologies continue to evolve, they are expected to drive further growth in the live cell imaging market by enhancing the capabilities and applications of live cell imaging in fields such as drug discovery, cancer research, and developmental biology.
Increasing Demand in Drug Discovery and Development
The growing application of live cell imaging in drug discovery and development is another significant driver for market growth. In the pharmaceutical and biotechnology sectors, live cell imaging is used extensively to study drug-cell interactions, evaluate drug efficacy, and understand disease mechanisms. It plays a critical role in identifying potential therapeutic targets, monitoring cellular responses to drug treatments, and determining the mechanisms of action of new compounds. Live cell imaging allows for real-time observation of how drugs affect cellular behavior, such as proliferation, apoptosis, or migration. This capability is particularly valuable in cancer research, where the ability to observe tumor cells in real-time can provide critical insights into the effectiveness of anti-cancer therapies. For instance, AstraZeneca utilizes live cell imaging to study drug pharmacology and identify novel therapeutic targets. Additionally, live cell imaging facilitates the study of pharmacokinetics and pharmacodynamics, enabling researchers to monitor drug distribution and metabolism within live cells. This application reduces the reliance on static endpoint assays, offering more dynamic and comprehensive insights into drug performance. As the demand for more efficient and effective drug discovery processes increases, live cell imaging is becoming an indispensable tool in the pharmaceutical industry, further fueling the market’s growth.
Rising Prevalence of Chronic Diseases
The rising prevalence of chronic diseases, particularly cancer, cardiovascular diseases, and neurodegenerative disorders, is driving the demand for live cell imaging. Chronic diseases are often associated with complex cellular and molecular mechanisms that require real-time monitoring and analysis to understand disease progression and treatment responses. Live cell imaging allows researchers to observe these mechanisms at a cellular level, providing crucial insights into how diseases develop and progress. In cancer research, for instance, live cell imaging enables scientists to study tumor cell behavior, metastasis, and response to various treatments in real-time, offering invaluable data for developing targeted therapies. For instance, the CDC highlights the increasing prevalence of chronic diseases such as cancer and cardiovascular diseases, which necessitates advanced research tools like live cell imaging. Similarly, in neurodegenerative disease research, live cell imaging is used to study neuron activity, synapse formation, and the effects of therapeutic interventions on brain cells. As the global burden of chronic diseases continues to rise, particularly in aging populations, the demand for advanced research tools like live cell imaging is expected to increase. This trend is contributing significantly to the growth of the live cell imaging market, as researchers seek more effective ways to study and combat these diseases.
Growing Focus on Personalized Medicine
The increasing focus on personalized medicine is another major driver of the live cell imaging market. Personalized medicine, which tailors treatment plans to individual patients based on their genetic, cellular, and molecular profiles, requires advanced diagnostic and research tools to analyze cellular behavior and responses to therapies. Live cell imaging plays a crucial role in this approach by providing real-time data on how individual cells or patient-derived cells respond to different treatments. This capability enables researchers and clinicians to identify the most effective therapies for specific patients, improving treatment outcomes and reducing the risk of adverse effects. In oncology, for example, live cell imaging can be used to monitor how cancer cells from a particular patient respond to various chemotherapy drugs, allowing for more personalized and targeted treatment strategies. The ability to observe and analyze patient-specific cellular behavior is becoming increasingly important in the development of precision therapies, particularly in the fields of oncology, immunology, and regenerative medicine. As personalized medicine continues to gain traction in the healthcare industry, the demand for live cell imaging technologies is expected to grow, driving further market expansion.
Market Trends
Integration of Artificial Intelligence and Machine Learning
The integration of artificial intelligence (AI) and machine learning (ML) technologies is significantly transforming the live cell imaging market. These advanced computational tools are enhancing image analysis, enabling more accurate and efficient interpretation of complex cellular data. AI algorithms can automatically identify and quantify cellular structures, track dynamic processes, and detect subtle changes in cell behavior that might be missed by manual analysis. This automation not only accelerates the research process but also reduces the potential for human error, leading to more reliable and reproducible results. For instance, Sartorius has developed AI-driven image analysis tools that streamline the process of quantifying cell morphology and viability. Additionally, machine learning models are being developed to predict cellular responses to various treatments, facilitating personalized medicine approaches. By leveraging large datasets, AI and ML can uncover patterns and insights that drive deeper understanding of cellular mechanisms and disease pathways. Furthermore, the integration of AI with live cell imaging platforms allows for real-time data processing and visualization, providing researchers with immediate feedback and enabling dynamic adjustments to experimental conditions. As these technologies continue to advance, their adoption is expected to expand across various applications, including drug discovery, cancer research, and developmental biology, thereby propelling the growth of the live cell imaging market.
Advancements in Multiplex and High-Content Imaging Technologies
Advancements in multiplex and high-content imaging technologies represent another significant trend in the live cell imaging market. Multiplex imaging allows for the simultaneous visualization of multiple cellular components or molecular targets within a single cell, providing a more comprehensive understanding of cellular interactions and functions. This capability is particularly valuable in complex biological studies, such as those involving signaling pathways, gene expression, and protein interactions. High-content imaging (HCI) further enhances this trend by enabling the acquisition and analysis of large volumes of data from high-resolution images, facilitating high-throughput screening and detailed phenotypic analysis. For instance, Nature highlights the use of multiplex bioimaging to obtain spatially resolved proteomic, genomic, and metabolic profiles of human cancers at the single-cell level. The combination of multiplex and HCI technologies allows researchers to conduct more sophisticated experiments, uncovering intricate cellular behaviors and interactions with greater precision. Additionally, these technologies are being integrated with advanced microscopy techniques, such as super-resolution and light-sheet microscopy, to achieve unprecedented levels of detail and spatial resolution. The ability to perform multi-parameter analysis in live cells is driving innovations in areas like drug discovery, where understanding the multifaceted effects of compounds on cellular systems is crucial. As multiplex and high-content imaging technologies continue to evolve, they are expected to enhance the capabilities of live cell imaging platforms, thereby expanding their applications and contributing to the overall growth of the market.
Market Restraints and Challenges
High Costs of Advanced Imaging Technologies
One of the significant restraints on the growth of the live cell imaging market is the high cost associated with advanced imaging technologies and equipment. The sophisticated nature of live cell imaging systems, including high-resolution microscopes, fluorescence imaging devices, and specialized software for data analysis, often requires substantial financial investment. Many academic and research institutions, particularly in developing regions, may struggle to allocate adequate budgets for these expensive technologies, leading to limited access to advanced live cell imaging tools. Additionally, ongoing maintenance and operational costs can further burden research facilities, which may deter potential users from adopting these technologies. The high capital expenditure involved also poses challenges for smaller biotech companies and startups, potentially restricting innovation and limiting competition within the market. As a result, despite the promising applications and benefits of live cell imaging, the economic barriers may hinder widespread adoption and utilization, particularly among institutions with constrained resources.
Technical Complexity and Expertise Requirements
The technical complexity associated with live cell imaging is another significant challenge that impacts its market growth. Operating advanced imaging systems requires a high level of expertise and technical knowledge, making it difficult for some researchers to effectively utilize these technologies. Researchers must be proficient in multiple areas, including microscopy techniques, image processing, and data analysis, which can be a barrier to entry for those without specialized training. This complexity can lead to inconsistencies in experimental outcomes and data interpretation if not managed properly. Furthermore, the rapidly evolving nature of imaging technologies necessitates continuous training and skill development for researchers, which can be resource-intensive and time-consuming. The lack of standardized protocols and best practices in live cell imaging can also contribute to variability in results, making it challenging to replicate findings across different studies. Consequently, the demand for skilled personnel and the necessity for ongoing education in live cell imaging techniques pose significant hurdles that need to be addressed to fully realize the market's potential.
Market Segmentation Analysis
By Product and Services
The live cell imaging market is segmented based on products and services, including instruments, consumables, software, services, and others. Instruments are further categorized into microscopy and standalone systems. Microscopy remains a critical tool for live cell imaging, enabling high-resolution visualization of cellular processes. Consumables, such as reagents and other necessary materials, are essential for conducting imaging experiments, with reagents playing a key role in cell staining and visualization. The software segment focuses on image processing and data analysis, which are crucial for accurate interpretation of cellular events. Services, including maintenance and technical support, are also vital components of the market, supporting research institutions and companies in the optimal use of live cell imaging technologies.
By Application
The live cell imaging market is broadly applied across several areas, including cell biology, stem cell research, developmental biology, drug discovery, and others. In cell biology, live cell imaging allows for the observation of cellular mechanisms in real-time, offering invaluable insights into cellular behavior and interactions. Stem cell research benefits significantly from live imaging, as it helps in understanding differentiation processes and regenerative capabilities. Developmental biology leverages live imaging to study organism growth and developmental stages, while drug discovery utilizes it for real-time analysis of drug-cell interactions and therapeutic efficacy. Other applications include immunology and neuroscience, where live cell imaging helps uncover the underlying mechanisms of diseases.
Segments
Based on Product and Services
- Instruments
- Microscopy
- Standalone system
- Consumables
- Reagents
- Others
- Software
- Services
- Others
Based on Application
- Cell Biology
- Stem Cells
- Developmental Biology
- Drug Discovery
- Others
Based on End User
- Pharmaceutical & Biotechnology Companies
- Academic and Research Institutes
- Contract Research Organization
Based on Technology
- Time-lapse Micrology
- Florescence Research Energy Transfer
- Florescence Recovery after Photobleaching
- High Content Screening
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (40%):
North America holds the largest share of the live cell imaging market, accounting for approximately 40% of the total market share in 2023. The region’s dominance can be attributed to its advanced healthcare infrastructure, high investment in research and development, and the presence of key market players such as Thermo Fisher Scientific, PerkinElmer, and Carl Zeiss AG. The United States leads the market in this region, with extensive adoption of live cell imaging technologies in pharmaceutical research, biotechnology, and academic research institutions. Continuous innovation in imaging technologies, coupled with significant government funding for life sciences research, further fuels the market growth in North America.
Europe (30%):
Europe is the second-largest market, representing around 30% of the global market share. This region benefits from a strong emphasis on biotechnology and life sciences research, particularly in countries like Germany, the UK, and France. Europe’s commitment to advancing scientific research and drug discovery is a key driver of market growth, with leading research institutions and pharmaceutical companies heavily investing in live cell imaging technologies. Additionally, the European Union’s support for cross-border research collaborations has facilitated the development and adoption of advanced imaging techniques.
Key players
- Danaher
- Zeiss Group
- Nikon Corp.
- Sartorius AG
- Thermo Fisher Scientific Inc.
- Olympus Corp.
- PerkinElmer Inc.
- Etaluma Inc.
- Cytosmart Technologies
- Agilent Technologies Inc.
- Nanoentek Inc.
- Becton Dickinson and Company
- GE Healthcare
- Bruker Corp.
Competitive Analysis
The live cell imaging market is highly competitive, with several key players driving innovation and advancements. Leading companies such as Danaher, Zeiss Group, Nikon Corp., and Thermo Fisher Scientific Inc. dominate the market due to their extensive product portfolios and robust global presence. These companies focus on developing advanced imaging technologies, offering high-resolution microscopy, software for image analysis, and integrated platforms for real-time cellular observation. Additionally, companies like Olympus Corp., PerkinElmer Inc., and Becton Dickinson emphasize research and development to expand their imaging solutions, catering to pharmaceutical and academic research needs. Emerging players, including Etaluma Inc. and Cytosmart Technologies, are carving out niches by offering portable and cost-effective imaging systems. With continuous innovation and strategic partnerships, these companies are striving to capture larger market shares in the growing live cell imaging industry.
Recent Developments
- In March 2023, Danaher introduced advancements in Quantitative Phase Imaging (QPI) for live cell imaging, enhancing real-time monitoring of cellular events.
- In February 2023, Zeiss launched the ZEISS Visioner 1, an innovative digital microscope for live-cell imaging, featuring the Micro-mirror Array Lens System (MALS) for real-time focusing.
- In February 2023, Nikon announced the release of the NSPARC super-resolution unit, enabling high-resolution deep imaging of living cells and tissues.
- In 2023, Sartorius expanded its live-cell imaging capabilities with the Incucyte SX5 Live-Cell Analysis System, offering up to five colors specifically designed for live-cell imaging and analysis.
- In 2023, Thermo Fisher Scientific introduced advancements in live-cell imaging reagents and systems, including the EVOS M7000 and M5000 Cell Imaging Systems.
- In December 2022, PerkinElmer introduced the Operetta CLS High-Content Screening System for automated high-content screening assays.
- In 2022, Etaluma supported the new RegeneratOR Test Bed with the LS460Microscope, offering high-resolution live-cell imaging inside incubators.
- In June 2022, CytoSMART Technologies launched a new Organoid Analysis Module for the CytoSMART Omni live-cell imaging product line, incorporating next-generation machine learning capabilities.
- In December 2023, Agilent enhanced the BioTek Cytation C10 Confocal Imaging Reader with water immersion technology and new confocal spinning disk technology.
Market Concentration and Characteristics
The live cell imaging market is moderately concentrated, with a few dominant players holding a significant share due to their advanced technological offerings and strong global presence. Companies like Danaher, Thermo Fisher Scientific Inc., and Zeiss Group lead the market with comprehensive product portfolios, including cutting-edge microscopy systems, reagents, and imaging software. The market is characterized by continuous innovation, driven by the increasing demand for high-resolution imaging, time-lapse microscopy, and AI-powered analysis tools. Additionally, strategic partnerships, acquisitions, and ongoing research and development activities are key strategies used by major players to maintain their competitive edge. Smaller and emerging companies, such as Etaluma Inc. and Cytosmart Technologies, are also contributing to market dynamics by offering cost-effective and specialized imaging solutions, making the market competitive while still being innovation-driven.
Report Coverage
The research report offers an in-depth analysis based on product and services, application, end user, technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The integration of AI and machine learning into live cell imaging will accelerate real-time analysis, improving the accuracy and efficiency of cellular observations and data interpretation.
- The growing use of live cell imaging in drug discovery will drive market growth, as it enables real-time monitoring of drug-cell interactions and helps identify therapeutic targets more effectively.
- The rising focus on personalized medicine will boost the adoption of live cell imaging, allowing researchers to study patient-specific cellular responses, leading to tailored treatment strategies.
- As technology evolves, more cost-effective and portable live cell imaging systems are expected to emerge, making advanced imaging accessible to a wider range of research institutions globally.
- Live cell imaging will play a critical role in stem cell and cancer research, providing insights into cell differentiation and tumor behavior, further driving the market’s expansion.
- Growing investments in healthcare infrastructure and research in developing regions, particularly in Asia Pacific, will lead to increased adoption of live cell imaging technologies in these areas.
- Strategic collaborations between academic institutions, research organizations, and key market players will enhance technological advancements and expand the applications of live cell imaging in various fields.
- The adoption of high-content screening (HCS) technologies, which allow for high-throughput analysis, will continue to rise, contributing to more efficient drug screening and cellular analysis processes.
- Ongoing innovations in microscopy will lead to improved resolution and faster imaging speeds, enabling researchers to capture intricate cellular processes in real-time with greater precision.
- As governments and regulatory bodies continue to emphasize the importance of biomedical research, increased funding and regulatory support will boost the growth of the live cell imaging market in the coming years.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Imaging Technologies
Continuous innovation in high-resolution microscopy, confocal and multi-photon imaging, and integration of AI and machine learning are enabling more precise, real-time cellular analysis, expanding the capabilities and applications of live cell imaging.
Increasing Demand in Drug Discovery and Development
Live cell imaging is critical for real-time observation of drug-cell interactions, efficacy testing, and understanding disease mechanisms, making it indispensable in pharmaceutical and biotechnology research and accelerating drug development pipelines.
Rising Prevalence of Chronic Diseases
The growing incidence of cancer, cardiovascular, and neurodegenerative diseases is driving demand for advanced research tools like live cell imaging, which provides crucial insights into disease progression and treatment responses at the cellular level.
Growing Focus on Personalized Medicine
Personalized medicine relies on analyzing patient-specific cellular responses to therapies; live cell imaging enables real-time monitoring of these responses, supporting the development of tailored treatment strategies and improving clinical outcomes.
Integration of Artificial Intelligence and Machine Learning
AI and ML are transforming image analysis by automating quantification, tracking cellular processes, and predicting responses, which increases research efficiency, reduces human error, and enables high-throughput, reproducible results.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Live Cell Imaging Market in 2023 and 2032, and what is its CAGR?
What are the key factors driving the growth of the Live Cell Imaging Market?
How is artificial intelligence influencing the Live Cell Imaging Market?
Which regions dominate the Live Cell Imaging Market?
What are the main applications of live cell imaging technologies?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Pharmaceutical & Biotechnology Companies
- 1.2.2 Academic and Research Institutes
- 1.2.3 Contract Research Organization
- 1.3 By Technology
- 1.3.1 Time-lapse Microscopy
- 1.3.2 Fluorescence Resonance Energy Transfer (FRET)
- 1.3.3 Fluorescence Recovery after Photobleaching (FRAP)
- 1.3.4 High Content Screening
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Cell Biology
- 1.4.2 Stem Cells
- 1.4.3 Developmental Biology
- 1.4.4 Drug Discovery
- 1.4.5 Others
- 1.5 By Product and Services
- 1.5.1 Instruments
- 1.5.2 Consumables
- 1.5.3 Software
- 1.5.4 Services
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 2,684.39 million → 2032: USD 5,501.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Live Cell Imaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Live Cell Imaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Live Cell Imaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Live Cell Imaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Live Cell Imaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Live Cell Imaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Live Cell Imaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Live Cell Imaging Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 2,684.39 million → 2032: USD 5,501.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Live Cell Imaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceutical & Biotechnology Companies
- 12.3.7.2 Academic and Research Institutes
- 12.3.7.3 Contract Research Organization
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Time-lapse Microscopy
- 12.4.7.2 Fluorescence Resonance Energy Transfer (FRET)
- 12.4.7.3 Fluorescence Recovery after Photobleaching (FRAP)
- 12.4.7.4 High Content Screening
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cell Biology
- 12.5.7.2 Stem Cells
- 12.5.7.3 Developmental Biology
- 12.5.7.4 Drug Discovery
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product and Services - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Instruments
- 12.6.7.2 Consumables
- 12.6.7.3 Software
- 12.6.7.4 Services
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Live Cell Imaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Live Cell Imaging Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Live Cell Imaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Live Cell Imaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Danaher
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Zeiss Group
- 18.4 Nikon Corp.
- 18.5 Sartorius AG
- 18.6 Thermo Fisher Scientific Inc.
- 18.7 Olympus Corp.
- 18.8 PerkinElmer Inc.
- 18.9 Becton Dickinson and Company
- 18.10 Agilent Technologies Inc.
- 18.11 Bruker Corp.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

