
Market Overview
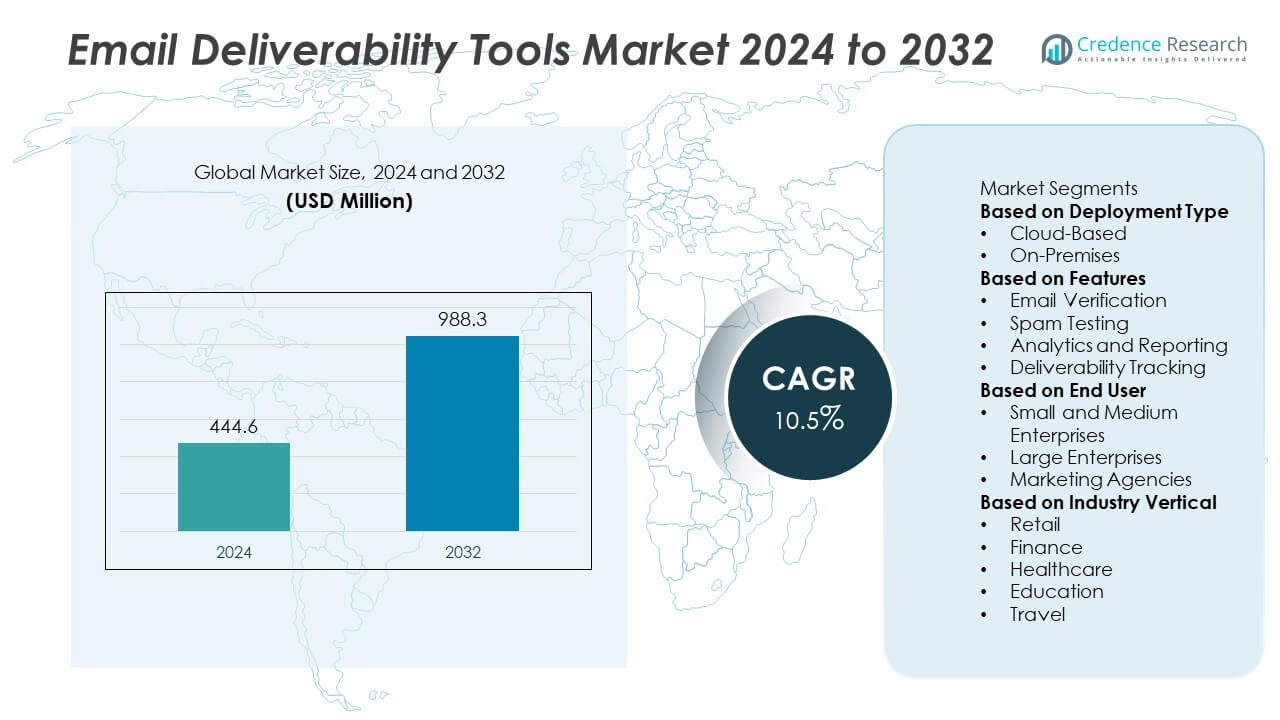
The Email Deliverability Tools Market was valued at USD 444.6 million in 2024 and is projected to reach USD 988.3 million by 2032, growing at a strong CAGR of 10.5% during the forecast period (2024–2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Email Deliverability Tools Market Size 2024 | USD 444.6 Million |
| Email Deliverability Tools Market, CAGR | 10.5% |
| Email Deliverability Tools Market Size 2032 | USD 988.3 Million |
The Email Deliverability Tools Market grows on strong drivers such as rising global email volumes, stricter compliance regulations, and the need for businesses to maintain sender reputation and ensure inbox placement. It benefits from increasing adoption across industries like e-commerce, BFSI, and healthcare, where reliable communication is essential. Market trends highlight the integration of AI-driven analytics, predictive deliverability scoring, and advanced authentication protocols that enhance performance and security.
The Email Deliverability Tools Market demonstrates strong geographical presence, with North America leading adoption due to its mature digital marketing ecosystem and wide use of SaaS-based platforms. Europe follows with significant demand driven by strict regulatory compliance such as GDPR, while Asia-Pacific emerges as the fastest-growing region, supported by rapid digital transformation and rising e-commerce activity. Latin America and the Middle East & Africa show steady growth as SMEs and enterprises adopt deliverability solutions to improve customer engagement and communication reliability. Key players such as SendGrid (Twilio), Mailgun, SparkPost, and Amazon SES play a pivotal role by offering scalable cloud-based platforms, advanced inbox monitoring, and authentication features.
Market Insights
- The Email Deliverability Tools Market was valued at USD 444.6 million in 2024 and is projected to reach USD 988.3 million by 2032, growing at a CAGR of 10.5% during the forecast period.
- Growth is fueled by rising global email volumes, stricter compliance regulations, and the increasing need for businesses to maintain sender reputation and ensure reliable inbox placement.
- Key market trends include AI-driven deliverability scoring, predictive analytics for campaign optimization, and expanding use of advanced authentication protocols such as SPF, DKIM, DMARC, and BIMI to improve security and trust.
- Competitive dynamics are shaped by leading vendors such as SendGrid (Twilio), Mailgun, SparkPost, Amazon SES, and Constant Contact, who focus on scalable cloud platforms, AI-powered insights, and seamless integration with marketing automation ecosystems.
- Market restraints include high implementation costs for advanced solutions, technical complexity in integrating deliverability tools with existing CRM systems, and the constant challenge of adapting to evolving global data privacy regulations.
- Regional growth patterns highlight North America’s leadership with its mature digital marketing ecosystem, Europe’s regulatory-driven adoption, Asia-Pacific’s rapid expansion due to e-commerce and SME digitalization, and steady growth in Latin America and Middle East & Africa.
- Long-term opportunities exist in targeting SMEs and emerging markets with affordable, user-friendly, and cloud-based solutions that simplify compliance and deliver actionable insights for effective campaign management.
Market Drivers
Rising Dependence on Digital Marketing and Customer Engagement
The Email Deliverability Tools Market expands with the growing reliance of businesses on digital marketing to engage customers and generate revenue. Companies across industries deploy email as a primary communication channel to drive conversions and strengthen brand loyalty. It creates a strong need for advanced deliverability tools that ensure messages reach customer inboxes rather than spam folders. Rising e-commerce adoption, increased online transactions, and subscription-based services amplify this demand. Organizations focus on customer retention strategies supported by personalized and targeted campaigns. This driver reinforces email deliverability tools as critical enablers of modern marketing performance.
- For instance, Constant Contact reported sending over 7 billion emails in November 2024 for SMEs globally, with deliverability optimization features improving open rates by 18% across e-commerce campaigns.
Stricter Data Privacy and Compliance Requirements
Global regulations such as GDPR, CCPA, and CAN-SPAM Act drive organizations to prioritize email authenticity and compliance. The Email Deliverability Tools Market gains momentum from these frameworks, as companies seek solutions to safeguard sender reputation and avoid legal penalties. It compels enterprises to integrate advanced authentication protocols like SPF, DKIM, and DMARC within their systems. Compliance monitoring features in deliverability tools help organizations meet evolving regulatory standards across regions. Businesses adopt these tools to reduce risk and maintain trust with recipients. The regulatory environment continues to accelerate investment in reliable deliverability platforms.
- For instance, Amazon SES processed more than 35 billion emails in Q2 2025 with full DMARC enforcement, helping enterprise clients reduce phishing-related spoofing incidents by 22% year-over-year.
Growth in Email Volumes Across Industries
The exponential increase in email volumes across e-commerce, BFSI, healthcare, and media drives adoption of deliverability tools. The Email Deliverability Tools Market benefits from this surge, as enterprises require real-time monitoring of inbox placement and delivery performance. It ensures that high volumes of promotional and transactional emails achieve intended reach and engagement. Businesses rely on automation to manage campaigns effectively, creating demand for scalable deliverability platforms. Rising mobile usage further amplifies the need to optimize email performance across devices. This driver cements deliverability tools as a core part of enterprise communication strategies.
Rising Adoption of AI and Analytics in Campaign Optimization
Artificial intelligence and advanced analytics play a critical role in shaping the Email Deliverability Tools Market. AI-enabled solutions predict inbox placement, monitor bounce rates, and optimize sending times to enhance engagement. It empowers organizations to refine campaign strategies through actionable insights and predictive modeling. Machine learning algorithms improve reputation management by analyzing user behavior and feedback loops. Companies leverage these capabilities to improve ROI from email campaigns and strengthen long-term customer relationships. The growing integration of AI ensures continuous innovation in deliverability platforms, driving competitive advantage across industries.
Market Trends
Increasing Integration with Marketing Automation Platforms
The Email Deliverability Tools Market evolves through integration with leading marketing automation and CRM platforms. Businesses demand seamless workflows that connect deliverability insights with campaign management systems. It enables organizations to optimize targeting, improve personalization, and ensure consistent inbox placement. Vendors expand APIs and plug-ins that allow easy integration into platforms like HubSpot, Salesforce, and Marketo. This trend improves operational efficiency and enhances the value proposition for enterprises. It reflects the convergence of deliverability tools with broader digital marketing ecosystems.
- For instance, Mailgun’s Optimize feature, available through Salesforce integrations, enables email validation that lowers bounce rates by 21% and raises open rates by 65% for clients who validate addresses via its API
Growing Role of AI and Predictive Analytics
Artificial intelligence reshapes the Email Deliverability Tools Market with predictive analytics and automated optimization features. AI models identify sending patterns, analyze recipient behavior, and forecast inbox placement outcomes. It supports real-time decision-making, such as adjusting send times or modifying content for better engagement. Vendors incorporate machine learning to detect anomalies and protect sender reputation. Predictive scoring of campaigns ensures higher effectiveness across industries. This trend accelerates adoption of intelligent deliverability solutions tailored to evolving customer expectations.
- For instance, SparkPost offers a “Health Score” that ranges from 0 to 100-senders with at least 1,000 daily emails and open tracking enabled receive scores above 80 for healthy performance.
Rising Emphasis on Security and Authentication Protocols
The increasing sophistication of phishing attacks and spam drives stronger focus on authentication within the Email Deliverability Tools Market. Enterprises adopt advanced protocols like DMARC, BIMI, and MTA-STS to protect sender identity and ensure brand trust. It strengthens email ecosystems by reducing the risk of fraudulent activity. Vendors enhance toolkits with real-time monitoring of authentication status and compliance checks. Security features align with global regulations and rising consumer demand for transparency. This trend positions deliverability tools as both marketing enablers and cybersecurity assets.
Expansion of Cloud-Based and Scalable Platforms
Cloud-based deployment dominates growth in the Email Deliverability Tools Market, supported by demand for scalability and cost efficiency. Enterprises adopt SaaS-based models that allow flexible capacity management during high-volume campaigns. It provides businesses with global accessibility, simplified upgrades, and lower infrastructure costs. Vendors expand offerings with real-time dashboards and advanced analytics powered by cloud platforms. Growing SME adoption highlights the value of subscription-based, scalable services. This trend reinforces cloud architecture as the foundation for future deliverability innovation.
Market Challenges Analysis
High Complexity of Evolving Regulations and Standards
The Email Deliverability Tools Market faces challenges from the constantly evolving landscape of data privacy and compliance regulations. Enterprises must adhere to frameworks such as GDPR, CCPA, and CAN-SPAM while also keeping up with emerging authentication protocols like DMARC and BIMI. It creates complexity for organizations that operate across multiple regions with varying compliance requirements. Vendors are pressured to continuously update their tools to ensure customers remain compliant, which increases development costs. Smaller businesses often struggle to implement these standards due to limited technical expertise. This challenge raises barriers to adoption for some market segments.
Rising Costs and Technical Barriers to Implementation
The adoption of advanced deliverability solutions requires significant investment in infrastructure, integration, and technical expertise. The Email Deliverability Tools Market faces hurdles where organizations, particularly SMEs, find the cost of premium platforms restrictive. It also demands skilled personnel to interpret deliverability data, manage reputation scores, and optimize campaigns effectively. The complexity of integrating tools into existing CRM and marketing automation systems further slows deployment. Vendors must address these barriers through simplified platforms and affordable pricing models. Without overcoming these constraints, adoption in smaller enterprises may remain limited despite overall market growth potential.
Market Opportunities
Expansion Through AI-Driven Personalization and Analytics
The Email Deliverability Tools Market creates opportunities through deeper integration of artificial intelligence and predictive analytics. AI-driven tools can analyze vast volumes of engagement data to predict inbox placement and optimize campaign timing. It allows enterprises to personalize emails at scale while protecting sender reputation. Predictive models enhance decision-making by identifying high-value recipients and minimizing bounce rates. Vendors that invest in machine learning algorithms position themselves as strategic partners for organizations seeking measurable ROI from email campaigns. The growing demand for actionable insights opens a clear path for innovation and differentiation.
Rising Adoption Across SMEs and Emerging Markets
Small and medium enterprises, along with companies in emerging economies, represent a major growth opportunity for the Email Deliverability Tools Market. Many of these businesses increase their reliance on digital communication but lack the expertise to manage deliverability challenges effectively. It creates strong demand for cost-efficient, user-friendly platforms that provide automated compliance checks and real-time monitoring. Cloud-based and subscription models make these tools more accessible to SMEs with limited budgets. Emerging markets in Asia-Pacific, Latin America, and Africa show rising digital adoption, expanding the potential customer base. Vendors that target these regions with tailored offerings can secure long-term market presence.
Market Segmentation Analysis:
By Deployment Type
The Email Deliverability Tools Market is segmented into cloud-based and on-premises solutions. Cloud-based deployment leads adoption due to its scalability, cost efficiency, and accessibility for businesses of all sizes. It enables enterprises to manage high-volume campaigns with real-time analytics and seamless updates. Subscription-based SaaS models appeal strongly to SMEs, offering flexibility without heavy infrastructure costs. On-premises deployment continues to serve organizations with stringent data security and compliance requirements, particularly in BFSI and healthcare sectors. Vendors offering hybrid options cater to enterprises that require both flexibility and control, expanding adoption across diverse industries.
- For instance, Mailgun hosts more than 450 billion sent emails annually through its cloud infrastructure and uses its Optimize suite to enable Inbox Placement testing and blocklist monitoring via APIs without requiring on-site deployment
By Features
Feature segmentation highlights critical functions that drive adoption, including inbox placement monitoring, email authentication, blacklist tracking, spam filter testing, and advanced analytics. The Email Deliverability Tools Market benefits from rising demand for authentication support such as SPF, DKIM, and DMARC protocols to maintain sender reputation. It also leverages predictive analytics that optimize send times and improve engagement. Real-time blacklist monitoring protects against reputational risks, while spam filter testing ensures campaign visibility across multiple email clients. Vendors differentiate themselves by integrating AI-driven dashboards and automation capabilities. This segment reflects the growing priority of accuracy, compliance, and actionable insights in deliverability management.
- For instance, SparkPost’s Deliverability Analytics provides comprehensive inbox and spam rates, unlimited inline seeding, blocklist alerting, and competitor benchmarking, leveraging its delivery of nearly five trillion commercial emails annually to power analytics and remediation workflows
By End User
End-user segmentation underscores adoption across e-commerce, BFSI, media and entertainment, healthcare, and SMEs. The Email Deliverability Tools Market finds strong traction in e-commerce, where businesses rely heavily on promotional and transactional emails to drive revenue. BFSI institutions prioritize deliverability for critical communication such as account alerts and policy updates, making reliability a key requirement. Media and entertainment companies leverage these tools to optimize subscriber engagement and minimize churn. Healthcare organizations adopt deliverability solutions to ensure timely communication of sensitive information within regulatory frameworks. SMEs across industries turn to cost-effective and automated platforms to improve customer reach, highlighting broad applicability across market tiers.
Segments:
Based on Deployment Type
- Cloud-Based
- On-Premises
Based on Features
- Email Verification
- Spam Testing
- Analytics and Reporting
- Deliverability Tracking
Based on End User
- Small and Medium Enterprises
- Large Enterprises
- Marketing Agencies
Based on Industry Vertical
- Retail
- Finance
- Healthcare
- Education
- Travel
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for 36% of the Email Deliverability Tools Market, driven by the region’s advanced digital marketing ecosystem and high adoption of SaaS-based solutions. The United States leads demand as enterprises rely heavily on email marketing for customer acquisition and retention. It benefits from widespread adoption of compliance frameworks such as CAN-SPAM and strong investments in marketing automation platforms that integrate deliverability tools. Canada adds momentum with rising adoption among SMEs that expand their online presence across retail, BFSI, and healthcare. The strong presence of vendors like Validity, SparkPost, and Twilio SendGrid strengthens competition and accelerates innovation. Continuous investment in AI-enabled analytics and inbox placement monitoring reinforces North America’s leadership position in the global market.
Europe
Europe represents 27% of the Email Deliverability Tools Market, supported by strict regulatory enforcement and high internet penetration rates. The introduction of GDPR reshaped marketing practices across the region, making compliance monitoring and authentication critical for enterprises. It benefits from adoption among industries such as BFSI, e-commerce, and media, where reliable communication with customers remains a priority. Countries such as Germany, the UK, and France lead adoption, supported by strong enterprise digitalization and advanced marketing strategies. European vendors emphasize integration with DMARC, BIMI, and data security features to align with compliance-focused buyers. Rising adoption of AI-based optimization tools in Scandinavia and Western Europe underscores a trend toward intelligent automation in deliverability platforms.
Asia-Pacific
Asia-Pacific holds 23% of the Email Deliverability Tools Market, emerging as the fastest-growing region due to rapid digital transformation and e-commerce expansion. China, India, Japan, and South Korea drive significant demand as businesses scale online marketing to reach growing digital populations. It gains momentum from SMEs that adopt cost-effective cloud-based deliverability solutions to enhance customer engagement. Government initiatives supporting digitalization and mobile-first strategies fuel adoption across emerging economies. Regional enterprises invest in AI-driven campaign optimization and authentication protocols to compete globally. Vendors targeting Asia-Pacific capitalize on the region’s demand for scalable and affordable platforms, making it a critical growth engine for the global market.
Latin America
Latin America contributes 8% of the Email Deliverability Tools Market, with Brazil and Mexico at the forefront of adoption. Expanding e-commerce platforms and mobile-based marketing strategies create strong opportunities for deliverability solutions. It faces challenges in data privacy enforcement, yet rising consumer awareness about secure and transparent communication fuels adoption. Enterprises in retail, banking, and media sectors lead implementation of inbox monitoring and compliance tools to strengthen customer trust. Vendors expand cloud-based offerings to meet growing SME demand, making affordability and accessibility key differentiators in this region. Despite its smaller share, Latin America shows steady adoption momentum and expanding opportunities for global providers.
Middle East & Africa
The Middle East & Africa region holds 6% of the Email Deliverability Tools Market, characterized by gradual adoption of advanced digital marketing solutions. Gulf countries such as the UAE and Saudi Arabia lead growth, driven by strong investments in e-commerce and digital transformation initiatives. It benefits from increasing adoption of compliance-oriented deliverability solutions by BFSI and telecom sectors. South Africa contributes with growing adoption in retail and healthcare, where communication reliability is critical. Limited awareness and budget constraints in some African countries restrain faster adoption, but expanding internet penetration supports gradual growth. Vendors focusing on localized solutions and strategic partnerships with regional enterprises gain a competitive advantage in this market.
Key Player Analysis
- GetResponse
- Amazon SES
- Postmark
- SendGrid
- AWeber
- SparkPost
- Constant Contact
- Mailgun
- Pardot
- Sendinblue
Competitive Analysis
The Email Deliverability Tools Market is highly competitive, with leading players including Mailgun, Sendinblue, AWeber, SparkPost, Pardot, SendGrid (Twilio), Postmark, GetResponse, Amazon SES, and Constant Contact driving innovation and adoption worldwide. These companies focus on improving inbox placement rates, enhancing authentication protocols, and providing real-time analytics to help enterprises optimize campaign performance. SendGrid and Amazon SES dominate with scalable cloud-based infrastructures that serve high-volume enterprise clients, while Mailgun and SparkPost differentiate through advanced APIs, predictive deliverability scoring, and strong integration capabilities. Constant Contact, AWeber, and GetResponse target SMEs with affordable, user-friendly platforms that combine deliverability monitoring with broader email marketing functionalities. Sendinblue and Pardot emphasize automation and personalization, strengthening their appeal among businesses seeking all-in-one marketing solutions. Postmark focuses on reliable transactional email delivery with strict authentication and fast response times, carving a niche in developer-driven markets. The competitive landscape is marked by rising investments in AI-driven analytics, real-time blacklist tracking, and seamless integration with CRM and marketing automation ecosystems. Vendors that balance scalability, compliance, and affordability while addressing emerging security and regulatory demands are best positioned to strengthen their market presence and secure long-term growth.
Recent Developments
- In August 2025, Amazon SES added a tenant management feature to isolate and manage sending reputations for multiple downstream entities on a single account.
- In July 2025, GetResponse introduced the option for enterprise-tier plans to host customer data exclusively within the EU, addressing data residency and privacy concerns.
- In June 2025, AWS launched a partnership between Amazon SES and Valimail to offer enhanced email authentication and deliverability capabilities-helping senders comply with Microsoft’s new requirements.
Market Concentration & Characteristics
The Email Deliverability Tools Market reflects moderate concentration, with a mix of established global providers and niche players competing across enterprise and SME segments. Leading vendors such as Mailgun, SendGrid, SparkPost, Amazon SES, and Constant Contact maintain strong positions through scalable cloud platforms, API-driven integrations, and advanced analytics capabilities. It is characterized by rapid innovation in AI-driven deliverability scoring, predictive monitoring, and real-time authentication to align with evolving compliance standards. Smaller players strengthen competition by targeting specific needs such as transactional email reliability, simplified compliance, or affordable solutions for SMEs. The market demonstrates resilience through rising email volumes, regulatory enforcement, and growing demand for secure, personalized, and efficient digital communication. It continues to evolve as vendors balance scalability, affordability, and advanced features, creating a dynamic environment where differentiation is driven by innovation, reliability, and integration with broader marketing ecosystems.
Report Coverage
The research report offers an in-depth analysis based on Deployment Type, Features, End User, Industry Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption will increase with the rise of global email volumes across industries.
- Vendors will integrate more AI-driven analytics to predict inbox placement and optimize campaigns.
- Cloud-based platforms will dominate as enterprises and SMEs seek scalability and flexibility.
- Compliance-focused features will expand to meet evolving regulations such as GDPR and DMARC mandates.
- Demand from SMEs will grow as affordable and automated solutions become widely available.
- Security and authentication protocols will strengthen to counter phishing and spam threats.
- Integration with CRM and marketing automation ecosystems will become a key differentiator.
- Vendors will expand into emerging markets where digital adoption and e-commerce growth accelerate demand.
- Personalization and real-time optimization will drive higher investment in advanced deliverability solutions.
- Competition will intensify as global leaders and regional players innovate to balance performance and affordability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Dependence on Digital Marketing and Customer Engagement
As businesses increasingly rely on digital marketing to reach and retain customers, the need for advanced email deliverability tools grows to ensure messages land in inboxes and not spam folders. This is especially critical for industries like e-commerce and subscription services where email is a primary communication channel.
Stricter Data Privacy and Compliance Requirements
Global regulations such as GDPR, CCPA, and CAN-SPAM are compelling organizations to adopt deliverability tools that support advanced authentication and compliance monitoring, helping them avoid legal penalties and maintain sender reputation.
Growth in Email Volumes Across Industries
The exponential rise in email traffic across sectors like e-commerce, BFSI, and healthcare drives demand for scalable deliverability solutions that can monitor inbox placement and optimize delivery performance for both promotional and transactional emails.
Rising Adoption of AI and Analytics in Campaign Optimization
AI-powered deliverability tools enable predictive inbox placement, bounce rate monitoring, and optimized send times, allowing organizations to refine campaigns and improve ROI through actionable insights and machine learning-driven reputation management.
Expansion of Cloud-Based and Scalable Platforms
The shift toward cloud-based SaaS models allows businesses of all sizes to access scalable, cost-efficient deliverability solutions, supporting high-volume campaigns and real-time analytics without heavy infrastructure investments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Email Deliverability Tools, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Email Deliverability Tools market projected to grow between 2025 and 2032?
Which Email Deliverability Tools market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Email Deliverability Tools market?
Who are the leading companies in the Email Deliverability Tools market?
Which region commanded the largest share of the Email Deliverability Tools market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Small and Medium Enterprises
- 1.2.2 Large Enterprises
- 1.2.3 Marketing Agencies
- 1.3 By Features
- 1.3.1 Email Verification
- 1.3.2 Spam Testing
- 1.3.3 Analytics and Reporting
- 1.3.4 Deliverability Tracking
- 1.4 By Deployment Type
- 1.4.1 Cloud-Based
- 1.4.2 On-Premises
- 1.5 By Industry Vertical
- 1.5.1 Retail
- 1.5.2 Finance
- 1.5.3 Healthcare
- 1.5.4 Education
- 1.5.5 Travel
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 444.6 million → 2032: USD 988.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Email Deliverability Tools Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Email Deliverability Tools Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Email Deliverability Tools Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Email Deliverability Tools Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Email Deliverability Tools Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Email Deliverability Tools Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Email Deliverability Tools Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Email Deliverability Tools Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 444.6 million → 2032: USD 988.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Email Deliverability Tools Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small and Medium Enterprises
- 12.3.7.2 Large Enterprises
- 12.3.7.3 Marketing Agencies
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Features - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Email Verification
- 12.4.7.2 Spam Testing
- 12.4.7.3 Analytics and Reporting
- 12.4.7.4 Deliverability Tracking
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cloud-Based
- 12.5.7.2 On-Premises
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Retail
- 12.6.7.2 Finance
- 12.6.7.3 Healthcare
- 12.6.7.4 Education
- 12.6.7.5 Travel
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Email Deliverability Tools End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Email Deliverability Tools Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Email Deliverability Tools Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Email Deliverability Tools Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SendGrid (Twilio)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mailgun
- 18.4 SparkPost
- 18.5 Amazon SES
- 18.6 Constant Contact
- 18.7 GetResponse
- 18.8 Postmark
- 18.9 AWeber
- 18.10 Pardot
- 18.11 Sendinblue
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

