
Market Overview:
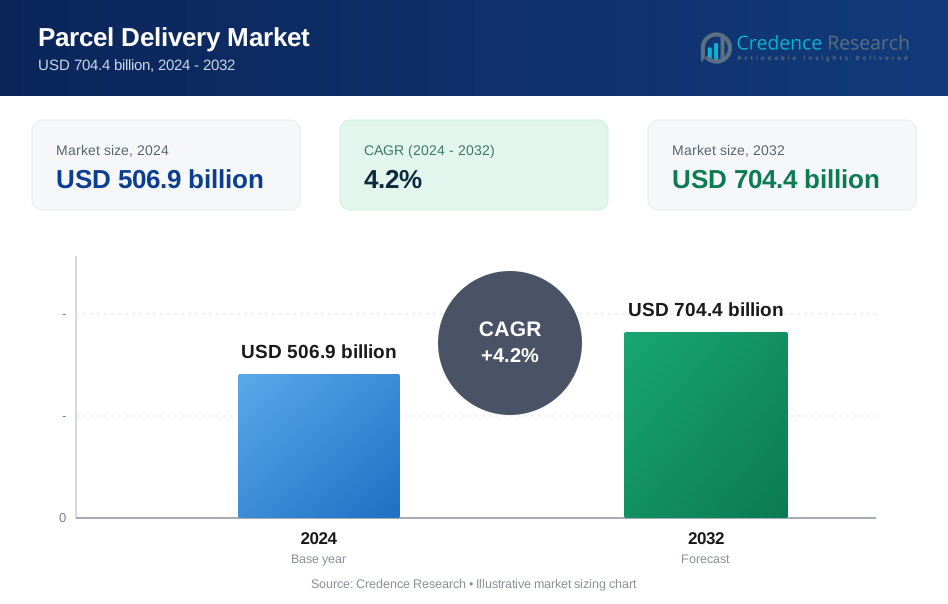
The Parcel delivery market is projected to grow from USD 506.9 billion in 2024 to an estimated USD 704.4 billion by 2032, at a CAGR of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Parcel Delivery Market Size 2024 | USD 506.9 billion |
| Parcel Delivery Market, CAGR | 4.2% |
| Parcel Delivery Market Size 2032 | USD 704.4 billion |
The market is driven by the rapid expansion of online retail, greater consumer preference for fast and flexible deliveries, and the rise of omnichannel retail strategies. Companies are actively improving last-mile delivery through digital platforms, route optimization, and partnerships with third-party logistics providers. Growing urbanization and the rising number of SMEs using parcel services further fuel adoption, while environmental pressures push players toward green logistics and electric vehicle fleets.
Regionally, North America and Europe hold leading positions due to advanced logistics infrastructure, high e-commerce adoption, and consumer preference for premium delivery services. Asia-Pacific is emerging as the fastest-growing region, driven by rapid digitalization, booming online shopping in China and India, and government-backed smart logistics initiatives. Latin America and the Middle East & Africa show promising potential, with growing internet penetration and rising cross-border trade, though infrastructure gaps remain a challenge compared to mature markets.

Market Insights:
- The parcel delivery market was valued at USD 506.9 billion in 2024 and is projected to reach USD 704.4 billion by 2032, growing at a CAGR of 2% during the forecast period.
- Strong growth is driven by the rapid expansion of e-commerce, increasing consumer expectations for same-day and next-day delivery, and greater reliance on digital shopping channels.
- Technological advancements, including AI, automation, and route optimization systems, enhance delivery speed and efficiency, strengthening competitiveness in the sector.
- Rising operational costs, infrastructure limitations, and last-mile delivery inefficiencies create restraints, especially in congested urban and remote rural areas.
- Sustainability pressures and regulatory compliance requirements around emissions and labor standards further challenge profitability for logistics providers.
- North America and Europe dominate due to advanced logistics infrastructure, mature e-commerce ecosystems, and high consumer demand for premium services.
- Asia-Pacific is anticipated to record the fastest growth, fueled by booming online retail in China and India, increasing digital adoption, and government-backed logistics modernization.
Market Drivers:
Rising Expansion of E-Commerce and Growing Customer Expectations for Fast and Reliable Deliveries:
The parcel delivery market benefits significantly from the continuous expansion of global e-commerce, where rising internet penetration and smartphone adoption fuel online retail transactions. Consumers increasingly demand shorter delivery times, pushing logistics providers to enhance efficiency and invest in advanced route optimization technologies. It is also influenced by the growth of small and medium-sized enterprises relying on digital platforms for global reach. Same-day and next-day delivery options are no longer premium services but expected standards, creating pressure on logistics networks. Retailers and delivery providers are forming strategic partnerships to streamline last-mile operations. Automation and robotics are being deployed in sorting and warehousing facilities to improve scalability. It is adapting by expanding networks to support cross-border deliveries. Growing consumer confidence in digital shopping ensures that parcel volumes will continue to rise across diverse categories.
- For instance, Amazon enhanced its delivery network to cover over 4,000 smaller towns and rural areas in the U.S., boosting its same-day and next-day delivery reach significantly by mid-2025.
Increasing Adoption of Technological Solutions to Enhance Operational Efficiency and Service Quality:
The parcel delivery market is driven by the integration of artificial intelligence, big data analytics, and Internet of Things solutions that optimize logistics processes. Companies are using predictive analytics to forecast parcel volumes, reduce delays, and minimize costs. Smart lockers and digital platforms are improving delivery convenience for consumers. It is also influenced by automation in warehouses, which reduces labor dependency and increases accuracy. Drone-based deliveries and autonomous vehicles are gaining traction in urban centers where congestion limits traditional options. Blockchain technologies are being explored for enhancing transparency and tracking. It is becoming increasingly dependent on digital ecosystems that improve speed and reliability. Companies leveraging these solutions achieve competitive advantages in an industry where efficiency directly impacts profitability.
- For instance, FedEx expanded its collaboration with Pick Network to offer over 1,000 smart locker drop-off points island-wide in Singapore, harnessing digital infrastructure for last-mile efficiency.
Growing Cross-Border Trade and Increasing Globalization of Supply Chains Driving Higher Parcel Volumes:
The parcel delivery market is strengthened by expanding cross-border trade, with consumers and businesses engaging more in international e-commerce transactions. Retailers now focus on global audiences, requiring logistics providers to expand capabilities for international shipping. It is also impacted by rising free trade agreements that encourage greater flow of goods across borders. Cross-border deliveries demand strong customs clearance systems, which have become critical investment areas. Advanced tracking solutions provide customers with visibility over international parcels, improving trust. Partnerships between regional and global logistics providers ensure better network integration. It is expected to experience steady growth in this segment as cross-border shopping becomes more mainstream. Emerging markets are driving much of this growth, with rising middle-class populations seeking access to international brands.
Rising Consumer Preference for Sustainable Deliveries and Eco-Friendly Logistics Operations:
The parcel delivery market is being shaped by rising demand for sustainable logistics solutions as consumers and regulators push for lower emissions. Logistics companies are increasingly investing in electric vehicle fleets and alternative fuels to meet sustainability goals. It is also experiencing growth in demand for carbon-neutral delivery options, which appeal to environmentally conscious buyers. Companies are redesigning packaging strategies to reduce waste and align with circular economy practices. Green warehouses powered by renewable energy sources are being integrated into networks. Sustainability commitments are now key differentiators in an industry with growing environmental scrutiny. It is adapting by integrating eco-friendly initiatives into corporate strategies. Meeting these demands not only reduces environmental impact but also strengthens brand reputation among a competitive consumer base.
Market Trends:
Integration of Smart Delivery Infrastructure and Urban Logistics Innovations in Growing Cities:
The parcel delivery market is witnessing the rise of smart delivery infrastructure such as automated parcel lockers and micro-fulfillment centers. Companies are responding to urban congestion by introducing bicycle couriers, electric vans, and last-mile delivery robots. It is increasingly adapting to urbanization where dense populations require efficient parcel movement. The demand for contactless delivery services has become more prominent, accelerated by health-conscious consumer behavior. Cities are partnering with logistics providers to design smarter last-mile systems. Delivery networks are optimizing through AI-based traffic management tools. It is evolving toward sustainable city logistics where speed and environmental performance align. These changes create more resilient supply chains in fast-growing metropolitan regions.
- For instance, DHL merged its UK eCommerce unit with Evri in 2025 to consolidate parcel locker networks and scaled contactless delivery solutions addressing urban congestion and consumer demand.
Emergence of Omni-Channel Retail Strategies and Hybrid Delivery Models in Retail Supply Chains:
The parcel delivery market is adapting to omni-channel retail where customers expect seamless integration of online and offline experiences. Retailers now provide options for curbside pickup, in-store collection, and direct-to-home delivery. It is increasingly influenced by hybrid models that reduce pressure on last-mile delivery. Integration of inventory management systems ensures real-time tracking and flexibility. Retailers rely on logistics providers to support a variety of distribution models. It is benefiting from rising investment in retail logistics technology. These models also reduce operational costs while enhancing consumer satisfaction. The growing use of such strategies marks a long-term trend across retail and logistics sectors.
- For instance, UPS’s acquisition of Estafeta has enhanced its ability to support hybrid delivery models in Mexico, offering diversified last-mile options tied to omni-channel retail demands.
Increasing Role of Artificial Intelligence and Automation in Delivery Fleet Optimization and Route Planning:
The parcel delivery market is undergoing transformation through advanced use of artificial intelligence in fleet management and route planning. Predictive algorithms help companies manage delivery peaks effectively. It is also being influenced by rising investments in autonomous vehicles for pilot delivery programs. Robotics in sorting facilities reduces human error and boosts throughput. Artificial intelligence ensures better fuel optimization and reduced operational expenses. Companies are experimenting with dynamic rerouting technologies to overcome traffic disruptions. It is increasingly investing in machine learning platforms that adapt in real time. This trend is shaping efficiency gains and creating scalable delivery networks.
Expansion of Subscription-Based Delivery Services and Growing Consumer Loyalty to Fast Shipping Options:
The parcel delivery market is seeing rapid expansion in subscription-based services offered by e-commerce giants and logistics providers. Consumers subscribe for benefits like free shipping, faster deliveries, and exclusive deals. It is reinforcing customer loyalty by linking delivery services with retail memberships. Companies are scaling loyalty-driven logistics programs to retain repeat customers. Subscriptions are boosting parcel volumes across retail categories. It is also enhancing revenue predictability for providers. Delivery performance is becoming a strategic element of customer retention. This trend highlights the increasing role of delivery speed in shaping consumer choices.
Market Challenges Analysis:
Rising Infrastructure Limitations and Last-Mile Delivery Inefficiencies Creating Cost Pressures:
The parcel delivery market faces persistent challenges due to last-mile inefficiencies that account for a large share of delivery costs. Urban congestion, traffic restrictions, and high fuel prices add complexity. It struggles with balancing speed, accuracy, and cost-effectiveness in dense urban areas. Rural areas also present difficulties due to limited infrastructure and longer delivery routes. Companies face growing operational expenses as they expand networks to meet demand. It is further constrained by capacity shortages during peak seasons. Labor shortages among delivery personnel add to cost pressures. These challenges force logistics providers to invest heavily in technology and infrastructure upgrades.
Increasing Competitive Pressure and Regulatory Constraints Impacting Growth Prospects:
The parcel delivery market is facing heightened competition as traditional postal operators, courier services, and new entrants fight for market share. It must adapt to regulatory frameworks focused on labor laws, data protection, and environmental sustainability. Compliance costs are rising with governments imposing stricter delivery timelines and emissions regulations. Smaller logistics players find it difficult to match investments in technology and infrastructure made by global leaders. It is further challenged by fluctuating trade policies that impact cross-border deliveries. Intense competition creates price wars, reducing profit margins. Companies must differentiate through customer service and technological innovation. The market’s long-term growth depends on balancing compliance with competitiveness.
Market Opportunities:
Expanding Potential in Emerging Markets with Rising E-Commerce Penetration and Logistics Investments:
The parcel delivery market is expected to witness strong opportunities in emerging regions where internet penetration and online shopping are accelerating. Countries in Asia-Pacific, Latin America, and Africa are experiencing rising consumer demand for global and local e-commerce. It is supported by governments investing in smart logistics infrastructure and digital trade facilitation. Local partnerships are strengthening networks to reach underserved markets. Cross-border shopping trends are also creating higher parcel volumes. Companies expanding into these regions secure first-mover advantages. It is positioned to benefit from rising middle-class populations with growing purchasing power. These regions represent untapped growth potential for global logistics providers.
Opportunities Through Green Logistics and Technological Innovation in Sustainable Delivery Practices:
The parcel delivery market has significant opportunities through the shift toward sustainable and technologically advanced logistics solutions. Electric vehicles, renewable-powered warehouses, and recyclable packaging are becoming investment priorities. It is also creating prospects for drone-based and autonomous vehicle deliveries in urban environments. Consumers increasingly value eco-friendly delivery options, giving companies room for differentiation. Partnerships between logistics providers and technology firms are accelerating these initiatives. It is aligning profitability with sustainability objectives. Companies that prioritize innovation in green logistics strengthen both reputation and competitive edge. These opportunities define the next phase of industry growth across developed and emerging markets.
Market Segmentation Analysis:
By Business Type
The parcel delivery market is segmented into B2B, B2C, and C2C, with B2C holding the largest share due to the rapid expansion of e-commerce platforms and direct-to-consumer distribution. B2B remains critical for wholesale and industrial shipments that require bulk logistics efficiency. C2C is expanding with the popularity of resale platforms and second-hand product marketplaces that depend on reliable courier services.
- For instance, Aramex has leveraged AI partnerships to optimize B2C last-mile delivery in real-time, improving service reliability for rapidly growing consumer segments in the Middle East.
By Delivery Mode
Ground freight dominates the market, supported by its affordability and extensive use in domestic shipping. Air freight is increasing in relevance for time-sensitive and high-value goods that require fast delivery. Sea freight remains essential for bulk cross-border trade. Rail freight is growing in regions with developed infrastructure, offering a cost-effective and environmentally sustainable option for long-haul transportation.
- For instance, SF Express adjusted service hours and optimized operational capacity during peak periods like Chinese New Year 2025 to maintain ground and air freight consistency for time-sensitive deliveries.
By Destination
Domestic delivery leads the segment, driven by consumer demand for fast and affordable fulfillment within national boundaries. International delivery is growing steadily with rising cross-border e-commerce and globalization of supply chains. It requires robust customs clearance, regulatory compliance, and advanced tracking systems to ensure efficiency and reliability.
By Delivery Type
Express delivery is expanding quickly, supported by customer preference for speed and convenience. Standard courier services remain widely adopted for cost efficiency. Other models such as same-day, next-day, and scheduled deliveries are becoming increasingly popular in urban centers, aligning with changing consumer lifestyles.
By Industry Served
Key industries include consumer packaged goods, fashion and apparel, and telecom and electronics, which generate high parcel volumes. Pharmaceuticals and food and beverage are expanding due to demand for temperature-controlled and time-sensitive logistics. Automotive and other industrial sectors maintain consistent reliance on dependable delivery networks. It serves diverse verticals, reinforcing its role in global commerce.
Segmentation:
By Business Type
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Consumer-to-Consumer (C2C)
By Delivery Mode
- Ground Freight
- Air Freight
- Sea Freight
- Rail Freight
By Destination
- Domestic
- International
By Delivery Type
- Express Delivery
- Standard Courier Services
- Others (same-day delivery, next-day delivery, scheduled delivery, etc.)
By Industry Served
- Consumer Packaged Goods
- Telecom and Electronics
- Fashion and Apparel
- Food and Beverage
- Automotive
- Pharmaceutical
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America and Europe
North America holds a significant share of the parcel delivery market, accounting for nearly 30% of the global market. Strong e-commerce adoption, advanced logistics infrastructure, and consumer demand for premium services drive growth in the region. The United States leads with well-established networks and investments in automation, while Canada strengthens cross-border trade connectivity. Europe contributes around 25%, supported by mature postal systems and regulatory frameworks that emphasize efficiency and sustainability. Major economies such as Germany, the U.K., and France are central hubs for cross-border e-commerce. It continues to benefit from digital platforms and investments in green logistics initiatives across these regions.
Asia-Pacific
Asia-Pacific represents the largest share at nearly 35%, driven by booming e-commerce growth and strong demand in countries such as China, India, and Japan. Expanding middle-class populations, digital adoption, and government-backed logistics modernization projects enhance market expansion. China dominates regional share due to its extensive courier network and high parcel volumes generated by domestic e-commerce giants. India is emerging rapidly with digital payment systems and rising retail penetration. Southeast Asian markets are also gaining traction with cross-border parcel flows and regional trade agreements. It is set to experience the fastest growth rate due to scale, demographics, and rising global integration.
Latin America and Middle East & Africa
Latin America holds close to 5% of the parcel delivery market, with Brazil and Mexico leading demand supported by expanding e-commerce penetration. Infrastructure challenges limit speed and cost efficiency, yet digital platforms are accelerating adoption. The Middle East & Africa collectively account for about 5%, with the Gulf Cooperation Council countries driving investments in logistics hubs. South Africa and Nigeria are emerging with rising online retail activities and improved payment systems. Market growth in these regions depends on logistics modernization and trade facilitation policies. It shows potential for expansion as global players collaborate with local couriers to build reliable and scalable networks.
Key Player Analysis:
- com Inc.
- United Parcel Service (UPS) Inc.
- Deutsche Post AG (DHL)
- FedEx Corporation
- Japan Post Holdings Co. Ltd.
- SF Express Co., Ltd.
- Aramex PJSC
- Bell and Howell LLC
- Cleveron AS
- KEBA AG
- ByBox Holdings Ltd.
- InPost S.A.
- J&T Express
- Jadlog S.A.
- Regional and national postal and courier companies
Competitive Analysis:
The parcel delivery market is highly competitive with global leaders such as Amazon, UPS, DHL, FedEx, and Japan Post dominating market share through extensive networks and technological investments. Regional players including SF Express, Aramex, and J&T Express strengthen local distribution by offering cost-efficient solutions. It is characterized by continuous innovation in last-mile delivery, integration of AI-driven route optimization, and adoption of sustainable logistics practices. Companies compete on service speed, network reach, and reliability while forming strategic alliances to expand global coverage and enhance efficiency.
Recent Developments:
- In June 2025, Amazon.com Inc. expanded its faster Prime delivery speeds to over 4,000 smaller cities, towns, and rural communities across the U.S., enhancing Same-Day and Next-Day delivery options for a wide selection of everyday essentials and groceries.
- In June 2025, FedEx Corporation expanded its collaboration with Pick Network in Singapore, enabling customers to drop off pre-labelled FedEx packages at over 1,000 smart lockers island-wide, enhancing convenience and flexibility for small to medium-sized shipments.
- In May 2025, Deutsche Post AG (DHL) merged its DHL eCommerce UK unit with Evri, creating a leading UK parcel delivery business that combines DHL's premium van delivery network with Evri's courier services, expanding international capabilities and the out-of-home parcel network.
- In April 2025, Aramex PJSC partnered with Shipsy to leverage AI-powered logistics solutions aimed at improving last-mile delivery efficiency and providing more accurate delivery windows for time-sensitive shipments, supporting a smarter, more agile supply chain in the Middle East.
Market Concentration & Characteristics:
The parcel delivery market demonstrates a moderately high level of concentration, with a few multinational companies holding significant global presence. It features strong competition from both established logistics firms and emerging regional players. It is marked by high capital investments, extensive infrastructure requirements, and growing reliance on digital technologies to manage large parcel volumes. Service differentiation through faster delivery, advanced tracking, and sustainability commitments defines market positioning.
Report Coverage:
The research report offers an in-depth analysis based on business type, delivery mode, destination, delivery type, industry served, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- E-commerce expansion will continue to drive strong parcel volumes worldwide.
- Technological innovations in AI, automation, and IoT will redefine delivery efficiency.
- Electric vehicles and green logistics will become core strategies for sustainability.
- Subscription-based and loyalty-driven delivery models will strengthen customer retention.
- Cross-border e-commerce will accelerate demand for integrated international networks.
- Urbanization will intensify demand for last-mile delivery solutions in metropolitan areas.
- Drone and autonomous vehicle delivery pilots will expand into mainstream operations.
- Strategic partnerships between logistics providers and retailers will increase.
- Emerging markets will offer strong growth potential for global and regional players.
- Customer expectations for faster, reliable, and transparent delivery will reshape service standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Parcel delivery market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Parcel delivery market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Parcel delivery market?
Who are the leading companies in the Parcel delivery market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Parcel Delivery Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Parcel Delivery Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 506.9 billion → 2032: USD 704.4 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Parcel Delivery Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Parcel Delivery Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Parcel Delivery Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Parcel Delivery Market Drivers
- 3.3 Parcel Delivery Market Restraints & Challenges
- 3.4 Parcel Delivery Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Parcel Delivery Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Parcel Delivery Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Parcel Delivery category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Parcel Delivery Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Parcel Delivery Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Parcel Delivery market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Parcel Delivery Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Parcel Delivery Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Parcel Delivery Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Parcel Delivery (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Parcel Delivery Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Parcel Delivery Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Parcel Delivery Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Parcel Delivery Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Parcel Delivery Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Parcel Delivery Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Parcel Delivery Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Parcel Delivery Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Parcel Delivery Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
