
Magnesium Market Overview:
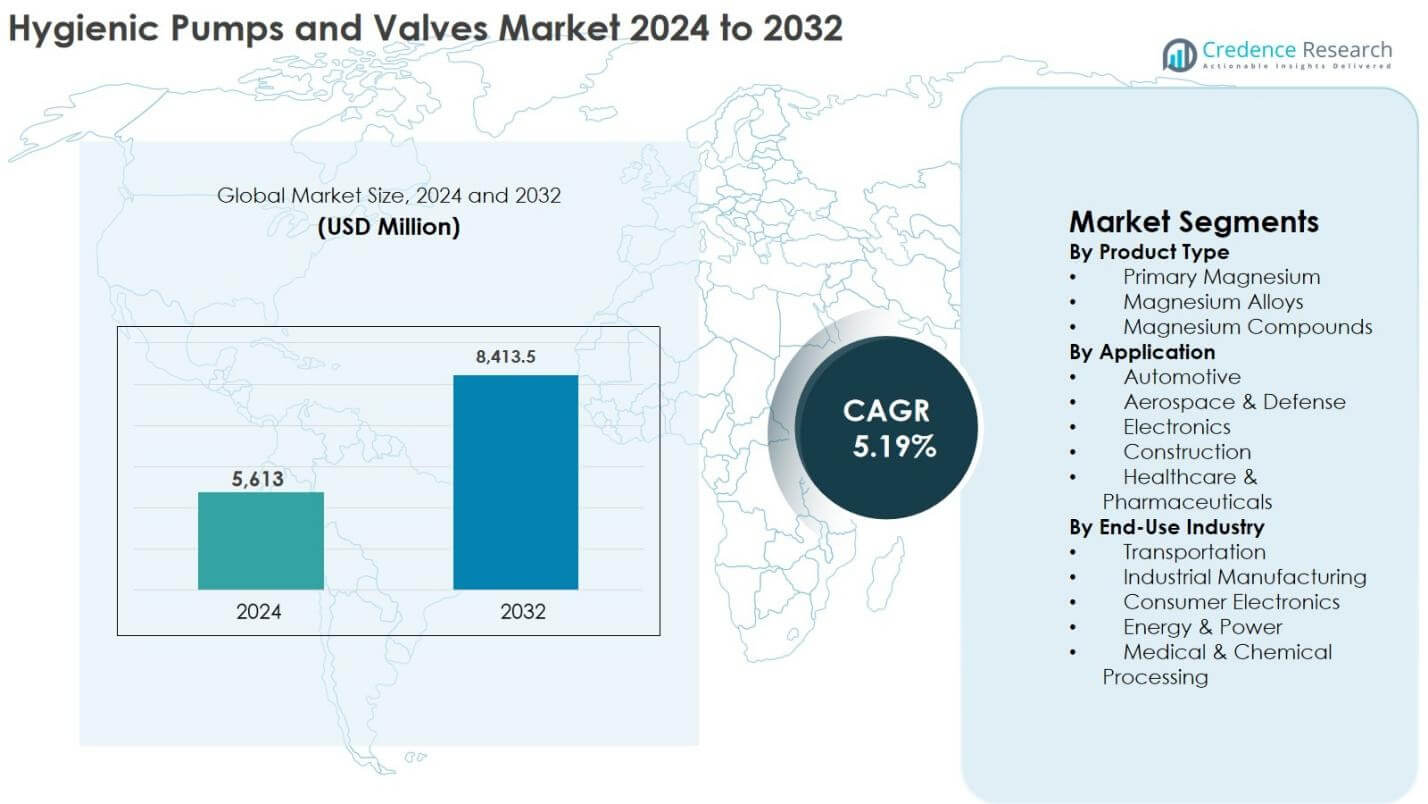
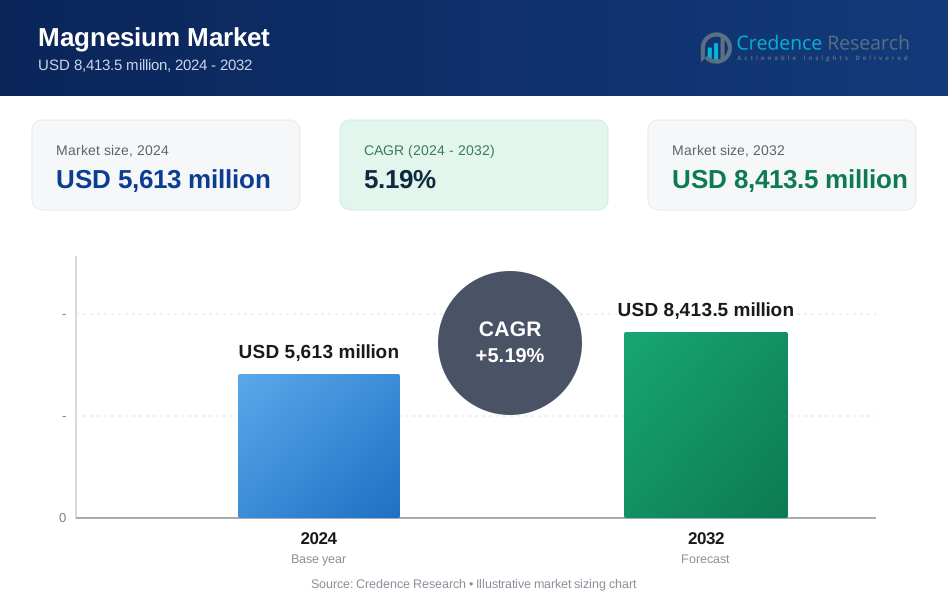
The Magnesium Market size was valued at USD 5,613 million in 2024 and is anticipated to reach USD 8,413.5 million by 2032, at a CAGR of 5.19% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Magnesium Market Size 2024 | USD 5,613 million |
| Magnesium Market, CAGR | 5.19% |
| Magnesium Market Size 2032 | USD 8,413.5 million |
Magnesium Market Insights
- Market growth is driven by lightweighting requirements in automotive and aerospace, with automotive accounting for 38.6% share in 2024 and magnesium alloys leading the product mix with a 8% segment share due to strength-to-weight and recyclability advantages.
- Key market trends include increasing use of magnesium alloys in electric vehicles, expanding electronics manufacturing, and growing focus on recycling-based magnesium production to reduce carbon intensity and improve supply sustainability.
- Market restraints include energy-intensive production processes, raw material price volatility, and environmental compliance costs, which impact profitability and capacity expansion, particularly for traditional primary magnesium producers.
- Regionally, Asia Pacific dominated with a 63.4% share in 2024, followed by North America at 15.2% and Europe at 13.6%, while transportation remained the largest end-use segment with a 2% share, ensuring stable long-term demand.
Magnesium Market Segmentation Analysis:
By Product Type:
The Magnesium Market by product type is led by magnesium alloys, which accounted for 46.8% market share in 2024, driven by their superior strength-to-weight ratio, corrosion resistance, and recyclability. Magnesium alloys are widely adopted across automotive, aerospace, and electronics applications to support lightweighting and fuel-efficiency targets. Primary magnesium followed with 32.4% share, supported by its use in alloy production and metallurgical processes, while magnesium compounds held 20.8% share, benefiting from steady demand in pharmaceuticals, chemicals, and flame-retardant applications.
- For instance, Magontec produces primary magnesium alloys like AZ91, suited for pressure casting, gravity die-casting, and sand casting in die-cast customer applications across Asia, Europe, and the Americas.
By Application:
By application, the automotive segment dominated the Magnesium Market with a 38.6% share in 2024, supported by rising adoption of lightweight materials to meet emission regulations and improve vehicle efficiency. Magnesium components are increasingly used in structural parts, powertrain systems, and interior components. Aerospace & defense accounted for 21.3% share, driven by demand for high-performance lightweight materials, followed by electronics at 18.9%, construction at 12.1%, and healthcare & pharmaceuticals at 9.1%, supported by medical-grade magnesium usage.
- For instance, Seres Motors achieves the highest average magnesium alloy usage per vehicle in China at approximately 19 kg, partnering with Baowu Magnesium to integrate these alloys into mass-produced new energy vehicle components for lightweighting.
By End-Use Industry:
The transportation industry emerged as the dominant end-use segment with a 41.2% market share in 2024, driven by extensive magnesium usage in automotive and aerospace manufacturing. Increasing investments in electric vehicles and lightweight aircraft components continue to strengthen demand. Industrial manufacturing accounted for 24.7% share, supported by die-casting and metal processing applications. Consumer electronics held 15.6% share, followed by energy & power at 10.4%, while medical & chemical processing captured 8.1% share, driven by pharmaceutical formulations and specialty chemical applications.
Key Growth Drivers
Rising Demand for Lightweight Materials in Automotive and Aerospace
The Magnesium Market is strongly driven by increasing demand for lightweight materials in the automotive and aerospace sectors to improve fuel efficiency and reduce carbon emissions. Automakers are increasingly substituting steel and aluminum with magnesium alloys in structural components, transmission housings, and interior parts to meet stringent emission regulations. In aerospace, magnesium’s high strength-to-weight ratio supports aircraft weight reduction and performance enhancement. The rapid growth of electric vehicles further accelerates magnesium adoption, as lightweight materials help extend driving range and improve battery efficiency.
- For instance, Rolls-Royce employs MSR magnesium alloy for the 130 kg Tay engine casing and RZ5 for the BMW Rolls-Royce BR710 casing, leveraging the material's properties for gearbox and engine applications in aircraft.
Expansion of Electronics and Consumer Devices Manufacturing
The growing production of consumer electronics significantly supports the Magnesium Market, as magnesium alloys are widely used in casings, frames, and heat-dissipation components for smartphones, laptops, tablets, and wearables. Manufacturers prefer magnesium due to its excellent thermal conductivity, electromagnetic shielding properties, and premium finish. Rising demand for compact, lightweight, and durable electronic devices, combined with increasing consumer spending on smart technologies, continues to drive magnesium consumption across global electronics manufacturing hubs.
- For instance, ASUS incorporates magnesium alloy in the chassis of its Zenbook S 13 OLED (UM5302), creating a super-thin 14.9 mm unibody that weighs just 1 kg while meeting MIL-STD-810H durability standards.
Increasing Use in Healthcare and Pharmaceutical Applications
Rising awareness of magnesium’s physiological benefits is driving its use in healthcare and pharmaceutical applications. Magnesium compounds are widely used in antacids, laxatives, dietary supplements, and injectable formulations due to their proven effectiveness and safety profile. Growth in preventive healthcare, aging populations, and increasing incidence of digestive and metabolic disorders are supporting demand. Additionally, magnesium’s biocompatibility has expanded its application in medical implants and specialty pharmaceutical formulations, strengthening long-term market growth.
Key Trends & Opportunities
Technological Advancements in Magnesium Alloy Processing
Ongoing advancements in magnesium alloy processing technologies present significant growth opportunities for the Magnesium Market. Innovations in casting, extrusion, and surface treatment techniques have improved mechanical strength, corrosion resistance, and formability, addressing historical performance limitations. These developments enable broader adoption across high-stress applications in automotive, aerospace, and industrial manufacturing. Improved recyclability and process efficiency also align with sustainability goals, encouraging manufacturers to integrate magnesium into next-generation lightweight material solutions.
- For instance, Sumitomo Electric, in collaboration with the University of Toyama, developed a heat-resistant magnesium alloy for die casting that exhibits superior compressive creep characteristics and tensile strength at 150-200°C, without using costly rare-earth elements, enabling its use as recyclable engine components.
Growing Focus on Sustainable and Recyclable Materials
The increasing global emphasis on sustainability is creating new opportunities for the Magnesium Market. Magnesium is fully recyclable and requires lower energy input for recycling compared to several alternative metals. Governments and manufacturers are prioritizing circular economy practices, encouraging the use of recyclable lightweight materials. This trend supports magnesium adoption in transportation, packaging, and energy applications. Rising investments in low-carbon manufacturing processes further enhance magnesium’s positioning as a sustainable material of choice.
- For instance, Okon Recycling captures magnesium scrap from automotive foundries and die-casting operations, where automotive components represent about 35% of old scrap sources, transforming it into reusable material before waste entry.
Key Challenges
Volatility in Raw Material Prices and Supply Constraints
The Magnesium Market faces challenges from fluctuating raw material prices and supply disruptions. Magnesium production is energy-intensive and highly sensitive to electricity costs, making pricing vulnerable to energy market volatility. Concentration of magnesium production in limited regions also exposes the market to geopolitical risks, trade restrictions, and regulatory changes. These factors can disrupt supply chains, increase production costs, and create pricing instability, affecting long-term planning for manufacturers and end users.
Environmental and Regulatory Pressures on Production Processes
Stringent environmental regulations pose a key challenge for the Magnesium Market, particularly for producers relying on traditional extraction and processing methods. Magnesium production can generate significant emissions if not managed through advanced technologies. Compliance with environmental standards increases capital and operational costs for manufacturers. Additionally, regulatory scrutiny related to waste disposal and carbon emissions may limit capacity expansion, compelling producers to invest heavily in cleaner technologies to remain competitive.
Regional Analysis
Asia Pacific
The Asia Pacific dominated the Magnesium Market with a 63.4% market share in 2024, supported by strong production capacity and high consumption across China, Japan, South Korea, and India. The region benefits from integrated magnesium supply chains, cost-efficient manufacturing, and extensive use in automotive, electronics, and industrial manufacturing sectors. China remains the primary producer and exporter, supplying magnesium for global alloy and casting applications. Rising electric vehicle production, expanding consumer electronics manufacturing, and continued infrastructure development further strengthen Asia Pacific’s leadership in the global magnesium industry.
North America
North America accounted for 15.2% market share in 2024, driven by growing demand from automotive lightweighting initiatives, aerospace manufacturing, and defense applications. The United States leads regional consumption due to increased adoption of magnesium alloys in vehicle components to meet fuel-efficiency and emission standards. Expanding aerospace production, supported by strong defense spending, further boosts magnesium demand. Additionally, rising investment in domestic magnesium production and recycling capabilities is improving supply security, supporting steady market growth across the region.
Europe
Europe held a 13.6% market share in 2024, supported by stringent emission regulations and strong focus on lightweight materials in automotive and aerospace industries. Countries such as Germany, France, and Italy are key consumers, utilizing magnesium alloys in vehicle body structures, powertrain components, and aircraft interiors. The region’s emphasis on sustainability and circular economy practices also supports magnesium recycling initiatives. Growing electric vehicle adoption and increasing use of magnesium in industrial manufacturing continue to reinforce Europe’s market position.
Latin America
Latin America represented 4.3% market share in 2024, driven by gradual growth in automotive production, construction activities, and industrial manufacturing. Brazil and Mexico are key markets, supported by expanding vehicle assembly plants and infrastructure investments. Magnesium demand in the region is also supported by increasing use of alloys in die-casting and metal processing applications. While local production remains limited, rising imports and improving industrial capabilities are supporting steady magnesium consumption growth across Latin America.
Middle East & Africa
The Middle East & Africa captured 3.5% market share in 2024, supported by growing industrialization, infrastructure development, and expanding energy projects. Demand is primarily driven by construction, industrial manufacturing, and emerging automotive assembly activities. Countries in the Middle East are investing in lightweight materials to support energy efficiency and advanced manufacturing goals. In Africa, gradual industrial growth and rising imports of magnesium products are contributing to market expansion, although consumption remains comparatively lower than other regions.
Magnesium Market Segmentations:
By Product Type
- Primary Magnesium
- Magnesium Alloys
- Magnesium Compounds
By Application
- Automotive
- Aerospace & Defense
- Electronics
- Construction
- Healthcare & Pharmaceuticals
By End-Use Industry
- Transportation
- Industrial Manufacturing
- Consumer Electronics
- Energy & Power
- Medical & Chemical Processing
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Magnesium Market features U.S. Magnesium LLC, RIMA Group, VSMPO-Avisma Corp., Nippon Kinzoku Co. Ltd., Alliance Magnesium, Latrobe Magnesium, Shanghai Sunglow Investment (Group) Co., Ltd., Mag Specialties Inc., Esan Eczacibasi, and Regal Metal. The market remains moderately consolidated, with competition centered on production scale, cost efficiency, alloy innovation, and supply reliability. Leading producers focus on expanding capacity, improving energy efficiency, and securing downstream partnerships with automotive, aerospace, and electronics manufacturers. Recycling-based producers are gaining traction by offering low-carbon magnesium, aligning with sustainability mandates. Asian players benefit from integrated supply chains and pricing advantages, while North American and European companies emphasize supply security and value-added alloys. Strategic investments in cleaner production technologies, recycling, and long-term offtake agreements continue to shape competitive positioning and barriers to entry.
Key Player Analysis
- VSMPO-Avisma Corp.
- Mag Specialties Inc.
- Nippon Kinzoku Co. Ltd.
- Shanghai Sunglow Investment (Group) Co., Ltd.
- Latrobe Magnesium
- Regal Metal
- Alliance Magnesium
- RIMA Group
- U.S. Magnesium LLC
- Esan Eczacibasi
Recent Developments
- In March 2025, Great Wall Motor and Baowu Magnesium established a strategic cooperation framework and joint laboratory to advance lightweight magnesium alloy applications in new energy vehicles (NEVs).
- In December 2025, an MoU was signed between Magmec and SMS group to develop a magnesium metal production facility in the UAE, aiming to establish domestic magnesium supply infrastructure.
- In 2025, Guangxi Automobile Group launched its lightweight magnesium alloy business at Chongqing Zhuotong, enhancing magnesium alloy use in automotive components.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Magnesium Market will continue to expand driven by rising lightweight material adoption across automotive and aerospace industries.
- Electric vehicle production growth will increase demand for magnesium alloys to improve energy efficiency and driving range.
- Advancements in magnesium alloy processing will enhance strength, corrosion resistance, and application scope.
- Recycling-based magnesium production will gain momentum due to sustainability and circular economy initiatives.
- Stricter emission regulations will encourage substitution of heavier metals with magnesium in transportation applications.
- Consumer electronics manufacturing growth will support steady demand for magnesium casings and components.
- Healthcare and pharmaceutical applications will expand with increasing use of magnesium compounds in medical formulations.
- Supply chain diversification efforts will strengthen regional production outside traditional manufacturing hubs.
- Investments in low-carbon and energy-efficient production technologies will reshape competitive dynamics.
- Industrial manufacturing and energy applications will provide long-term stability to overall market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Magnesium Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Magnesium Market projected to grow between 2024 and 2032?
Which Magnesium Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Magnesium Market?
Who are the leading companies in the Magnesium Market?
Which region commanded the largest share of the Magnesium Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Magnesium Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Magnesium Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,613 million → 2032: USD 8,413.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Magnesium Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Magnesium Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Magnesium Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Magnesium Market Drivers
- 3.3 Magnesium Market Restraints & Challenges
- 3.4 Magnesium Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Magnesium Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Magnesium Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Magnesium category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Magnesium Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Magnesium Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Magnesium market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Magnesium Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Magnesium Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Magnesium Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Magnesium (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Magnesium Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Magnesium Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Magnesium Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Magnesium Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Magnesium Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Magnesium Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Magnesium Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Magnesium Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Magnesium Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
