
Manual Resuscitator Market Overview:
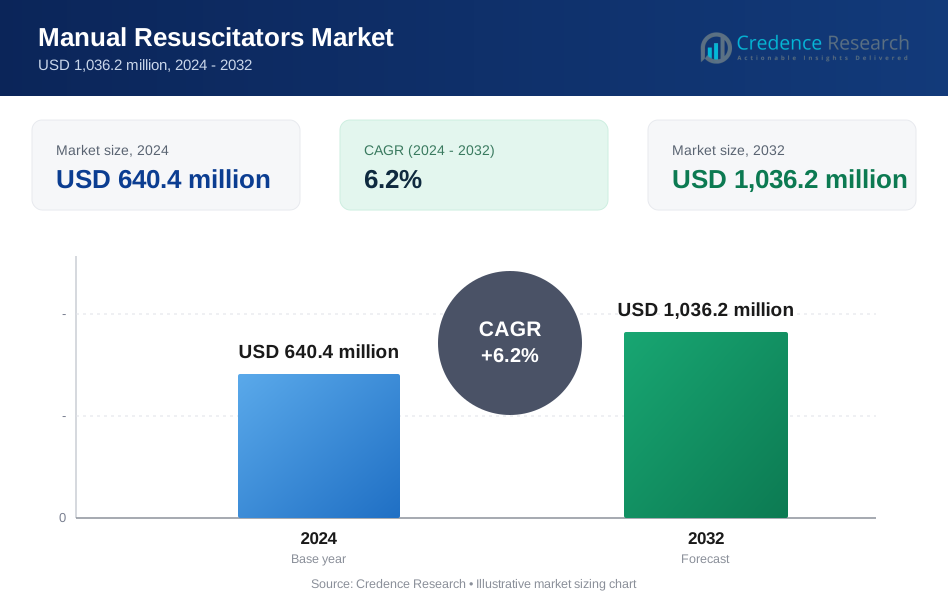
The Manual Resuscitator Market size was valued at USD 640.4 million in 2024 and is anticipated to reach USD 1,036.2 million by 2032, growing at a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Manual Resuscitator Market Size 2024 | USD 640.4 million |
| Manual Resuscitator Market, CAGR | 6.2% |
| Manual Resuscitator Market Size 2032 | USD 1,036.2 million |
Manual Resuscitator Market Insights
- Rising adoption in emergency and pre-hospital care, increasing awareness of infection control, and technological advancements such as smart monitoring and ergonomic designs are key drivers supporting market growth.
- Integration of smart monitoring features, real-time feedback systems, and expansion of homecare applications, especially in Asia-Pacific, Latin America, and the Middle East, are significant market trends creating new growth opportunities.
- High cost of advanced and premium devices, regulatory compliance, and product standardization challenges restrain market growth, particularly in emerging and price-sensitive regions.
- North America leads with 32.4% share in 2024, Europe holds 28.1%, Asia-Pacific 22.7%, Latin America 9.6%, and the Middle East & Africa 7.2%, reflecting strong regional adoption and market potential.

Manual Resuscitator Market Segmentation Analysis:
By Type
The Manual Resuscitator market is segmented into Self-inflating, Flow-inflating, and T-piece devices. Among these, Self-inflating resuscitators dominate the market, accounting for 61.5% share in 2024, driven by their ease of use in emergency settings, portability, and compatibility with various patient populations, including neonates, pediatrics, and adults. Growing adoption in pre-hospital and in-hospital emergency care, coupled with increased awareness among first responders and healthcare professionals, further fuels demand. The versatility and requirement for rapid ventilation support remain key drivers for this sub-segment’s market leadership.
- For instance, Laerdal's Silicone Resuscitator (LSR) provides transparent silicone material for excellent bag re-expansion, resistant to extreme temperatures, and superior feel of lung compliance to reduce over-inflation risk.
By Modality
The market is classified into Disposable and Reusable manual resuscitators. Disposable resuscitators hold the largest share at 57.8% in 2024, primarily due to heightened concerns over cross-contamination and hospital-acquired infections. Rising regulatory emphasis on single-use medical devices, combined with the need for infection control in critical care units, drives adoption. These devices also offer operational convenience by eliminating the need for sterilization and maintenance, making them highly preferred in emergency care, ambulatory services, and outpatient settings across global healthcare facilities.
- For instance, Teleflex's Hudson RCI Lifesaver disposable manual resuscitator features a 40cm pressure relief valve and Star-Lumen oxygen tubing to prevent overinflation and ensure consistent airflow, minimizing cross-contamination in code blue events, patient transport, and field rescues.
By Material
The market includes Silicon, PVC, and Rubber manual resuscitators. Silicon-based resuscitators are the dominant sub-segment with a 52.6% share in 2024, owing to their durability, flexibility, and resistance to high-temperature sterilization processes. The biocompatibility and chemical stability of silicon make it suitable for repeated use in critical and neonatal care. Increasing investments in premium healthcare devices and growing preference for long-lasting, reliable materials in hospitals and emergency care centers further support market growth. Silicon’s superior performance and user safety remain primary drivers for this segment’s leading position.
Key Growth Drivers
Rising Adoption in Emergency and Pre-Hospital Care
The growing emphasis on rapid intervention in critical and pre-hospital settings is a primary growth driver for the Manual Resuscitator market. Healthcare providers increasingly rely on these devices for immediate ventilation support during emergencies, ambulatory care, and disaster response. The ease of portability, compatibility with different patient populations including neonates and adults, and ability to function without a power source make manual resuscitators indispensable. Government initiatives promoting emergency preparedness and first responder training further enhance demand. Hospitals, clinics, and emergency medical services are investing in high-quality resuscitators, driving significant market expansion across developed and emerging regions.
- For instance, Ambu resuscitators feature on standardized ambulance equipment lists from the American College of Surgeons Committee on Trauma and other emergency organizations. These devices support hospital crash carts and bedsides for rapid ventilation.
Rising Awareness of Infection Control and Disposable Devices
Increasing concerns over hospital-acquired infections and cross-contamination are boosting demand for disposable manual resuscitators. Hospitals and critical care centers prioritize single-use devices to maintain stringent hygiene standards, particularly in neonatal, pediatric, and intensive care units. Regulatory bodies worldwide are advocating for disposable medical equipment to ensure patient safety, encouraging healthcare facilities to replace reusable devices with disposable alternatives. The operational convenience of eliminating sterilization requirements, coupled with faster availability during emergencies, supports adoption. These factors collectively position disposable resuscitators as a preferred solution, fueling market growth and driving innovation in infection-control-focused product designs.
- For instance, GaleMed's Dispo-Bag manual resuscitator, available in adult, pediatric, and infant sizes, reduces cross-contamination in ICUs and emergency rooms as a latex-free, single-use device meeting strict infection control protocols.
Technological Advancements and Material Innovation
Technological improvements and material innovations significantly contribute to market growth. Advanced materials such as high-grade silicon offer enhanced durability, flexibility, and resistance to repeated sterilization, appealing to both reusable and premium device segments. Ergonomic designs, integrated safety valves, and improved flow control mechanisms enhance ease of use and patient safety. Manufacturers are also developing lightweight, portable models that cater to field applications and neonatal care. These innovations improve device efficiency, reliability, and adoption across hospitals, emergency services, and homecare settings. Continuous R&D investment supports differentiation, increases clinical confidence, and expands the overall market footprint globally.
Key Trends & Opportunities
Integration with Smart Monitoring and Patient Safety Features
The integration of smart monitoring features, such as pressure sensors and real-time feedback systems, represents a significant trend and opportunity in the Manual Resuscitator market. These technologies allow healthcare professionals to monitor ventilation parameters accurately, reducing the risk of hypoxia or barotrauma. Coupled with ergonomic and lightweight designs, smart resuscitators are gaining traction in neonatal, pediatric, and adult care. Increasing adoption of digital health solutions in hospitals and pre-hospital emergency services creates opportunities for premium device segments. Manufacturers can capitalize on this trend by developing connected, intelligent resuscitators that enhance patient safety and operational efficiency, strengthening their market positioning.
- For instance, Laerdal's Upright Resuscitator for newborns integrates a pressure-limiting valve set at 30-45 cm H₂O alongside an optional PEEP valve delivering approximately 6 cm H₂O.
Expansion in Emerging Markets and Homecare Applications
Emerging markets present substantial growth opportunities due to increasing healthcare infrastructure investments and rising awareness of respiratory care. Countries in Asia-Pacific, Latin America, and the Middle East are witnessing higher demand for manual resuscitators in hospitals, ambulatory services, and homecare settings. Homecare adoption is being driven by rising chronic respiratory illnesses and aging populations requiring patient-managed ventilation support. Manufacturers targeting these markets can leverage cost-effective, portable, and disposable resuscitators to expand their footprint. Strategic collaborations, government support, and distribution network expansion in these regions provide a strong growth avenue for market players while addressing unmet healthcare needs.
- For instance, in South Korea, INSUNG Medical and JW Medical are enhancing manual resuscitator performance through design innovations that improve portability and control, supported by government programs for medical device modernization.
Key Challenges
High Cost of Advanced and Premium Devices
The high cost of technologically advanced manual resuscitators, particularly models with smart monitoring systems or premium silicon materials, poses a challenge for widespread adoption. Smaller hospitals, clinics, and emerging market healthcare facilities may find such devices financially prohibitive. This cost barrier restricts market penetration in price-sensitive regions and limits accessibility for low-resource emergency and pre-hospital care units. Additionally, the initial investment in training healthcare professionals to use advanced devices effectively can add to operational expenses. Balancing innovation with affordability remains a critical challenge for manufacturers seeking broader adoption and sustained growth.
Regulatory Compliance and Product Standardization
Stringent regulatory requirements for medical devices, including manual resuscitators, present a significant challenge for market players. Compliance with international standards for safety, efficacy, sterilization, and biocompatibility can increase product development timelines and costs. Varying regulatory frameworks across countries complicate global market entry, creating hurdles for manufacturers. Ensuring standardization in performance, material quality, and design is crucial to gain regulatory approvals and clinical trust. Delays or non-compliance may lead to product recalls, litigation risks, or market restrictions, making regulatory alignment a persistent challenge for growth in this highly regulated healthcare segment.
Regional Analysis
North America
The North American Manual Resuscitator market holds a 32.4% share in 2024, driven by well-established healthcare infrastructure, high prevalence of chronic respiratory disorders, and increasing emergency care initiatives. Widespread adoption of technologically advanced devices, including smart monitoring and disposable resuscitators, supports market growth. Government programs promoting first responder training and pre-hospital emergency preparedness further boost demand. Presence of key players such as Philips Healthcare, Medline Industries, and GE Healthcare enhances product availability and distribution efficiency. Increasing investment in hospital emergency units and homecare respiratory support solutions continues to propel market expansion across the United States and Canada.
Europe
Europe accounts for 28.1% share in 2024 of the Manual Resuscitator market, supported by robust healthcare systems, regulatory compliance standards, and high awareness of patient safety. Adoption of disposable and silicon-based resuscitators is accelerating, particularly in neonatal and intensive care units. Countries such as Germany, France, and the UK are investing in emergency preparedness and advanced hospital equipment. The presence of established manufacturers including Dräger Medical AG & Co., Ambu A/S, and Weinmann Emergency ensures high product penetration. Rising demand for portable and reusable resuscitators in pre-hospital and ambulatory care settings continues to drive regional growth.
Asia-Pacific
Asia-Pacific represents 22.7% share in 2024 of the Manual Resuscitator market, propelled by increasing healthcare infrastructure investments, expanding emergency medical services, and rising awareness of respiratory care. Growing neonatal and adult patient populations, coupled with rising incidences of chronic respiratory diseases, fuel demand for both disposable and reusable devices. Countries such as China, India, and Japan are witnessing high adoption of cost-effective, portable resuscitators. Collaborations between global manufacturers and regional distributors are enhancing product accessibility. Additionally, government initiatives to improve emergency response and rural healthcare capabilities provide significant opportunities for market expansion across the region.
Latin America
Latin America holds a 9.6% share in 2024 of the Manual Resuscitator market, driven by increasing investments in hospital infrastructure, emergency care training programs, and rising prevalence of respiratory illnesses. Countries such as Brazil and Mexico are adopting disposable and self-inflating resuscitators to improve patient safety and reduce infection risks. The expanding private healthcare sector and growing focus on pre-hospital emergency services are fueling demand. Collaborations with local distributors by global manufacturers such as Laerdal Medical and Ambu A/S enhance market reach. However, price sensitivity in the region encourages adoption of cost-effective, durable resuscitators suitable for widespread use.
Middle East & Africa
The Middle East & Africa region accounts for 7.2% share in 2024 of the Manual Resuscitator market, supported by growing healthcare infrastructure investments and increasing awareness of emergency medical care. Countries including Saudi Arabia, UAE, and South Africa are expanding hospital and pre-hospital emergency facilities. Rising demand for portable, disposable, and silicon-based resuscitators, particularly for neonatal and adult care, drives growth. Strategic partnerships between regional distributors and global manufacturers such as ResMed, Inc., and CareFusion (BD) enhance product availability. Government initiatives to improve emergency response capabilities and training programs for first responders further contribute to market expansion across the region.
Manual Resuscitator Market Segmentations:
By Type :
- Self-inflating
- Flow-inflating
- T-piece
By Modality :
- Disposable
- Reusable
By Material :
- Silicon
- PVC
- Rubber
By Application :
- Chronic Obstructive Pulmonary Disease
- Cardiopulmonary Arrest
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape of the Manual Resuscitator Market features key players including Ambu A/S, Laerdal Medical, Philips Healthcare, Covidien (Medtronic), Dräger Medical AG & Co., GE Healthcare, Medline Industries, ResMed, Inc., Weinmann Emergency, and CareFusion (BD). These companies dominate the market through a combination of innovative product portfolios, technological advancements, and expansive distribution networks. They focus on introducing disposable, reusable, and silicon-based resuscitators tailored to neonatal, pediatric, and adult care, enhancing patient safety and usability. Strategic partnerships, acquisitions, and regional expansions strengthen their market presence globally. Investment in R&D for ergonomic designs, smart monitoring, and portable solutions drives differentiation. Emphasis on regulatory compliance, quality certifications, and rapid response to emergency care demands ensures sustained adoption of their products. Competitive pricing and collaboration with hospitals, emergency services, and distributors allow these players to maintain leadership while capturing growth opportunities across North America, Europe, and emerging markets.
Key Player Analysis
- Weinmann Emergency
- GE Healthcare
- ResMed, Inc.
- Laerdal Medical
- CareFusion (BD)
- Medline Industries
- Dräger Medical AG & Co.
- Philips Healthcare
- Ambu A/S
- Covidien (Medtronic)
Recent Developments
- In August 2025, Ambu Inc. issued a recall of certain SPUR II manual resuscitators due to a blocked manometer port that rendered the pressure monitoring feature non‑functional, prompting an Urgent Field Safety Notice to healthcare providers to remove affected units from use.
- In May 2025, Laerdal Medical launched a compact, single-use manual resuscitator tailored for ambulances and emergency transport, emphasizing lightweight design and lower cross-contamination risks.
Report Coverage
The research report offers an in-depth analysis based on Type, Modality, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for portable and lightweight manual resuscitators will continue to rise across pre-hospital and emergency care settings.
- Adoption of disposable resuscitators will expand due to increased focus on infection control and hygiene standards.
- Technological innovations, including smart monitoring and ergonomic designs, will drive premium segment growth.
- Growth in neonatal and pediatric care will fuel demand for specialized resuscitator devices.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East will offer significant expansion opportunities.
- Strategic collaborations and partnerships between manufacturers and regional distributors will enhance market reach.
- Investment in training programs for first responders and healthcare professionals will boost adoption.
- Increasing prevalence of chronic respiratory diseases will sustain long-term demand for manual resuscitators.
- Manufacturers will focus on durable, silicon-based materials for reusable and high-performance devices.
- Regulatory compliance and standardization will remain critical for product development and global market entry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Manual Resuscitator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Manual Resuscitator Market projected to grow between 2024 and 2032?
Which Manual Resuscitator Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Manual Resuscitator Market?
Who are the leading companies in the Manual Resuscitator Market?
Which region commanded the largest share of the Manual Resuscitator Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Manual Resuscitators Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Manual Resuscitators Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 640.4 million → 2032: USD 1,036.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Manual Resuscitators Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Manual Resuscitators Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Manual Resuscitators Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Manual Resuscitators Market Drivers
- 3.3 Manual Resuscitators Market Restraints & Challenges
- 3.4 Manual Resuscitators Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Manual Resuscitators Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Manual Resuscitators Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Manual Resuscitators category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Manual Resuscitators Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Manual Resuscitators Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Manual Resuscitators market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Manual Resuscitators Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Manual Resuscitators Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Manual Resuscitators Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Manual Resuscitators (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Manual Resuscitators Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Manual Resuscitators Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Manual Resuscitators Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Manual Resuscitators Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Manual Resuscitators Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Manual Resuscitators Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Manual Resuscitators Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Manual Resuscitators Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Manual Resuscitators Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
