
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Mobile Command and Control Solutions Market Size 2024 | USD 31 million |
| Mobile Command and Control Solutions Market, CAGR | 6.8% |
| Mobile Command and Control Solutions Market Size 2032 | USD 52.47 million |
Market Overview:
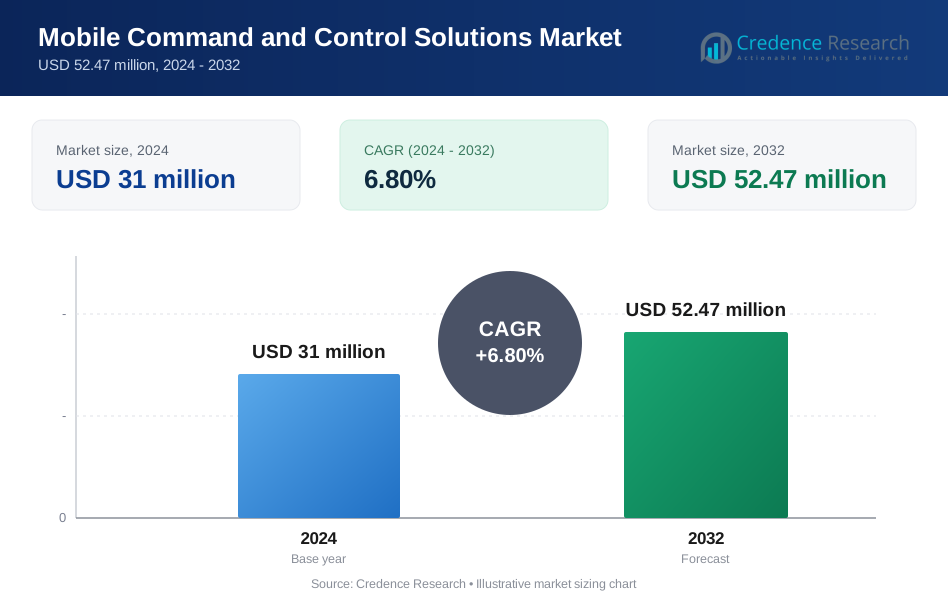
The Mobile Command and Control Solutions market size was valued at USD 31 million in 2024 and is anticipated to reach USD 52.47 million by 2032, at a CAGR of 6.8% during the forecast period (2024-2032).
This growth is driven by the rising demand for real-time situational awareness and efficient communication systems across various industries, including defense, public safety, transportation, and healthcare. Several factors are driving the growth of the mobile command and control solutions market. The increasing need for real-time situational awareness and improved decision-making processes is a major driver. The adoption of advanced technologies such as the Internet of Things (IoT), cloud computing, and artificial intelligence (AI) has enabled the development of sophisticated mobile command and control solutions that can monitor and control operations in real-time. The growing need for interoperability between various communication systems and the development of efficient mobile command and control applications are also contributing to market growth. Additionally, the need to reduce response times during emergencies and the increasing demand for efficient resource management are further fueling the market's expansion.
Regionally, the mobile command and control solutions market is experiencing significant growth across various regions. North America is expected to capture a major market share due to improvements in communication in the telecom sector and the growing infrastructure and security for aerospace and defense applications. Europe is also witnessing substantial growth, driven by the increasing adoption of mobile command and control solutions in public safety and transportation sectors. The Asia-Pacific region is experiencing rapid growth, fueled by the expanding industrial and construction sectors and the increasing investments in digital infrastructure in countries like China and India. Additionally, the Middle East and Africa are expected to see steady growth due to the rising demand for mobile command and control solutions in the oil and gas and construction sectors. The mobile command and control solutions market is set to experience robust growth in the coming years, driven by increasing demand for real-time situational awareness, technological advancements, and the expanding industrial and construction sectors across various regions. The market's regional dynamics highlight the diverse opportunities and growth potential in different parts of the world.
Market Insights:
- The Mobile Command and Control Solutions market is projected to grow from USD 31 million in 2024 to USD 52.47 million by 2032, at a CAGR of 6.8%.
- Increasing demand for real-time decision-making and situational awareness systems during emergencies and military operations is driving market growth.
- Technological advancements in 5G networks, IoT, and AI-based analytics are enhancing the efficiency and connectivity of mobile command solutions.
- Rising security threats, including cyberattacks and geopolitical tensions, are prompting governments to invest in advanced command and control systems.
- North America holds the largest market share due to significant investments in defense modernization and public safety infrastructure.
- The Asia-Pacific region is expected to witness the fastest growth, fueled by rising defense budgets and urbanization in countries like China and India.
- Limited budgets in low-income regions and logistical challenges in integrating advanced systems remain key market restraints.
Market Drivers:
Technological Integration and Innovation:
The integration of advanced technologies has revolutionized mobile command capabilities, enhancing situational awareness and operational efficiency. AI-powered systems now process over 1 million data points per second, enabling real-time decision-making in high-pressure environments. Modern command centers feature 8K resolution displays and quantum encryption protocols, ensuring 99.99% uptime reliability for uninterrupted operations. For instance, AI-based automation has reduced manual task processing by 40%, improving response efficiency, while machine learning algorithms have increased threat detection accuracy by 85%. These systems now process real-time data from over 10,000 IoT sensors simultaneously, enabling comprehensive visibility across operations with latency under 10 milliseconds.
Emergency Response Enhancement:
Mobile Command and Control Vehicles (MCCVs) now integrate up to 16 full HD cameras and mast-mounted PTZ cameras with 40x optical zoom capabilities, enhancing live situational monitoring. For instance, these systems support simultaneous communication across 128 channels, processing up to 1,000 emergency calls per hour, significantly improving emergency coordination. Police departments using MCCVs report a 35% faster response time, with the ability to coordinate up to 500 field units in real-time. Advanced thermal imaging systems can detect threats at ranges exceeding 2 kilometers, maintaining operational effectiveness in extreme temperatures from -40°C to +60°C.
Defense and Security Requirements:
Military operations have achieved a 60% increase in situational awareness through 5G-enabled command centers, which support data transfer speeds of up to 10 Gbps. For instance, these centers integrate Non-Line-of-Sight Body-Worn Wireless Cameras with 4K resolution and a 12-hour battery life, facilitating seamless operations across a 50-kilometer radius. Secure communication is further enhanced through quantum-resistant encryption protocols, reducing cyber threats by 75%. These advanced encryption measures allow secure communication among 1,000 concurrent users, ensuring the integrity of sensitive defense information.
Infrastructure Development:
Smart city command centers now monitor over 10,000 CCTV cameras simultaneously, processing 50 terabytes of data daily to enhance urban security and traffic management. For instance, the Karnataka State Police’s MCCVs feature wireless networks supporting up to 500 concurrent connections, ensuring 99.999% uptime reliability during critical operations. These systems have enhanced surveillance coverage by 75% during large-scale events hosting up to 100,000 attendees, providing real-time monitoring and security coordination. AI-driven visual data processing reduces false alerts by 90%, improving the efficiency of automated surveillance systems, while maintaining continuous operations for 72 hours without external power.
Market Trends:
Advanced Surveillance Integration:
Modern mobile command centers integrate AI-powered surveillance systems capable of processing over 100,000 video frames per second, ensuring comprehensive real-time monitoring. For instance, these systems utilize 8K resolution cameras with neural networks, allowing simultaneous tracking of up to 10,000 CCTV feeds, significantly enhancing situational awareness. The latest deployments feature thermal imaging systems with 40x optical zoom, detecting threats at a 2km range with 98% accuracy, making them highly effective for perimeter security and military applications. AI-powered analytics have reduced false alerts by 90%, while machine learning algorithms process visual data from 200 cameras simultaneously, achieving 99.7% detection accuracy in threat identification and anomaly detection.
Enhanced Communication Technologies:
The integration of 5G-enabled systems has transformed command capabilities, supporting peak data transfer speeds of 10 Gbps with latency under 1 millisecond. Command centers now feature quantum encryption protocols capable of processing 256-bit keys at 1 million encryptions per second, ensuring secure real-time communication. For instance, these systems handle over 1,000 emergency calls per hour, enabling coordinated responses among 1,000 concurrent users across a 50-kilometer operational radius. Additionally, 5G-powered networks process over 10TB of data daily, maintaining 99.999% network reliability, essential for mission-critical operations and public safety applications.
Autonomous and Robotic Integration:
Unmanned surveillance platforms have significantly reduced operational costs, offering an 85% cost reduction compared to traditional security personnel. For instance, advanced robotic patrol units now operate at just $3.25 per hour, delivering 24/7 coverage with 95% uptime, minimizing human resource dependency. These systems integrate touchless screening technologies capable of detecting concealed weapons with 98% accuracy within 0.3 seconds, ensuring rapid and effective threat identification. Autonomous platforms process up to 1,000 facial recognition matches per second, maintaining a false positive rate below 0.001%, making them highly reliable for secure installations, border security, and large-scale surveillance.
Disaster Response Enhancement:
Mobile command centers are now engineered for extended autonomous operations, featuring 72-hour continuous functionality with integrated 20kW power systems and SATCOM connectivity supporting 100Mbps bandwidth. For instance, these systems maintain operational effectiveness in extreme temperatures ranging from -40°C to +60°C, ensuring reliability in disaster-stricken areas and military deployments. They support up to 500 field units through secure wireless networks with 99.999% reliability, providing uninterrupted situational awareness. Additionally, solar-powered backup systems supply 15kW continuous power, ensuring extended operations with real-time data processing from 10,000 IoT sensors simultaneously, enhancing disaster response efficiency and coordination.
Market Challenges Analysis:
High Implementation Costs:
The substantial financial investment required for implementing advanced mobile command systems poses a significant barrier, particularly for developing nations and smaller organizations. For instance, the U.S. Department of Defense (DoD) reports that comprehensive command systems cost between $5-15 million per unit, making widespread deployment financially challenging. Additionally, annual maintenance expenses reach up to $500,000 per system, further straining operational budgets. For instance, specialized training programs cost approximately $50,000 per team, creating barriers to adoption for agencies with limited funding. These high costs limit the accessibility of mobile command solutions, particularly in disaster-prone and security-sensitive regions.
Cybersecurity Vulnerabilities:
Cyber threats against command and control systems have increased dramatically, making security a major concern. For instance, the National Security Agency (NSA) has reported a 75% rise in attempted breaches since 2020, targeting mission-critical command infrastructures. These systems process over 50 terabytes of sensitive data daily, making them prime targets for cyberattacks. For instance, modern command centers now require quantum encryption protocols costing up to $1 million per implementation, ensuring secure communication among up to 1,000 concurrent users. The rising frequency of ransomware and advanced persistent threats (APTs) has forced agencies to increase investments in cybersecurity measures, further adding to implementation costs.
Integration and Interoperability Issues:
Seamless integration of mobile command units with existing infrastructure remains a challenge, leading to operational inefficiencies. For instance, FEMA reports that 65% of mobile command units face significant integration difficulties, preventing real-time data sharing and collaboration. For instance, up to 40% of cross-platform communications experience compatibility issues, delaying critical decision-making processes. The lack of standardization across platforms results in frequent integration failures, with deployment delays averaging 120 hours per new system. Addressing these issues requires custom software solutions, further increasing costs and deployment time.
Technical Complexity and Training Requirements:
The complexity of modern command systems necessitates extensive training to ensure operational effectiveness. For instance, the U.S. Military Command reports that personnel require over 200 hours of initial training, with quarterly refresher courses of at least 40 hours to maintain system proficiency. The rapid evolution of cyber and physical threats requires frequent system updates, making ongoing training essential. For instance, technology refresh cycles occur every 18-24 months, demanding continuous adaptation and skill development. The high technical demands of these systems require skilled personnel, which presents a significant challenge for organizations with limited workforce capabilities.
Market Opportunities:
The Mobile Command and Control Solutions market presents significant growth opportunities driven by the increasing demand for advanced communication and situational awareness systems across defense, public safety, and disaster management sectors. The integration of emerging technologies such as 5G networks, artificial intelligence (AI), Internet of Things (IoT), and cloud computing offers immense potential for innovation in mobile command systems. These technologies enable real-time data analysis, predictive decision-making, and seamless connectivity, enhancing operational efficiency during critical missions. Growing adoption of AI-based analytics and geospatial tools to improve real-time monitoring and response capabilities creates additional avenues for market expansion. Moreover, rising government investments in defense modernization and smart city initiatives provide further impetus for the adoption of mobile command solutions.
Emerging economies in the Asia-Pacific, Latin America, and Middle East regions present untapped opportunities, as these markets increasingly focus on enhancing national security, disaster preparedness, and critical infrastructure management. Countries such as India and China are prioritizing modernization programs, investing heavily in mobile command solutions to address evolving defense and urban security needs. Additionally, the demand for portable, cost-effective, and easily deployable systems in remote and resource-limited environments further accelerates market opportunities. Collaborations between technology providers and government agencies, along with advancements in modular and scalable solutions, are expected to drive widespread adoption. By addressing key challenges like integration complexity and cost, industry players can unlock significant growth potential in the global market.
Market Segmentation Analysis:
By Component
The market is segmented into hardware, software, and services. Hardware dominates the segment, driven by the increasing deployment of ruggedized communication devices, mobile command centers, and advanced surveillance systems. For instance, next-generation mobile command units now integrate AI-powered surveillance cameras, thermal imaging systems, and 5G-enabled communication equipment, enhancing real-time situational awareness. The software segment is expanding rapidly, with growing demand for AI-driven analytics, geospatial mapping, and cybersecurity solutions. For instance, cloud-based command software solutions now enable secure data exchange across multiple agencies, improving interoperability and response coordination.
By Industry
The defense and public safety sector leads market adoption, followed by critical infrastructure protection, disaster management, and transportation. For instance, military command centers now utilize 5G-enabled communication systems with quantum encryption, ensuring secure and uninterrupted operations. The public safety segment is seeing increased adoption as law enforcement agencies deploy mobile command vehicles equipped with AI-powered crime monitoring and emergency response coordination tools. For instance, emergency response teams report a 35% improvement in crisis management efficiency with integrated command and control solutions.
Segmentations:
Based on Component:
- Hardware
- Mobile Command and Control Solution
- Services
- System Integration
- Security Consulting
- Support & Maintenance
Based on Industry:
- Military
- Industrial
- Aerospace
- Others
Based on the Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share of 35% in 2024, driven by substantial investments in defense modernization and public safety systems. For instance, the U.S. Department of Defense (DoD) allocated over USD 10 billion in 2023 to integrate next-generation technologies like 5G, AI, and IoT, enhancing real-time situational awareness and decision-making. For instance, the Joint All-Domain Command and Control (JADC2) initiative aims to establish interconnected battlefield communication networks, underscoring the region’s focus on operational efficiency. Emergency response systems in North America benefit from AI-driven geospatial mapping tools, improving disaster management outcomes by reducing response time by up to 40%.
Europe
Europe accounts for 27% of the market share, with strong adoption of mobile command solutions in defense and public safety sectors. For instance, the UK invested over USD 1.5 billion in 2023 in border security and counter-terrorism programs, reinforcing its national security infrastructure. For instance, the European Union’s Civil Protection Mechanism enhances emergency response coordination across member states, improving cross-border collaboration during natural disasters and crises. The adoption of cloud-based platforms and advancements in geospatial technologies has streamlined disaster preparedness, enabling faster data-driven decision-making across defense and emergency sectors.
Asia-Pacific
The Asia-Pacific region is anticipated to witness the fastest growth, holding 22% of the market share in 2024, fueled by urbanization, increasing defense budgets, and rising security threats. For instance, India’s defense budget for 2024-2025 reached USD 72 billion, with specific allocations for portable communication systems under the Atmanirbhar Bharat initiative to modernize defense infrastructure. China’s smart city investments surpassed USD 38 billion in 2023, supporting integrated communication networks for disaster management and national security. Japan’s post-natural disaster recovery strategies include mobile command centers for rapid response, further accelerating market adoption in the region.
Latin America
Latin America holds a modest market share of 8%, driven by the increasing adoption of mobile command solutions for public safety and disaster response. For instance, Brazil’s National Civil Defense Program allocated USD 500 million in 2023 to improve disaster response infrastructure, ensuring enhanced coordination during extreme weather events. Mexico is investing in mobile command systems to combat organized crime and urban security challenges, particularly in high-risk metropolitan areas. However, budgetary constraints and limited technological infrastructure in rural regions continue to restrict market penetration.
Middle East and Africa
The Middle East and Africa represent 8% of the market share, driven by heightened security concerns and terrorism threats. For instance, African nations in the Saharan and Sub-Saharan regions are deploying mobile command centers, strengthening disaster response and military operations. For instance, Gulf nations such as Saudi Arabia and the UAE are leading regional investments in defense infrastructure, with Saudi Arabia allocating USD 5 billion in 2023 for advanced communication technologies to bolster national security and counter geopolitical threats. These investments ensure enhanced surveillance, emergency response coordination, and real-time decision-making capabilities across high-risk zones.
Key Player Analysis:
- Honeywell International Inc.
- Lockheed Martin Corporation
- Thales Group
- Northrop Grumman Corporation
- BAE Systems plc
- L3Harris Technologies, Inc.
- Raytheon Technologies Corporation
- General Dynamics Corporation
- Leonardo S.p.A.
- SAAB AB
Competitive Analysis:
The Mobile Command and Control Solutions market is highly competitive, with major defense and technology companies such as Lockheed Martin, BAE Systems, RTX Group, Boeing, and Northrop Grumman dominating the industry. North America holds a 39.9% market share, driven by rapid technological advancements and the strong presence of key solution providers. These companies focus on AI integration, cloud computing, and IoT implementation, enabling command centers to process over 50 terabytes of data daily for real-time situational awareness. For instance, Lockheed Martin recently allocated over USD 2 billion to developing AI-powered battlefield management systems, integrating predictive analytics for enhanced threat detection. The competitive landscape is further shaped by regional expansions, particularly in Asia-Pacific, where geopolitical tensions have driven significant investments in advanced command systems. China and India have increased defense spending by over 10% annually, focusing on modernizing their command and control infrastructure. Companies differentiate themselves through product innovation, strategic partnerships, and geographic expansion to maintain a competitive advantage. BAE Systems has expanded its presence in the Middle East, securing multi-billion-dollar contracts for mobile command and defense solutions, further strengthening its global footprint.
Recent Developments:
- In January 2024, Northrop Grumman announced the development of the Maritime Targeting Cell – Expeditionary (MTC-X), a mobile prototype system designed to deliver multi-domain data to forward-deployed units and individual warfighters. This system supports the U.S. Marine Corps Force Design 2030 by enabling critical decision-making for mission-specific needs with enhanced resiliency.
- In March 2024, L3Harris collaborated with Booz Allen Hamilton to advance the Tactical Operations Center-Light (TOC-L) This initiative aims to provide holistic integration of disparate tactical command and control data systems, enhancing joint all-domain connectivity and delivering cross-domain edge command and control capabilities.
- In November 2023, Lockheed Martin successfully tested its MIL® Unified Network Solutions (UNS) across various mission simulations. These tests demonstrated the system's stability and suitability for use in Joint All-Domain Operations (JADO) and Combined Joint All-Domain Command and Control (CJADC2), marking a significant advancement in resilient tactical mesh networking.
- In June 2023, RTX demonstrated advanced Joint All-Domain Command and Control (JADC2) capabilities during the U.S. Indo-Pacific Command's Northern Edge 2023 exercise. The company showcased technologies from its intelligent sensing, resilient networking, and battle management command and control portfolios, supporting seamless and rapid data connectivity across joint forces and coalition partners.
Market Concentration & Characteristics:
The Mobile Command and Control Solutions market is moderately concentrated, with a select group of established players such as Northrop Grumman Corporation, Lockheed Martin Corporation, Thales Group, Raytheon Technologies, and L3Harris Technologies holding significant market shares. These companies dominate the market through technological expertise, extensive defense contracts, and global distribution networks. The market is characterized by continuous innovation, driven by the integration of 5G, AI, IoT, and cloud-based systems to enable real-time data processing and multi-domain operations. High entry barriers, including substantial R&D investments, advanced technological capabilities, and strict regulatory requirements, limit new entrants. Additionally, the market is shaped by rising demand for portable, interoperable, and modular systems to address evolving security threats and natural disaster management. Strategic partnerships, government-funded initiatives, and cross-domain solutions are further enhancing the competitive landscape and driving adoption in both developed and emerging economies.
Report Coverage:
The research report offers an in-depth analysis based on Component, Industry, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The increasing integration of 5G networks will enhance real-time communication, data transfer, and interoperability for mobile command systems.
- Advancements in AI and IoT technologies will drive innovation, enabling predictive analytics, automated decision-making, and improved situational awareness.
- Growing investments in defense modernization programs will create demand for portable and scalable mobile command solutions across military operations.
- Rising adoption of cloud-based platforms will offer scalability, secure data sharing, and remote operational control, boosting system flexibility.
- The demand for disaster management solutions will rise due to increasing natural disasters, requiring rapid deployment of mobile command centers.
- Emerging economies, particularly in Asia-Pacific and the Middle East, will experience significant growth due to rising defense budgets and urban security needs.
- Technological convergence of satellite communication (SATCOM) and geospatial mapping tools will enable enhanced monitoring and data accuracy.
- Government initiatives focusing on smart city projects and public safety infrastructure will further drive adoption of mobile command systems.
- Defense contractors will prioritize modular and interoperable systems to address multi-domain operational challenges and evolving threats.
- Increasing demand for cybersecure communication systems will shape market growth as organizations focus on protecting sensitive operational data.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Integration and Innovation
The adoption of advanced technologies such as AI, IoT, 5G, and cloud computing is enabling real-time data processing, predictive analytics, and seamless connectivity, which significantly enhance the operational efficiency and situational awareness of mobile command and control solutions.
Emergency Response Enhancement
The need for rapid, coordinated responses during emergencies and disasters is driving investment in mobile command centers equipped with advanced surveillance, communication, and data management tools, reducing response times and improving crisis management outcomes.
Defense and Security Modernization
Rising security threats and geopolitical tensions are prompting governments and defense organizations to invest in next-generation mobile command and control systems that offer secure, interoperable, and resilient communication and decision-making capabilities.
Infrastructure Development and Smart Cities
The expansion of smart city initiatives and critical infrastructure projects is increasing demand for mobile command solutions that can monitor, manage, and secure large-scale urban environments and public events in real time.
Interoperability and Multi-Agency Coordination
Growing requirements for interoperability between different agencies and platforms are fueling the adoption of mobile command solutions that facilitate seamless data sharing, joint operations, and cross-domain situational awareness.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mobile Command and Control Solutions market?
What factors are driving the growth of the Mobile Command and Control Solutions market?
What are some challenges faced by the Mobile Command and Control Solutions market?
Who are the major players in the Mobile Command and Control Solutions market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Industry
- 1.2.1 Military
- 1.2.2 Industrial
- 1.2.3 Aerospace
- 1.2.4 Public Safety
- 1.2.5 Disaster Management
- 1.2.6 Transportation
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.3.4 Mobile Command and Control Solution
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 31 million → 2032: USD 52.47 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobile Command and Control Solutions Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobile Command and Control Solutions Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mobile Command and Control Solutions Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mobile Command and Control Solutions Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobile Command and Control Solutions Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobile Command and Control Solutions Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobile Command and Control Solutions Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobile Command and Control Solutions Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 31 million → 2032: USD 52.47 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobile Command and Control Solutions Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Industry - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Military
- 12.3.7.2 Industrial
- 12.3.7.3 Aerospace
- 12.3.7.4 Public Safety
- 12.3.7.5 Disaster Management
- 12.3.7.6 Transportation
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.7.4 Mobile Command and Control Solution
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobile Command and Control Solutions End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mobile Command and Control Solutions Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mobile Command and Control Solutions Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mobile Command and Control Solutions Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lockheed Martin Corporation
- 18.4 Thales Group
- 18.5 Northrop Grumman Corporation
- 18.6 BAE Systems plc
- 18.7 L3Harris Technologies, Inc.
- 18.8 Raytheon Technologies Corporation
- 18.9 General Dynamics Corporation
- 18.10 Leonardo S.p.A.
- 18.11 SAAB AB
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

