
Market Overview
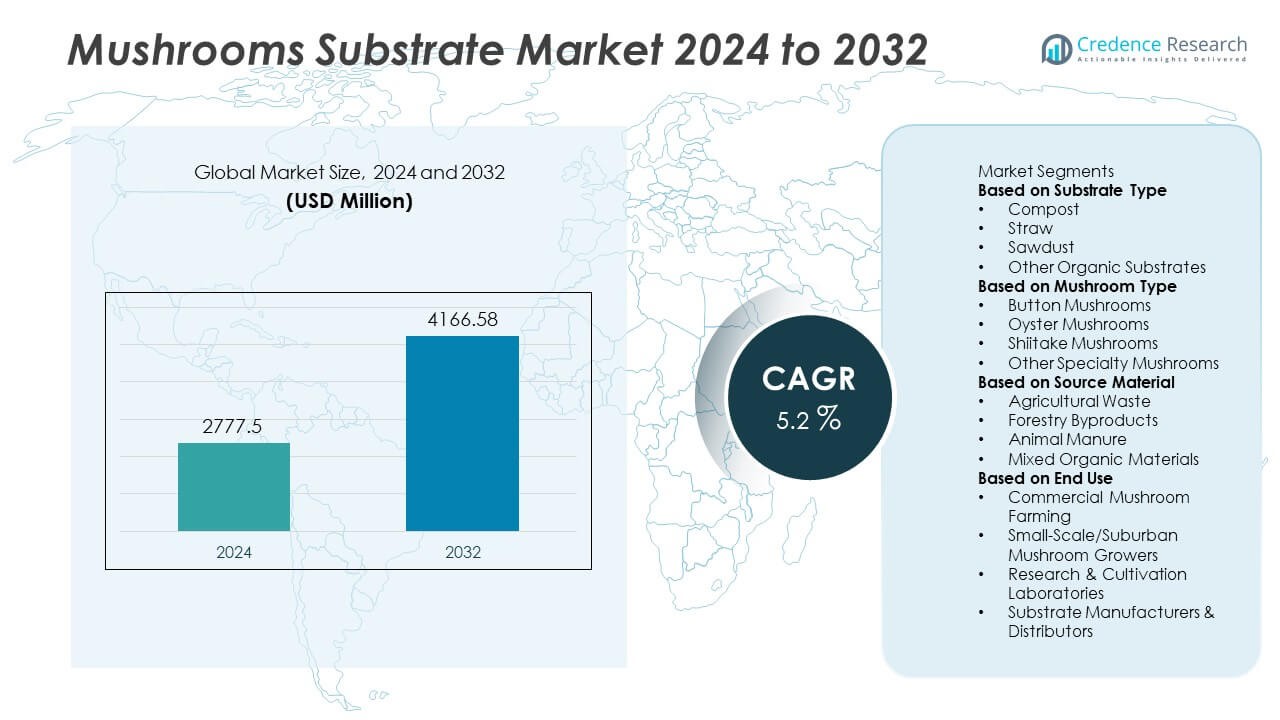
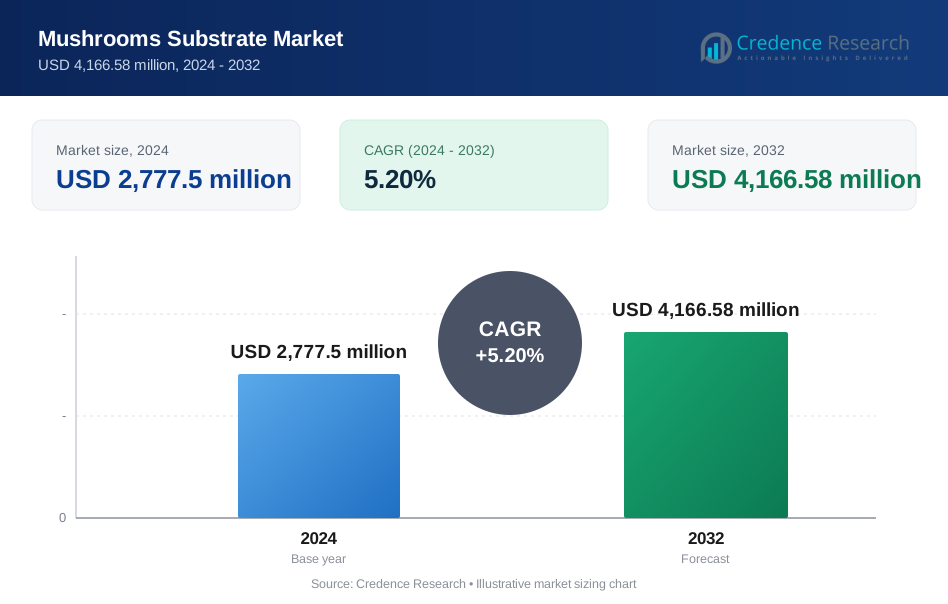
The Mushrooms Substrate Market reached USD 2,777.5 million in 2024 and is projected to grow to USD 4,166.58 million by 2032, recording a 5.2% CAGR over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mushrooms Substrate Market Size 2024 | USD 2,777.5 Million |
| Mushrooms Substrate Market, CAGR | 5.2% |
| Mushrooms Substrate Market Size 2032 | USD 4,166.58 Million |
The Mushrooms Substrate market includes leading participants such as Italspawn, Mushroom Substrate Solutions, Amycel Spawn, Mycelia BV, Hirano Mushroom LLC, Agrinoon (Fujian) Biological Co., Ltd, Highline Mushrooms, Aloha Medicinals, Phoratec Mushroom Supplies, and Sylvan Inc. These companies focus on compost, straw, and sawdust substrate formulations to improve yield efficiency, mycelium colonization speed, and contamination control for button, oyster, shiitake, and other specialty mushrooms. Product innovation continues in sterilized ready-to-use substrate blocks and enriched blends supporting medicinal mushroom cultivation. North America leads the market with a 34% share, followed by Europe with 28%, supported by expanding commercial mushroom operations, controlled-environment farming, and strong integration of agricultural and forestry byproduct substrates.
Market Insights
- The Mushrooms Substrate market reached USD 2,777.5 million in 2024 and is projected to reach USD 4,166.58 million by 2032, registering a 5.2% CAGR during the forecast period.
- Strong growth in commercial mushroom farming drives substrate demand, with compost leading the substrate type segment at 42% share, driven by high suitability for button and oyster mushroom production and consistent yield outcomes.
- Trends include rising adoption of ready-to-use sterilized substrate blocks, substrate enrichment for medicinal mushrooms, and expanding use of agricultural and forestry waste supporting circular farming practices.
- The market remains competitive with innovation in substrate sterilization, pathogen control, and distribution networks, while contamination risks, raw material variability, and production cost sensitivity continue to challenge small and emerging growers.
- North America holds 34%, Europe 28%, Asia Pacific 24%, Latin America 8%, and Middle East & Africa 6% of the market share, supported by strong adoption of compost, sawdust, and straw substrate formulations across commercial and decentralized mushroom cultivation.
Market Segmentation Analysis:
By Substrate Type:
Compost dominates the Mushrooms Substrate market with a 42% share, driven by high suitability for button, oyster, and portobello mushroom cultivation. Compost provides balanced nutrients, promotes stable mycelium growth, and supports higher yield consistency across commercial production systems. Straw substrate follows, mainly used in oyster and specialty mushroom farming due to accessibility and cost advantages. Sawdust plays a key role in shiitake and wood-based mushroom varieties, supporting dense fruiting bodies and improved shelf life. Other organic substrates, including coffee grounds and coco coir blends, gain attention from small-scale and urban growers focused on circular waste utilization.
- For instance, Mycelia NV produces high-quality mycelium spawn and mother cultures, which professional growers then use to inoculate a variety of substrates (such as sawdust or agricultural waste). This inoculum supports standardized shiitake strain performance, enabling the customer to grow mushrooms or create mycomaterials.
By Mushroom Type:
Button mushrooms lead the segment with a 48% market share, supported by strong global consumption and well-established commercial cultivation practices. These mushrooms rely heavily on compost-based substrates, enabling high-volume production and uniform crop cycles. Oyster mushrooms are the next major category, benefiting from rapid growth cycles and rising dietary demand. Shiitake mushrooms show steady expansion, supported by sawdust and wood-enriched substrate adoption for premium and medicinal markets. Other specialty mushrooms, including reishi, maitake, and lion’s mane, gain traction as functional food demand increases and substrate formulations evolve to enhance bioactive compound development.
- For instance, Sylvan is an important U.S. producer of fresh mushrooms and operates U.S. spawn production facilities in Pennsylvania and Nevada, as well as international plants. The company houses an extensive collection of over 600 strains from more than 50 mushroom species in its laboratories.
By Source Material:
Agricultural waste sources hold a 44% share, driven by large-scale use of straw, corn cobs, bran, and other crop residues in substrate mixing. This material supports sustainable production and reduces input costs for mushroom farms of varying sizes. Forestry byproducts, including sawdust and wood chips, remain essential for shiitake and wood-loving mushroom species, supporting dense and nutrient-rich substrate development. Animal manure blends enhance microbial diversity and compost efficiency, strengthening substrate performance in button mushroom farming. Mixed organic materials, including composted blends with coffee grounds, paper waste, and horticultural residues, gain interest in urban and small-scale mushroom operations focused on circular nutrient systems.
Key Growth Drivers
Rising Commercial Mushroom Cultivation Demand
Commercial mushroom farming expands globally due to growing consumption of button, oyster, and shiitake varieties. Substrate suppliers benefit as farms seek high-yield formulations that support faster colonization and stable crop cycles. Large producers adopt compost, straw, and enriched sawdust substrates to improve output and consistency across climate-controlled cultivation units. Rising interest in protein-rich, low-fat mushroom products supports farm investments in optimized substrate blends. Government-supported agricultural diversification programs and training for mushroom growers further accelerate substrate market growth. The driver remains strong as food processors and retail chains increase sourcing of fresh and processed mushrooms.
- For instance, Highline Mushrooms utilizes advanced technology and climate control in its facilities, including a "Farm of the Future" in Leamington, to ensure consistent and high-quality organic mushroom production. The company focuses on efficiency, with mushrooms going from farm to shelf in 24 hours.
Increasing Use of Agricultural and Forestry Waste
The growing focus on circular bioeconomy practices drives substrate production from crop residues, sawdust, and manure. These materials create cost-effective substrate mixes while reducing environmental waste and improving farm sustainability. Producers use straw, corn cobs, rice husk, and wood byproducts to support the nutritional needs of different mushroom species. This approach lowers substrate input expenses and enables year-round cultivation. Adoption grows as mushroom farming becomes a preferred income source for rural communities and small growers. Regulatory encouragement for organic cultivation strengthens this driver by supporting waste-to-resource applications in agriculture.
- For instance, the Fujian Kaisheng Biomass Power Plant uses rice husk and other agricultural residues as fuel to generate electricity, with a total nameplate capacity of 24 MW.
Rising Demand for Functional and Medicinal Mushrooms
Consumer interest in immune-boosting and nutritionally dense mushrooms supports substrate innovation for premium species such as shiitake, lion’s mane, and reishi. These mushrooms require enriched sawdust and wood-based substrate blends for higher bioactive compound levels. Functional mushroom supplements, extracts, and powders expand demand for controlled substrate formulations with traceable input quality. Health-conscious consumers and nutraceutical brands drive farms to adopt substrate solutions that improve yield potency. The growing global focus on natural wellness ingredients positions medicinal mushroom cultivation as a key growth contributor for the substrate market.
Key Trends & Opportunities
Growth of Ready-to-Use and Sterilized Substrate Blocks
Ready-to-use substrate blocks gain popularity among commercial and small-scale growers due to their convenience and reduced contamination risk. Sterilized and pre-inoculated substrate products enable faster colonization, higher yield reliability, and efficient handling for beginners and experienced farmers. The trend aligns with the rise of indoor and vertical mushroom farms that use controlled substrate formats to standardize output. Online distribution creates strong opportunities for substrate suppliers targeting hobby growers and urban farming communities. The opportunity strengthens as demand for subscription-based and pre-prepared substrate kits increases across major markets.
- For instance, Aloha Medicinals operates facilities involved in the production of mushroom products, utilizing equipment as part of its manufacturing process.
Expansion of Organic and Sustainable Mushroom Production
Growing demand for organic-certified mushrooms encourages substrate producers to offer chemical-free, traceable input sources. Organic farming trends support substrate blending from plant residues, sawdust, and livestock compost without synthetic additives. Sustainable substrates align with consumer expectations for eco-friendly, low-carbon cultivation systems. Certifications create new opportunities for suppliers to serve premium food, wellness, and export markets. The trend offers long-term growth potential as restaurants, retailers, and nutraceutical manufacturers increase sourcing of sustainably grown mushroom ingredients.
- For instance, Agrinoon Biological produces mushroom substrate and spawn and manages organic waste for agricultural use, contributing to the circular economy within the farming industry.
Key Challenges
Contamination Risks and Quality Control Issues
Substrate quality is critical for successful colonization, and contamination risks remain a major challenge. Poor sterilization, improper moisture control, and pathogen presence can cause complete crop loss. Small and medium-scale growers face difficulty achieving consistent substrate performance without advanced processing equipment. Contamination also increases farm production costs and reduces supply reliability for commercial buyers. Ensuring substrate purity requires reliable sourcing, testing, and standardized manufacturing methods, which may raise product prices. Suppliers must focus on hygiene control and technical support to overcome this challenge.
Supply Chain Limitations and Raw Material Variability
Substrate production depends on the availability of agricultural and forestry byproducts, which vary seasonally and geographically. Limited access to straw, manure, and quality sawdust may disrupt mixing ratios and performance consistency. Transportation costs increase for bulk substrate materials due to weight and handling requirements. Suppliers must adjust formulations to maintain nutrient balance despite input variability. These constraints challenge scale-up of substrate manufacturing in regions with limited biomass processing infrastructure. Developing decentralized substrate production and local sourcing networks is essential to reduce risk and stabilize market growth.
Regional Analysis
North America
North America holds a 34% market share driven by growth in commercial mushroom farming and adoption of controlled-environment agriculture. The United States leads substrate demand for button and oyster mushroom production, supported by compost and straw-based blends. Rising interest in functional mushroom varieties, including lion’s mane and maitake, encourages use of enriched sawdust substrates. Local substrate manufacturers benefit from steady availability of agricultural residues and forestry byproducts. The region also sees increased adoption of ready-to-use sterilized substrate blocks among small and urban growers. Strong distribution networks and investment in sustainable farming practices reinforce long-term market growth.
Europe
Europe accounts for a 28% market share, supported by established mushroom cultivation in the Netherlands, Poland, Spain, Italy, and France. Compost and manure-based substrates dominate due to strong button mushroom production. Oyster and specialty mushroom growers use straw and mixed organic materials, aligning with organic certification programs. Sustainability regulations encourage substrate producers to source crop and forestry waste responsibly. Demand for gourmet and medicinal mushrooms increases substrate innovation across small and mid-sized farms. Growth continues as retailers expand offerings of organic and locally grown mushroom products in fresh and processed formats.
Asia Pacific
Asia Pacific holds a 24% market share, driven by large-scale mushroom production in China, India, Japan, and South Korea. Sawdust and agricultural waste substrates support high consumption of shiitake and oyster mushrooms across foodservice and retail channels. Expanding adoption of integrated farming and circular biomass practices strengthens substrate availability. Regional growers focus on improving yield, shelf life, and contamination control through sterilized substrate blocks. Population growth and rising protein demand increase mushroom farming investments, particularly in India and Southeast Asia. Strong government support for agri-business and export-oriented cultivation enhances market expansion.
Latin America
Latin America represents an 8% market share, supported by increasing mushroom production in Brazil, Mexico, Argentina, and Chile. Substrate adoption grows as farms utilize abundant agricultural residues, including sugarcane bagasse, coffee waste, and straw. Oyster mushroom cultivation expands due to low entry cost and strong nutritional positioning among health-conscious consumers. Urban farming and small-scale production contribute to rising demand for ready-to-use substrate kits. Regional supply chains strengthen as agricultural cooperatives incorporate mushroom production into diversified income programs. Ongoing improvements in cold-chain logistics support broader retail distribution of fresh mushrooms.
Middle East & Africa
The Middle East & Africa region holds a 6% market share, driven by growing interest in climate-controlled mushroom farming. Substrate suppliers target markets in the United Arab Emirates, Saudi Arabia, South Africa, and Kenya, where controlled-environment agriculture expands to improve food security. Compost and straw-based substrates support button and oyster mushroom production, while premium sawdust blends serve emerging specialty mushroom growers. Limited substrate raw material availability increases reliance on imported or commercially processed mixes. Regional governments encourage sustainable farming and resource efficiency, supporting long-term substrate market opportunities.
Market Segmentations:
By Substrate Type
- Compost
- Straw
- Sawdust
- Other Organic Substrates
By Mushroom Type
- Button Mushrooms
- Oyster Mushrooms
- Shiitake Mushrooms
- Other Specialty Mushrooms
By Source Material
- Agricultural Waste
- Forestry Byproducts
- Animal Manure
- Mixed Organic Materials
By End Use
- Commercial Mushroom Farming
- Small-Scale/Suburban Mushroom Growers
- Research & Cultivation Laboratories
- Substrate Manufacturers & Distributors
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Mushrooms Substrate market features key players such as Italspawn, Mushroom Substrate Solutions, Amycel Spawn, Mycelia BV, Hirano Mushroom LLC, Agrinoon (Fujian) Biological Co., Ltd, Highline Mushrooms, Aloha Medicinals, Phoratec Mushroom Supplies, and Sylvan Inc. These companies focus on improving substrate formulations that enhance colonization rates, yield consistency, and contamination resistance for button, oyster, shiitake, and specialty mushrooms. Producers expand their presence through collaborations with commercial mushroom farms and controlled-environment cultivation operators. Many focus on compost, straw, and sawdust blends, while some introduce sterilized, ready-to-use substrate blocks for small growers and urban farming markets. Innovation centers on optimizing organic waste utilization and maintaining high substrate microbial quality. Companies pursue supply chain reliability by securing agricultural and forestry residue sources, while geographic expansion targets high-growth markets in Asia Pacific and North America. Growing interest in medicinal and functional mushrooms also supports R&D in enriched substrate formulations.
Key Player Analysis
- Italspawn
- Mushroom Substrate Solutions
- Amycel Spawn
- Mycelia BV
- Hirano Mushroom LLC
- Agrinoon (Fujian) Biological Co., Ltd
- Highline Mushrooms
- Aloha Medicinals
- Phoratec Mushroom Supplies
- Sylvan Inc.
Recent Developments
- In April 2025, Sylvan received a direct investment from Novo Holdings, while KKR remained the majority shareholder, to scale up production capacity, upgrade R&D infrastructure, and deepen substrate/spawn development in Asia.
- In March 2025, Sylvan Inc. began construction of a new R&D facility adjacent to its spawn plant in Huai’an, China, focused on breeding, molecular biology and substrate-formulation research.
- In May 2024, Highline Mushrooms held its Gardener Appreciation Day event at its Crossfield, Alberta, site. During the event, the company distributed free spent-mushroom substrate to local gardeners, demonstrating a substrate by-product reuse initiative.
Report Coverage
The research report offers an in-depth analysis based on Substrate Type, Mushroom Type, Source Material, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Commercial mushroom farming will expand, increasing demand for high-yield substrate blends.
- Ready-to-use sterilized substrate blocks will gain wider adoption among urban and small growers.
- Agricultural and forestry waste utilization will strengthen circular and sustainable substrate production.
- Substrate enrichment will grow to support medicinal and functional mushroom cultivation.
- Automation and laboratory-grade sterilization techniques will improve substrate consistency and contamination control.
- Online distribution and subscription-based substrate supply models will expand market reach.
- Regional manufacturing facilities will increase to reduce substrate transport costs and improve availability.
- Technological research will enhance substrate nutrient balance for higher colonization rates.
- Partnerships between substrate suppliers and commercial mushroom farms will accelerate product development.
- Government support for agri-innovation and alternative farming will boost long-term substrate market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Commercial Mushroom Farming
The global increase in commercial mushroom cultivation, especially for button, oyster, and shiitake varieties, is driving demand for high-performance substrates that enable higher yields, faster colonization, and consistent crop cycles.
Utilization of Agricultural and Forestry Waste
Growing emphasis on circular bioeconomy and sustainability is boosting the use of agricultural residues, sawdust, and manure in substrate production, reducing input costs and supporting eco-friendly farming practices.
Rising Demand for Functional and Medicinal Mushrooms
Consumer interest in health-promoting mushrooms such as shiitake, lion’s mane, and reishi is encouraging substrate innovation, particularly in enriched and traceable blends that enhance bioactive compound content.
Adoption of Ready-to-Use and Sterilized Substrate Blocks
The convenience and contamination control offered by pre-sterilized, ready-to-use substrate blocks are attracting both commercial and small-scale growers, supporting the growth of urban and indoor mushroom farming.
Government Support and Agri-Innovation Initiatives
Policies promoting agricultural diversification, organic farming, and sustainable waste management are fostering investments in advanced substrate formulations and expanding the market’s reach, especially in emerging economies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Mushrooms Substrate market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Mushrooms Substrate market projected to grow between 2025 and 2032?
Which Mushrooms Substrate market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mushrooms Substrate market?
Who are the leading companies in the Mushrooms Substrate market?
Which region commanded the largest share of the Mushrooms Substrate market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Commercial Mushroom Farming
- 1.2.2 Small-Scale/Suburban Mushroom Growers
- 1.2.3 Research & Cultivation Laboratories
- 1.2.4 Substrate Manufacturers & Distributors
- 1.3 By Mushroom Type
- 1.3.1 Button Mushrooms
- 1.3.2 Oyster Mushrooms
- 1.3.3 Shiitake Mushrooms
- 1.3.4 Other Specialty Mushrooms
- 1.4 By Substrate Type
- 1.4.1 Compost
- 1.4.2 Straw
- 1.4.3 Sawdust
- 1.4.4 Other Organic Substrates
- 1.5 By Source Material
- 1.5.1 Agricultural Waste
- 1.5.2 Forestry Byproducts
- 1.5.3 Animal Manure
- 1.5.4 Mixed Organic Materials
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,777.5 million → 2032: USD 4,166.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mushrooms Substrate Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mushrooms Substrate Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mushrooms Substrate Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mushrooms Substrate Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mushrooms Substrate Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mushrooms Substrate Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mushrooms Substrate Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mushrooms Substrate Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,777.5 million → 2032: USD 4,166.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mushrooms Substrate Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial Mushroom Farming
- 12.3.7.2 Small-Scale/Suburban Mushroom Growers
- 12.3.7.3 Research & Cultivation Laboratories
- 12.3.7.4 Substrate Manufacturers & Distributors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Mushroom Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Button Mushrooms
- 12.4.7.2 Oyster Mushrooms
- 12.4.7.3 Shiitake Mushrooms
- 12.4.7.4 Other Specialty Mushrooms
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Substrate Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Compost
- 12.5.7.2 Straw
- 12.5.7.3 Sawdust
- 12.5.7.4 Other Organic Substrates
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Source Material - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Agricultural Waste
- 12.6.7.2 Forestry Byproducts
- 12.6.7.3 Animal Manure
- 12.6.7.4 Mixed Organic Materials
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mushrooms Substrate End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mushrooms Substrate Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mushrooms Substrate Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mushrooms Substrate Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Italspawn
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mushroom Substrate Solutions
- 18.4 Amycel Spawn
- 18.5 Mycelia BV
- 18.6 Hirano Mushroom LLC
- 18.7 Agrinoon (Fujian) Biological Co., Ltd
- 18.8 Highline Mushrooms
- 18.9 Aloha Medicinals
- 18.10 Phoratec Mushroom Supplies
- 18.11 Sylvan Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
