
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
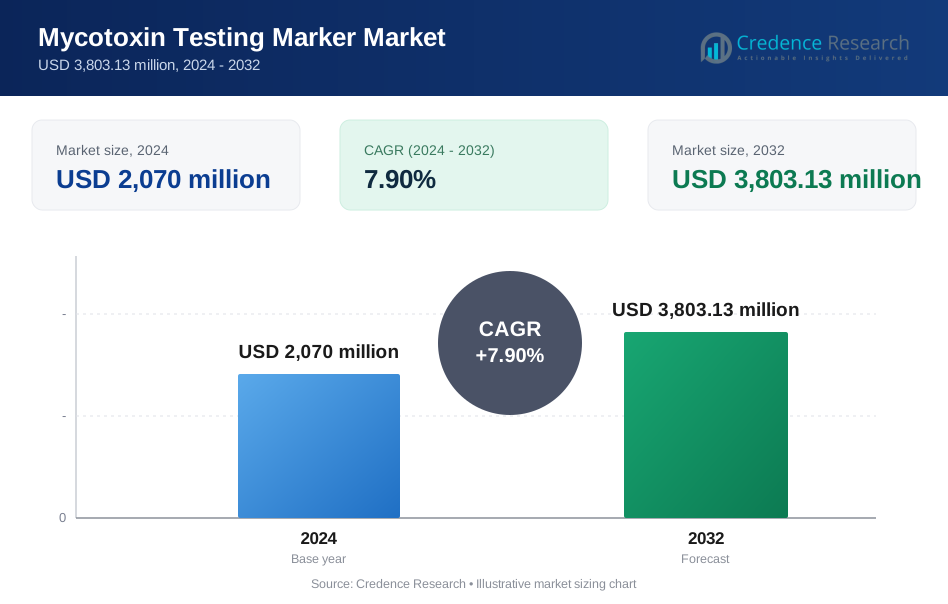
| Mycotoxin Testing Market Size 2024 | USD 2,070 million |
| Mycotoxin Testing Market, CAGR | 7.9%. |
| Mycotoxin Testing Market Size 2032 | USD 3,803.13 million |
Market Overview:
The global Mycotoxin Testing Market is projected to grow from USD 2,070 million in 2024 to USD 3,803.13 million by 2032, at a compound annual growth rate (CAGR) of 7.9%.
The mycotoxin testing market is driven by increasing concerns over food safety and the rising prevalence of mycotoxin contamination in crops and food products due to climate change and improper storage practices. Growing demand for high-quality, toxin-free food and feed, coupled with stringent regulatory standards set by governments and food safety authorities worldwide, is propelling market growth. Advancements in testing technologies, such as the development of faster, more sensitive, and cost-effective detection methods, are further boosting market adoption. Additionally, the expanding global trade of food products and animal feed is fueling the need for reliable mycotoxin testing to ensure compliance with international safety standards. Emerging trends include the integration of automation in testing processes, the rise of rapid testing kits, and increasing investment in R&D to improve detection capabilities for various types of mycotoxins. These factors collectively contribute to the steady growth of the mycotoxin testing market across the food and agricultural industries.
The geographical analysis of the mycotoxin testing market highlights North America, Europe, Asia-Pacific, and the Rest of the World (RoW) as key regions. North America holds the largest market share, driven by stringent food safety regulations, followed by Europe, where strong regulatory frameworks and increasing demand for organic products fuel growth. Asia-Pacific is experiencing the fastest growth, with rising food safety concerns and expanding food processing industries in countries like China, India, and Japan. The RoW, including Latin America, the Middle East, and Africa, is gradually expanding due to increasing agricultural activities and export demands. Key players, including SGS SA, Eurofins Scientific SE, Romer Labs Division Holding GmbH, Intertek Group plc, and ALS Limited, are strengthening their presence across these regions through advanced testing solutions and compliance with global safety standards.
Market Insights:
- The global mycotoxin testing market is projected to grow from USD 2,070 million in 2024 to USD 3,803.13 million by 2032, at a CAGR of 7.9%.
- Increasing concerns over food safety and the rising prevalence of mycotoxin contamination due to climate change and poor storage practices are driving market growth.
- Demand for high-quality, toxin-free food and feed, along with stringent regulatory standards worldwide, is propelling market expansion.
- Advancements in testing technologies, including faster, more sensitive, and cost-effective methods, are increasing market adoption.
- The global trade of food products and animal feed fuels the need for reliable mycotoxin testing to comply with international safety standards.
- Emerging trends include automation in testing processes, the rise of rapid testing kits, and increased investment in R&D to enhance detection capabilities.
- Key regions driving the market are North America, Europe, Asia-Pacific, and the Rest of the World, with North America holding the largest market share in 2024.
Market Drivers:
Stringent Food Safety Regulations:
One of the key drivers of the mycotoxin testing market is the stringent regulatory framework governing food safety standards worldwide. Governments and international food safety authorities, such as the Food and Agriculture Organization (FAO) and the World Health Organization (WHO), have established strict guidelines for acceptable levels of mycotoxins in food and feed products. For instance, the European Union has implemented one of the world's most comprehensive regulations, setting strict limits on mycotoxins such as aflatoxins and ochratoxins in food and feed. These regulations compel food manufacturers, processors, and distributors to comply with safety standards, creating a growing demand for accurate and efficient mycotoxin testing solutions.
Rising Awareness of Foodborne Illnesses:
Increasing awareness of the health risks associated with mycotoxins is also driving the market. Mycotoxins, which can contaminate crops, animal feed, and food products, pose serious health hazards such as carcinogenic, hepatotoxic, and immunosuppressive effects. As consumers become more informed about foodborne illnesses and the potential dangers of contaminated products, the demand for rigorous mycotoxin testing is rising. This trend is particularly pronounced in regions with growing consumer awareness about food quality and safety.
Globalization of Food Trade:
The globalization of the food trade has led to an increased demand for standardized testing practices across different regions. As food products and animal feed are traded internationally, compliance with varying food safety standards in different countries becomes critical. For instance, countries like the United States and China require imported food products to comply with their respective food safety regulations, driving the need for mycotoxin testing in export markets. Mycotoxin testing ensures that food products meet the safety requirements of multiple markets, minimizing the risk of contamination and potential trade disputes. This trend is further fueling the need for reliable and consistent mycotoxin testing methods.
Technological Advancements in Testing:
Advancements in testing technologies are another key driver of market growth. Innovations in detection methods, such as the development of faster, more sensitive, and cost-effective testing solutions, are making mycotoxin testing more accessible to a wider range of industries. Automated testing systems and rapid test kits are gaining popularity, providing efficient and accurate results, which helps food producers maintain compliance with regulatory standards.
Market Trends:
Adoption of Rapid Testing Methods:
A major trend in the mycotoxin testing market is the growing adoption of rapid testing methods. Traditional laboratory-based tests, while accurate, can be time-consuming. To meet the demand for quicker results, rapid test kits and portable devices have gained significant traction. For instance, portable lateral flow test kits from Romer Labs allow food producers to test for contamination on-site, delivering results within minutes. These methods allow for on-site testing, providing fast and reliable results, which helps food producers and processors quickly assess contamination levels and take timely corrective actions, reducing potential delays in production and distribution.
Integration of Automation in Testing:
Automation is increasingly being integrated into mycotoxin testing processes. Automated testing systems streamline the detection of mycotoxins by reducing human error and enhancing the accuracy and efficiency of results. This trend is especially prevalent in large-scale food processing industries where high throughput and consistent quality control are essential. Automated systems enable laboratories and testing facilities to manage larger volumes of samples with greater precision, improving the overall reliability of testing outcomes.
Rising Demand for Multi-Mycotoxin Detection:
The demand for multi-mycotoxin detection methods is growing as food and feed products are increasingly susceptible to contamination by multiple types of mycotoxins. Advanced testing technologies now offer solutions that can simultaneously detect various mycotoxins in a single test, improving the efficiency of the testing process. For instance, LC-MS/MS (liquid chromatography-mass spectrometry) systems from companies like SCIEX can simultaneously identify and quantify multiple mycotoxins in complex samples with exceptional accuracy. This trend is particularly valuable in industries where diverse raw materials are used, such as animal feed and grain processing, where contamination risks from multiple mycotoxins are higher.
Increased Investment in Research and Development:
There is a notable increase in investment in research and development to enhance mycotoxin detection technologies. Companies and research institutions are focused on developing more sensitive, faster, and cost-effective testing solutions. Emerging technologies, such as biosensors and molecular testing, are being explored to further improve accuracy and reduce testing time, driving innovation and shaping the future of the mycotoxin testing market.
Market Challenges Analysis:
High Cost of Testing Technologies:
One of the major challenges in the mycotoxin testing market is the high cost of advanced testing technologies. Many small and medium-sized food producers and processors, particularly in developing regions, struggle to invest in expensive testing equipment and services. Although technological advancements have improved testing efficiency and accuracy, the upfront costs of implementing sophisticated detection systems remain prohibitive for smaller enterprises. In addition to the cost of equipment, there are ongoing expenses associated with regular testing, maintenance, and the need for skilled personnel to operate the systems effectively. This financial burden limits the widespread adoption of mycotoxin testing, particularly in regions where access to capital and resources is constrained. For instance, Aflatoxin testing, testing corn for aflatoxin in southeast Texas can cost $20 to $30 per test, which equates to $2-3 per acre when testing one test per truckload of 30,000 to 60,000 pounds of commodity. The high cost of compliance can also put smaller businesses at a competitive disadvantage compared to larger, more established companies. Overcoming these cost-related barriers would require the development of more affordable testing solutions, greater subsidies, or financial assistance programs to support small-scale food producers and ensure food safety across all market segments.
Lack of Standardization Across Regions:
Another critical challenge in the mycotoxin testing market is the lack of standardized regulatory frameworks across different regions. While some countries have strict regulations and well-defined limits for mycotoxin contamination in food and feed, others have less stringent or ambiguous guidelines. This inconsistency complicates the testing processes for companies involved in international food trade, requiring them to navigate multiple, often conflicting, regulatory environments. In addition, the absence of uniform testing methods across regions can lead to discrepancies in results, further complicating efforts to maintain consistent food safety standards. This variability increases the risk of non-compliance, product recalls, and trade disputes, particularly for businesses operating in global markets. For companies engaged in exporting food products, the challenge of meeting diverse regulatory standards can be time-consuming and costly. To address this issue, greater collaboration between regulatory bodies and international organizations is needed to harmonize mycotoxin testing standards, ensuring a more consistent and reliable global food safety framework.
Market Opportunities:
The mycotoxin testing market presents significant growth opportunities driven by the increasing demand for food safety and quality assurance across global supply chains. As awareness of mycotoxin contamination rises, particularly in developing regions, there is a growing need for more accessible and cost-effective testing solutions. Companies that can develop affordable and portable testing kits with rapid and accurate results will have a competitive advantage in expanding into emerging markets where food safety infrastructure is still developing. Additionally, the expansion of the global food trade creates an opportunity for mycotoxin testing providers to offer comprehensive solutions that meet the varied regulatory requirements across different regions, helping businesses ensure compliance and reduce the risk of trade disruptions.
Another opportunity lies in the advancement of technology, particularly in the development of multi-mycotoxin detection systems and automation in testing processes. With increasing demand for high-throughput and efficient testing, particularly in large-scale food production and processing industries, companies that innovate in automated and integrated testing systems will see significant demand. The rise in demand for organic and clean-label products also fuels the need for more stringent testing, opening avenues for specialized mycotoxin testing solutions targeted at organic producers. Furthermore, increased investment in research and development to improve the sensitivity, speed, and ease of testing methods will enable businesses to capture a larger share of this growing market, particularly as food safety regulations continue to tighten globally.
Market Segmentation Analysis:
By Type
The mycotoxin testing market is segmented by type, which includes aflatoxins, ochratoxins, fumonisins, zearalenone, and trichothecenes. Aflatoxins hold the largest share due to their widespread presence in crops such as corn, peanuts, and grains. However, demand for testing other mycotoxins, like ochratoxins and fumonisins, is increasing as awareness of their health risks grows, particularly in food and feed production.
By End User
The end user segment includes food manufacturers, feed producers, testing laboratories, and regulatory bodies. Food manufacturers represent the largest market share due to the need for rigorous testing to ensure product safety and regulatory compliance. Testing laboratories also play a crucial role as they provide specialized testing services across industries. Feed producers are experiencing growing demand for mycotoxin testing to maintain animal health and meet safety standards in livestock feed.
Segments:
Based on Type:
- Aflatoxin
- Ochratoxins
- Deoxynivalenol
- Fumonisins
- Zearalenone
- Trichothecene
- Patulin
- Others
Based on End User:
- Food and Beverages
-
- Cereals, Grains and Pulses
- Dairy Products
- Nuts and Seeds
- Meat and Poultry
- Baby Food
- Beverages
- Bakery and Confectionery
- Snacks and Others
- Animal Feed
- Pharmaceuticals
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is projected to hold a significant share of the mycotoxin testing market, with an expected market share of 35% in 2024. The region’s dominance can be attributed to the stringent food safety regulations implemented by organizations such as the Food and Drug Administration (FDA) and the U.S. Department of Agriculture (USDA). The high prevalence of mycotoxin contamination in crops like corn, wheat, and peanuts, along with growing consumer awareness of foodborne illnesses, drives the demand for mycotoxin testing in the U.S. and Canada. Additionally, the presence of advanced testing technologies and well-established food safety infrastructure further strengthens the market in this region. The rise in export activities, requiring compliance with international food safety standards, also contributes to the growth of the mycotoxin testing market in North America.
Europe
Europe is anticipated to capture 30% of the mycotoxin testing market share in 2024. The region's strong regulatory framework, driven by organizations such as the European Food Safety Authority (EFSA), plays a significant role in boosting market demand. Countries like Germany, France, and the U.K. are key contributors, with a well-established food and agricultural sector that requires regular mycotoxin testing to ensure compliance with stringent food safety regulations. The European market is further propelled by the increasing awareness of foodborne risks and the growing emphasis on organic and non-GMO food products, which require more rigorous testing to guarantee safety. Additionally, the region’s extensive trade networks with other continents necessitate strict adherence to international safety standards, supporting the expansion of the mycotoxin testing market.
Asia-Pacific:
The Asia-Pacific region is expected to witness the fastest growth in the mycotoxin testing market, with a projected market share of 20% in 2024. Countries like China, India, Japan, and Australia are experiencing increased demand for mycotoxin testing due to rising food safety concerns, rapid urbanization, and the expansion of the food processing industry. The region’s growing export of food products to Europe and North America, which requires compliance with stringent safety standards, further fuels the demand for advanced mycotoxin testing. As awareness of foodborne risks grows, government initiatives to tighten regulations on food safety are also driving the market. Additionally, the increasing use of animal feed in livestock production creates additional demand for mycotoxin testing in this region.
Rest of the World (RoW):
The Rest of the World, including regions like Latin America, the Middle East, and Africa, is expected to hold a market share of 15% in 2024. While these regions are still developing their food safety infrastructure, growing awareness of mycotoxin contamination risks and increasing agricultural activities are boosting demand for mycotoxin testing. Brazil and Argentina, in particular, are major exporters of agricultural products and animal feed, which necessitate compliance with global food safety standards. The RoW market is also supported by initiatives from international organizations to improve food safety measures in developing countries.
Key Player Analysis:
- Eurofins Scientific SE
- Romer Labs Division Holding GmbH
- SGS SA
- EMSL Analytical, Inc.
- AltaBioscience
- Charm Sciences, Inc.
- Intertek Group plc.
- Belcosta Labs, Inc.
- Trilogy Analytical Laboratories
- ALS Limited
- Mérieux NutriSciences
- ELISA Technologies, Inc.
Competitive Analysis:
The mycotoxin testing market is highly competitive, with leading players such as SGS SA, Eurofins Scientific SE, Romer Labs Division Holding GmbH, Intertek Group plc, Charm Sciences, Inc., ALS Limited, and Mérieux NutriSciences playing a dominant role. These companies compete primarily based on their extensive portfolios of testing solutions, technological advancements, and global reach. Their strong presence in food safety testing, combined with advanced laboratories and R&D investments, enables them to meet the increasing demand for accurate and rapid mycotoxin detection. Additionally, companies like EMSL Analytical, Inc., Trilogy Analytical Laboratories, and AltaBioscience are focusing on expanding their specialized testing services and developing cost-effective solutions to cater to the growing market. Strategic mergers, acquisitions, and partnerships further enhance the competitive landscape, allowing these players to strengthen their market positions and broaden their customer base. Continuous innovation in testing technologies and a commitment to meeting global regulatory standards keep these companies at the forefront of the mycotoxin testing market.
Recent Developments:
- In May 2023, Symbio Labs in Australia enhanced its capabilities to detect a range of mycotoxins at extremely low concentrations, reaching parts per billion. This development positions Symbio Labs as one of the few in Australia able to promptly and accurately identify mycotoxins in grain, finished feed, and food products.
- In March 2023, Bureau Veritas opened its fifth Microbiology Laboratory in Winnipeg, Manitoba. The laboratory provides Rapid Pathogen testing (E. coli O157:H7, Salmonella, and Listeria) as well as indicators like Total Plate Count, Yeast & Mold. This expansion bolstered Bureau Veritas's food testing and certification business in North America.
- In January 2024, Creative Diagnostics introduced new reagents for aflatoxins B1/M1 ELISA Kits, Aflatoxin Total ELISA Kits, and Aflatoxin B1 Screen Tests, strengthening their product lineup for food and feed toxicology analysis.
Market Concentration & Characteristics:
The mycotoxin testing market is characterized by a moderately high level of market concentration, with a few dominant global players holding significant shares. Companies such as SGS SA, Eurofins Scientific SE, ALS Limited, and Romer Labs Division Holding GmbH lead the market due to their strong global presence, advanced testing technologies, and comprehensive service offerings. These market leaders benefit from well-established infrastructures, extensive R&D capabilities, and regulatory expertise, enabling them to cater to the growing demand for reliable mycotoxin detection across various industries. Smaller players and new entrants, while contributing to market diversity, often face challenges in scaling up due to high initial costs and competition from established companies. The market's growth is driven by technological advancements, the increasing global demand for toxin-free food, and the need for compliance with stringent food safety regulations, fostering innovation and competition within the industry.
Report Coverage:
The research report offers an in-depth analysis based on Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The increasing global focus on food safety will continue to drive the demand for mycotoxin testing.
- Technological advancements will make testing methods faster, more accurate, and cost-effective.
- The rise in global food trade will require more stringent mycotoxin testing to meet international safety standards.
- Automation in testing processes will become more prevalent, improving efficiency across laboratories.
- Growing awareness of mycotoxin-related health risks will increase the need for rigorous testing in food and feed industries.
- Asia-Pacific is expected to witness strong growth due to rising food safety concerns and expanding food processing industries.
- There will be increased investment in research and development to enhance detection capabilities for various mycotoxins.
- Government regulations will continue to tighten, prompting more comprehensive testing across different regions.
- Rapid test kits will gain popularity for their speed and convenience in detecting mycotoxins.
- The expansion of global agricultural activities will create additional demand for reliable mycotoxin testing solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mycotoxin Testing Market?
What factors are driving the growth of the Mycotoxin Testing Market?
What are some challenges faced by the Mycotoxin Testing Market?
Who are the major players in the Mycotoxin Testing Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mycotoxin Testing Marker Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mycotoxin Testing Marker Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,070 million → 2032: USD 3,803.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mycotoxin Testing Marker Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mycotoxin Testing Marker Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mycotoxin Testing Marker Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mycotoxin Testing Marker Market Drivers
- 3.3 Mycotoxin Testing Marker Market Restraints & Challenges
- 3.4 Mycotoxin Testing Marker Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mycotoxin Testing Marker Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mycotoxin Testing Marker Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mycotoxin Testing Marker category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mycotoxin Testing Marker Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mycotoxin Testing Marker Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mycotoxin Testing Marker market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mycotoxin Testing Marker Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mycotoxin Testing Marker Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mycotoxin Testing Marker Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mycotoxin Testing Marker (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mycotoxin Testing Marker Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mycotoxin Testing Marker Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mycotoxin Testing Marker Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mycotoxin Testing Marker Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mycotoxin Testing Marker Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mycotoxin Testing Marker Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mycotoxin Testing Marker Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mycotoxin Testing Marker Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mycotoxin Testing Marker Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
