
Market Overview:
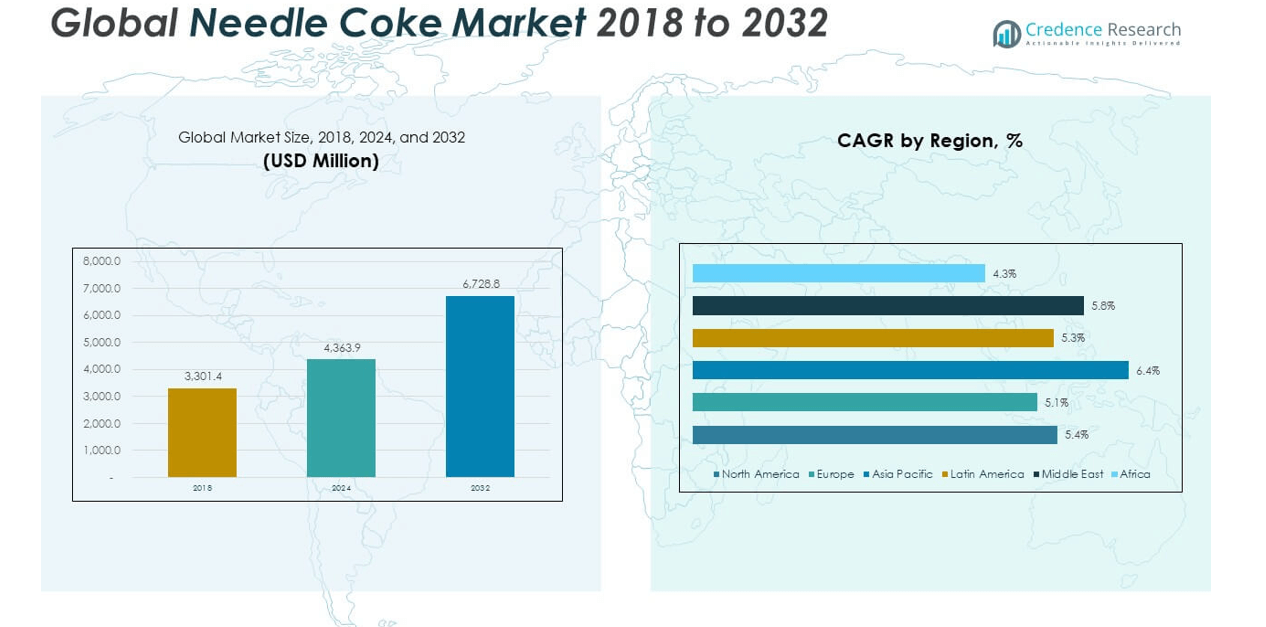
The Global Needle Coke Market size was valued at USD 3,301.4 million in 2018 to USD 4,363.9 million in 2024 and is anticipated to reach USD 6,728.8 million by 2032, at a CAGR of 5.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Needle Coke Market Size 2024 | USD 4,363.9 million |
| Needle Coke Market, CAGR | 5.62% |
| Needle Coke Market Size 2032 | USD 6,728.8 million |
The market is driven by rising demand for ultra-high-power graphite electrodes used in steel production through electric arc furnaces. Increasing adoption of lithium-ion batteries in electric vehicles further fuels the need for needle coke, as it is a critical raw material for synthetic graphite anodes. Growth in electronics and energy storage systems also supports demand. Technological advancements in refining and production processes enhance quality and cost-efficiency, encouraging widespread adoption. Stringent environmental regulations in steelmaking and battery industries continue to accelerate the shift toward needle coke utilization.
Geographically, Asia-Pacific dominates the market, led by China, India, and Japan due to strong steelmaking and battery manufacturing capacity. North America holds a significant share supported by established refining infrastructure and electric vehicle adoption. Europe continues to grow steadily, driven by energy transition policies and demand for advanced batteries. Emerging markets in Latin America and the Middle East show potential, with growing steel production and industrial development fostering future opportunities.
Market Insights:
- The Global Needle Coke Market was valued at USD 3,301.4 million in 2018, reached USD 4,363.9 million in 2024, and is projected to hit USD 6,728.83 million by 2032, growing at a CAGR of 5.62%.
- Asia Pacific held the largest share at 31.7% in 2024, followed by Europe at 26% and North America at 23.3%, driven by strong steelmaking capacity, EV adoption, and advanced refining infrastructure.
- Asia Pacific is also the fastest-growing region, supported by industrial expansion in China, India, Japan, and South Korea alongside rapid growth in battery manufacturing.
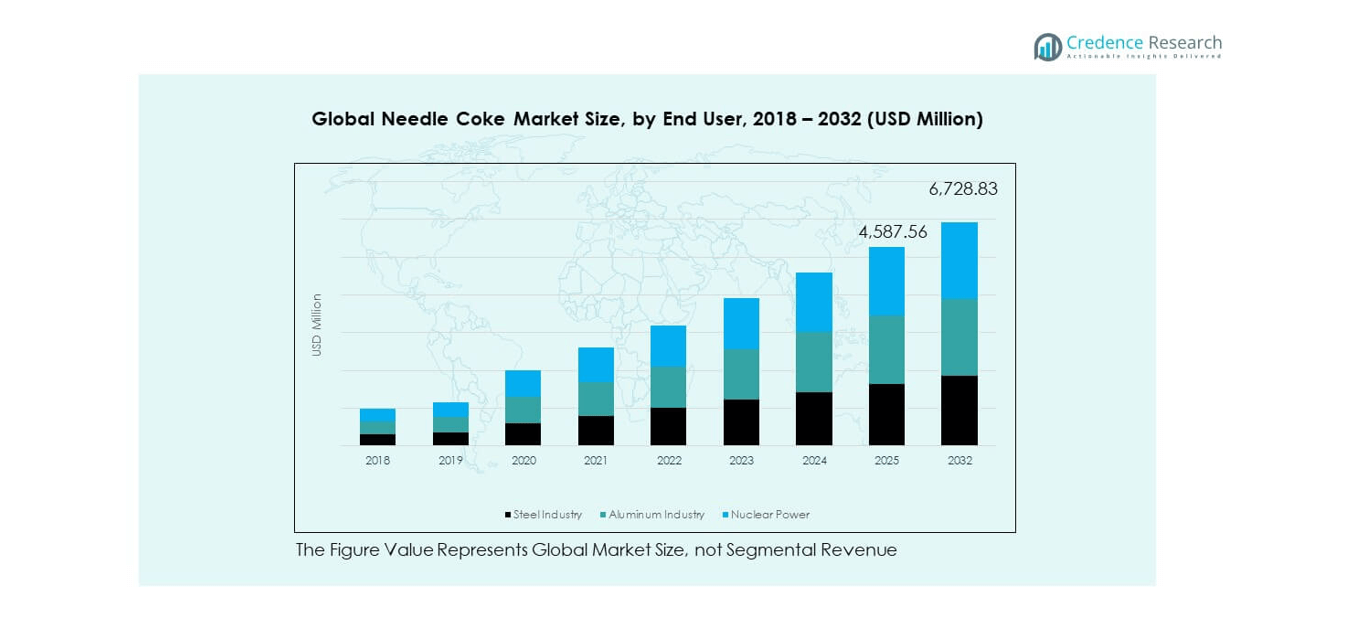
- In 2024, the steel industry accounted for around 36% of end-user demand, supported by growing adoption of electric arc furnaces.
- The aluminum industry and nuclear power sectors contributed about 34% and 30% respectively, reflecting steady demand from energy-intensive industries and specialized applications.
Market Drivers:
Rising Demand for Graphite Electrodes in Steel Manufacturing:
The Global Needle Coke Market benefits from strong demand for graphite electrodes, which are essential in electric arc furnace-based steelmaking. Growth in infrastructure and construction projects drives the need for steel, increasing electrode consumption. Needle coke offers superior properties such as low thermal expansion and high conductivity, making it the preferred choice for ultra-high-power electrodes. Electric arc furnaces reduce carbon emissions compared to blast furnaces, creating further adoption. It continues to support sustainability goals in global steel industries. Rising energy efficiency requirements also push manufacturers to prefer needle coke-based electrodes. The ongoing shift in emerging economies toward modern steelmaking technologies strengthens demand. These factors establish a stable base for needle coke expansion.
- For instance, GrafTech International’s 38% sales volume increase in the US market for Q2 2025 is confirmed by official company earnings releases and financial news platforms.
Growing Need for Lithium-Ion Batteries in Electric Vehicles:
The rising penetration of electric vehicles creates steady demand for lithium-ion batteries, where needle coke forms a key raw material for synthetic graphite anodes. The Global Needle Coke Market experiences growth as automotive manufacturers expand EV production globally. Governments promote EV adoption through subsidies and emission standards, boosting battery demand. Needle coke provides high purity and strong structural properties, improving battery performance. It enhances energy density and ensures durability for longer driving ranges. Increasing investments in battery gigafactories also drive higher needle coke consumption. Rapid technological progress in battery chemistry reinforces its role. The EV boom makes needle coke vital in future transportation energy systems.
- For instance, POSCO Future M’s July 2025 supply contract of natural graphite anode materials to a major Japanese battery manufacturer is reported in verified press releases and reputable industry news.
Expanding Application in Energy Storage Systems and Electronics:
Energy storage technologies are becoming critical in renewable energy integration, and needle coke contributes to improved storage capacity. The Global Needle Coke Market sees consistent demand from the electronics industry as well. Portable devices, laptops, and smartphones require high-performance batteries, where needle coke-based graphite ensures efficiency. Renewable energy deployment across solar and wind creates demand for grid-scale storage, increasing the need for needle coke. It delivers stability and extended lifespan in advanced storage systems. Smart grids and distributed energy solutions further strengthen market adoption. Rising consumer demand for compact electronics adds another growth factor. Such diverse applications ensure long-term stability for the market.
Technological Advancements and Refining Innovations Supporting Quality:
Refiners are adopting advanced technologies to improve the quality and efficiency of needle coke production. The Global Needle Coke Market benefits from enhanced yield and cost optimization through process innovation. Research initiatives aim to improve purity levels and minimize environmental impact during production. It strengthens the supply chain by supporting consistency in output. New refining methods reduce dependency on traditional coking processes, boosting flexibility. Industrial collaborations and R&D efforts accelerate development of sustainable production pathways. Such advancements reduce risks of supply disruption while meeting evolving quality standards. These technological improvements help ensure future resilience and competitive positioning.
Market Trends:
Shift Toward Green Steel and Decarbonization Strategies:
The Global Needle Coke Market aligns with global efforts toward decarbonization, as green steel initiatives gain traction. Electric arc furnaces dominate cleaner steel production methods, driving steady needle coke adoption. Companies in developed regions are investing in low-carbon steel plants. It supports the transition toward more sustainable production, reducing greenhouse gas emissions. Needle coke’s role in high-efficiency graphite electrodes makes it a preferred choice in this context. Policies promoting carbon-neutral steel accelerate demand. Collaborations between governments and steelmakers add momentum. These sustainability trends position needle coke as a key material in green manufacturing.
- For instance, industry reports and market analysis document PetroChina's Jinzhou Petrochemical completing an expansion to increase its needle coke capacity to 350,000 tons annually in late 2024.
Integration of Needle Coke into Advanced Battery Technologies:
Battery producers are integrating needle coke into advanced designs for improved performance and safety. The Global Needle Coke Market expands as manufacturers develop high-capacity energy storage devices. Emerging chemistries focus on enhancing cycle life and energy density with stable anode materials. It provides structural integrity, supporting next-generation lithium-ion and beyond-lithium solutions. Research in solid-state batteries also evaluates its application. Increased demand for fast-charging and durable batteries strengthens adoption. Strategic partnerships between chemical companies and automakers enhance production scale. These innovations in battery applications reinforce long-term demand for needle coke.
- For instance, Indian Oil Corporation’s approved Rs 1,268 crore investment in 2025 for a calcined needle coke production unit at Paradip refinery is substantiated by news articles and company announcements.
Rising Investments in Recycling and Circular Economy Approaches:
Sustainability trends encourage the recycling of graphite electrodes and needle coke-based products. The Global Needle Coke Market benefits from circular economy practices adopted by leading steel and battery companies. Recycling lowers raw material dependency and reduces carbon footprint. It supports resource efficiency and ensures long-term material availability. Firms invest in electrode recycling technologies to improve recovery yields. Governments also promote recycling regulations in battery supply chains. Industry initiatives demonstrate commitment to reducing waste and enhancing sustainability. Such approaches align with broader environmental goals and provide resilience against resource shortages.
Expansion of Production Facilities and Regional Supply Chain Diversification:
Producers are expanding capacity to meet rising demand across steel, battery, and electronics sectors. The Global Needle Coke Market witness’s regional diversification with new plants in Asia-Pacific, North America, and the Middle East. Companies aim to secure supply chains and reduce import reliance. It creates stability in meeting local industrial requirements. Governments support domestic production projects to strengthen industrial competitiveness. Strategic alliances between refiners and steelmakers improve efficiency. Technological upgrades in refineries enable large-scale output. These expansions ensure secure global supply and market balance for the long term.
Market Challenges Analysis:
High Production Costs and Limited Feedstock Availability:
The Global Needle Coke Market faces challenges due to the high costs of production and limited feedstock availability. Premium coking feedstock remains scarce, pushing manufacturers to compete for raw materials. It creates volatility in supply chains and affects production stability. Rising energy costs further pressure margins for producers. Regulatory restrictions on petroleum refining complicate operations. Dependence on oil-derived feedstocks makes the industry vulnerable to crude market fluctuations. Companies attempt to balance efficiency with environmental compliance, adding complexity. These cost pressures limit market accessibility for smaller players.
Environmental Regulations and Supply-Demand Imbalance Risks:
Stringent environmental standards present challenges for producers across regions. The Global Needle Coke Market experiences rising scrutiny of emissions and waste management practices. It compels manufacturers to invest heavily in compliance systems. Slow capacity expansion versus demand growth risks creating shortages. Battery and steel sectors increase consumption faster than supply scalability. This imbalance may push prices upward, straining downstream industries. Unpredictable trade policies and regional supply restrictions add to instability. Producers must adapt strategies to meet compliance while maintaining cost efficiency. These dynamics create uncertainty in long-term planning.
Market Opportunities:
Rising Demand from Electric Vehicles and Energy Storage Expansion:
The Global Needle Coke Market has strong opportunities due to EV expansion and renewable energy storage. Growing demand for high-performance lithium-ion batteries continues to push adoption. It ensures strong growth prospects in both automotive and stationary storage markets. Increasing investments in charging infrastructure also support battery demand. Policies promoting zero-emission mobility encourage long-term consumption. Expanding battery production plants further strengthen the outlook. Opportunities remain strong as energy storage systems become integral to sustainable power grids.
Emergence of New Refining Technologies and Regional Expansion:
Technological advances create opportunities for improving yield and quality in needle coke production. The Global Needle Coke Market benefits from regional expansion projects aimed at reducing import dependency. It ensures supply chain resilience and cost optimization. Collaboration between refiners and governments accelerates project execution. Emerging markets invest in large-scale steel and battery industries, creating demand centers. Producers focusing on sustainable refining practices strengthen competitiveness. These factors open growth avenues and reinforce long-term market potential.
Market Segmentation Analysis:
By Type
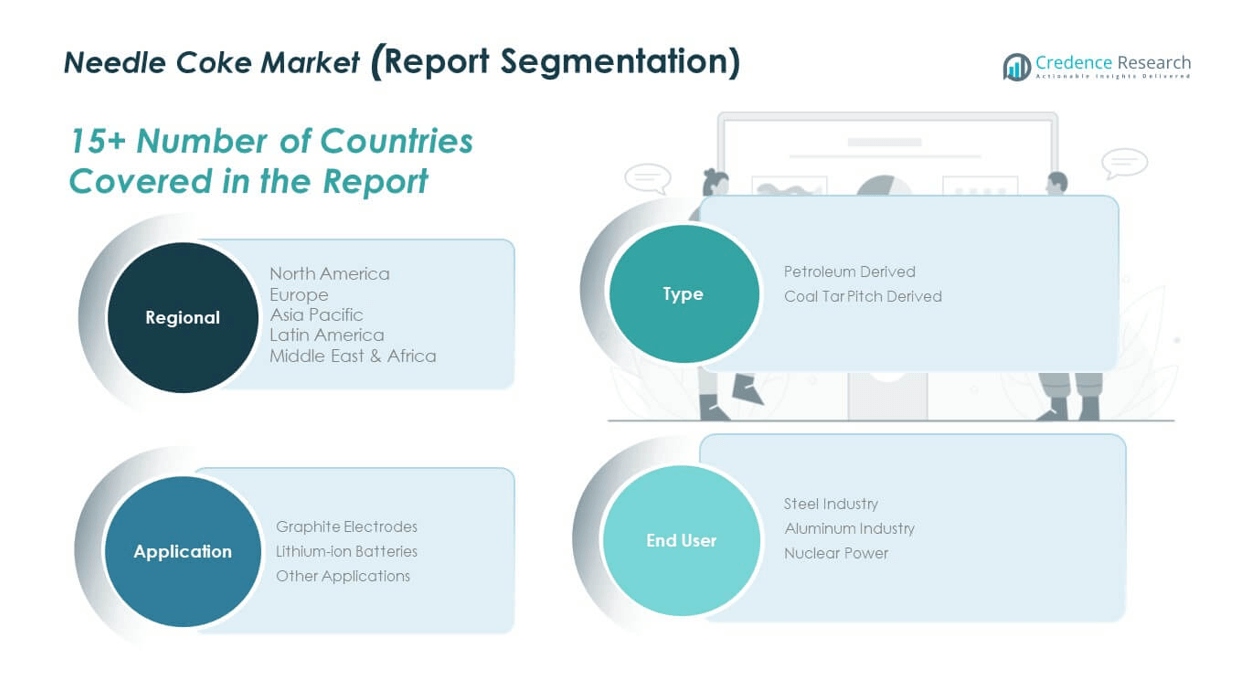
The Global Needle Coke Market is segmented into petroleum derived and coal tar pitch derived categories. Petroleum-derived needle coke dominates due to consistent availability of petroleum feedstock and advanced refining technologies. It delivers higher purity and uniform quality, making it preferred for premium graphite electrodes and high-capacity batteries. Coal tar pitch-derived needle coke holds a steady share, driven by cost advantages and utilization in regions with coal-based industries. It continues to support steelmaking applications, though environmental concerns limit expansion potential.
- For instance, Shanxi Hongte Coal Chemical Co. Ltd suspended its needle coke price quotations in 2025 amid market shifts, highlighting challenges in coal tar pitch-derived coke production.
By Application
The market is divided into graphite electrodes, lithium-ion batteries, and other applications. Graphite electrodes remain the largest segment, with demand driven by electric arc furnace-based steelmaking. It benefits from growing adoption of energy-efficient and lower-emission processes. Lithium-ion batteries represent the fastest-growing segment, supported by global electric vehicle expansion and rising energy storage deployment. Other applications include specialty carbon materials for nuclear and aerospace industries, where performance reliability drives niche demand.
- For instance, although GrafTech International increased its sales volume in the second quarter of 2025, lower average selling prices led to reduced net sales and a wider net loss, illustrating ongoing market pressures despite a sustained high demand for graphite electrodes in steelmaking.
By End User
Key end users include steel industry, aluminum industry, and nuclear power. The steel industry dominates consumption, relying on needle coke for ultra-high-power graphite electrodes. It remains critical for construction and infrastructure growth worldwide. The aluminum industry uses needle coke-based carbon anodes, contributing to steady demand. The nuclear power sector adopts needle coke in high-specification graphite components, ensuring safety and efficiency in reactor applications. Each segment underpins the diverse and long-term relevance of needle coke across industries.
Segmentation:
By Type
- Petroleum Derived
- Coal Tar Pitch Derived
By Application
- Graphite Electrodes
- Lithium-ion Batteries
- Other Applications
By End User
- Steel Industry
- Aluminum Industry
- Nuclear Power
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Global Needle Coke Market size was valued at USD 781.44 million in 2018 to USD 1,018.54 million in 2024 and is anticipated to reach USD 1,540.90 million by 2032, at a CAGR of 5.4% during the forecast period. North America holds about 23.3% of the global market share in 2024. The region benefits from strong steel production and established refining capacity. The U.S. leads consumption, driven by demand for graphite electrodes in electric arc furnaces and expanding electric vehicle battery manufacturing. Canada contributes steadily with industrial growth and energy projects, while Mexico shows potential through rising steel capacity. It gains support from policies promoting sustainable manufacturing and energy storage adoption. Strategic investments in battery plants further stimulate demand. North America continues to position itself as a hub for advanced carbon materials.
Europe
The Europe Global Needle Coke Market size was valued at USD 887.75 million in 2018 to USD 1,138.11 million in 2024 and is anticipated to reach USD 1,682.21 million by 2032, at a CAGR of 5.1% during the forecast period. Europe accounts for about 26% of the global market share in 2024. The region is shaped by strong demand for sustainable steelmaking and advanced battery technologies. Germany, France, and the UK remain key markets, driven by industrial capacity and EV adoption. It benefits from EU initiatives supporting decarbonization and renewable integration. Energy transition goals increase the importance of energy storage, creating higher demand for needle coke. Regional producers also strengthen capacity with cleaner refining practices. The focus on green steel and battery innovation makes Europe a stable and innovation-driven market.
Asia Pacific
The Asia Pacific Global Needle Coke Market size was valued at USD 998.02 million in 2018 to USD 1,383.54 million in 2024 and is anticipated to reach USD 2,265.60 million by 2032, at a CAGR of 6.4% during the forecast period. Asia Pacific dominates with nearly 31.7% of the global market share in 2024. China leads consumption due to its vast steelmaking industry and growing EV battery capacity. Japan and South Korea contribute significantly with strong electronics and automotive sectors. India shows robust growth potential, supported by infrastructure expansion and renewable energy projects. It benefits from large-scale graphite electrode production and rising lithium-ion battery demand. Southeast Asia emerges as an upcoming hub for industrial development. Regional governments support energy-efficient industries, ensuring consistent consumption. Asia Pacific remains the primary growth engine for the global market.
Latin America
The Latin America Global Needle Coke Market size was valued at USD 293.83 million in 2018 to USD 381.84 million in 2024 and is anticipated to reach USD 575.32 million by 2032, at a CAGR of 5.3% during the forecast period. Latin America represents about 8.7% of the global market share in 2024. Brazil leads regional demand, driven by steel production and automotive growth. Argentina supports consumption through industrial activity, while other countries expand capacity gradually. It benefits from rising investment in infrastructure and construction projects. Increasing adoption of electric arc furnaces boosts electrode demand. Energy storage applications remain limited but show future potential. Regional supply chains strengthen through imports from global producers. Latin America offers steady growth opportunities within the global market.
Middle East
The Middle East Global Needle Coke Market size was valued at USD 223.84 million in 2018 to USD 298.12 million in 2024 and is anticipated to reach USD 464.29 million by 2032, at a CAGR of 5.8% during the forecast period. The region accounts for about 6.8% of the global market share in 2024. It benefits from expanding steel production and industrial diversification programs. GCC countries invest heavily in infrastructure, raising demand for graphite electrodes. Turkey also contributes with its growing steel industry. Energy transition policies encourage demand for battery technologies, though still in early stages. Refinery expansion projects support localized supply opportunities. Regional focus on reducing import dependency strengthens long-term stability. The Middle East emerges as a competitive participant in the global market.
Africa
The Africa Global Needle Coke Market size was valued at USD 116.54 million in 2018 to USD 143.76 million in 2024 and is anticipated to reach USD 200.52 million by 2032, at a CAGR of 4.3% during the forecast period. Africa holds about 3.3% of the global market share in 2024. South Africa leads consumption, supported by steel production and industrial activity. Egypt follows with infrastructure-driven demand, while other regions remain underdeveloped. It relies heavily on imports to meet consumption needs. Slow adoption of electric arc furnaces limits demand expansion. Energy storage and EV adoption are at an early stage but hold future potential. Rising industrialization and urban development will gradually increase usage. Africa remains a small but evolving segment in the global market landscape.
Key Player Analysis:
- Baosteel Group
- China National Petroleum Corporation (CNPC)
- ENEOS Corporation
- GrafTech International
- Indian Oil Corporation
- Nippon Steel Corporation
- POSCO Future M
- Shanxi Hongte Coal Chemical Co. Ltd.
- Tokai Carbon Co., Ltd.
- Sinopec
- Other Key Players
Competitive Analysis:
The Global Needle Coke Market is moderately consolidated, with key players controlling a significant portion of global supply. Leading companies focus on expanding refining capacity, improving product purity, and strengthening supply chains to secure long-term contracts with steel and battery manufacturers. It remains highly competitive as regional producers in Asia, North America, and Europe seek to expand their presence through strategic alliances and technology investments. Companies compete on cost efficiency, product performance, and sustainable production practices. Strong demand from steelmaking and lithium-ion battery applications ensures that both established and emerging players actively pursue market share.
Recent Developments:
- In July 2025, POSCO Future M signed a supply agreement with a major Japanese battery manufacturer to supply natural graphite anode materials produced at its Sejong plant for use in electric vehicle batteries. The company continues to expand its customer base globally through a self-sufficient supply chain and differentiated technology.
- GrafTech International Ltd: For the second quarter of 2025, GrafTech reported a 12% year-over-year increase in sales volume, totaling 28.6 thousand metric tons. The company noted its highest sales volume performance since Q3 2022, especially driven by a 38% increase in sales volume in the US market.
- Shanxi Hongte Coal Chemical Co. Ltd: Shanxi Hongte Coal Chemical suspended its needle coke quotation around mid-2025 as per market reports, reflecting ongoing adjustments in the needle coke market.
Report Coverage:
The research report offers an in-depth analysis based on type, application, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of electric arc furnaces will sustain steady electrode demand.
- Expanding EV markets will accelerate consumption of lithium-ion battery anodes.
- Advanced refining technologies will enhance purity and production efficiency.
- Regional supply diversification will reduce dependency on imports.
- Recycling of graphite electrodes will support circular economy models.
- New refinery projects in Asia-Pacific will expand production capacity.
- Demand for green steel initiatives will strengthen market stability.
- Strategic partnerships between refiners and automakers will boost growth.
- Environmental compliance will drive investment in cleaner technologies.
- Emerging economies will offer untapped opportunities in steel and energy storage.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Electric Arc Furnace Steelmaking
The shift toward electric arc furnace (EAF) steel production, which relies on ultra-high-power graphite electrodes made from needle coke, is increasing demand as global infrastructure and construction activities expand. EAFs are favored for their lower carbon emissions, aligning with sustainability goals and regulatory pressures.
Expansion of Lithium-Ion Battery Production for EVs
Needle coke is a critical raw material for synthetic graphite anodes in lithium-ion batteries, which are essential for electric vehicles. The rapid adoption of EVs worldwide, supported by government incentives and stricter emission standards, is driving significant growth in needle coke consumption.
Technological Advancements in Refining and Production
Innovations in refining processes are improving the purity, yield, and cost-efficiency of needle coke production. These advancements enable producers to meet the stringent quality requirements of both steel and battery manufacturers, supporting broader market adoption and supply chain resilience.
Regional Industrialization and Battery Manufacturing Expansion
Asia Pacific, especially China, India, and Japan, is experiencing robust industrial growth and rapid expansion of battery manufacturing capacity. This regional momentum is fueling demand for needle coke in both steelmaking and advanced energy storage applications.
Environmental Regulations and Green Steel Initiatives
Stringent environmental regulations in steel and battery industries are accelerating the shift toward cleaner production methods, such as EAFs and high-purity battery materials. Needle coke's role in enabling lower-emission processes and supporting green steel initiatives is strengthening its market position.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Needle Coke Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Needle Coke Market projected to grow between 2025 and 2032?
Which Global Needle Coke Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Needle Coke Market?
Who are the leading companies in the Global Needle Coke Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Petroleum Derived
- 1.2.2 Coal Tar Pitch Derived
- 1.3 By End User
- 1.3.1 Steel Industry
- 1.3.2 Aluminum Industry
- 1.3.3 Nuclear Power
- 1.4 By Application
- 1.4.1 Graphite Electrodes
- 1.4.2 Lithium-ion Batteries
- 1.4.3 Other Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 3,301.4 million → 2032: USD 6,728.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Needle Coke Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Needle Coke Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Needle Coke Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Needle Coke Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Needle Coke Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Needle Coke Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Needle Coke Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Needle Coke Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 3,301.4 million → 2032: USD 6,728.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Needle Coke Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Petroleum Derived
- 12.3.7.2 Coal Tar Pitch Derived
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Steel Industry
- 12.4.7.2 Aluminum Industry
- 12.4.7.3 Nuclear Power
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Graphite Electrodes
- 12.5.7.2 Lithium-ion Batteries
- 12.5.7.3 Other Applications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Needle Coke End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Needle Coke Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Needle Coke Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Needle Coke Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Baosteel Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 China National Petroleum Corporation (CNPC)
- 18.4 ENEOS Corporation
- 18.5 GrafTech International
- 18.6 Indian Oil Corporation
- 18.7 Nippon Steel Corporation
- 18.8 POSCO Future M
- 18.9 Shanxi Hongte Coal Chemical Co. Ltd.
- 18.10 Tokai Carbon Co., Ltd.
- 18.11 Sinopec
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

