
Market Overview:
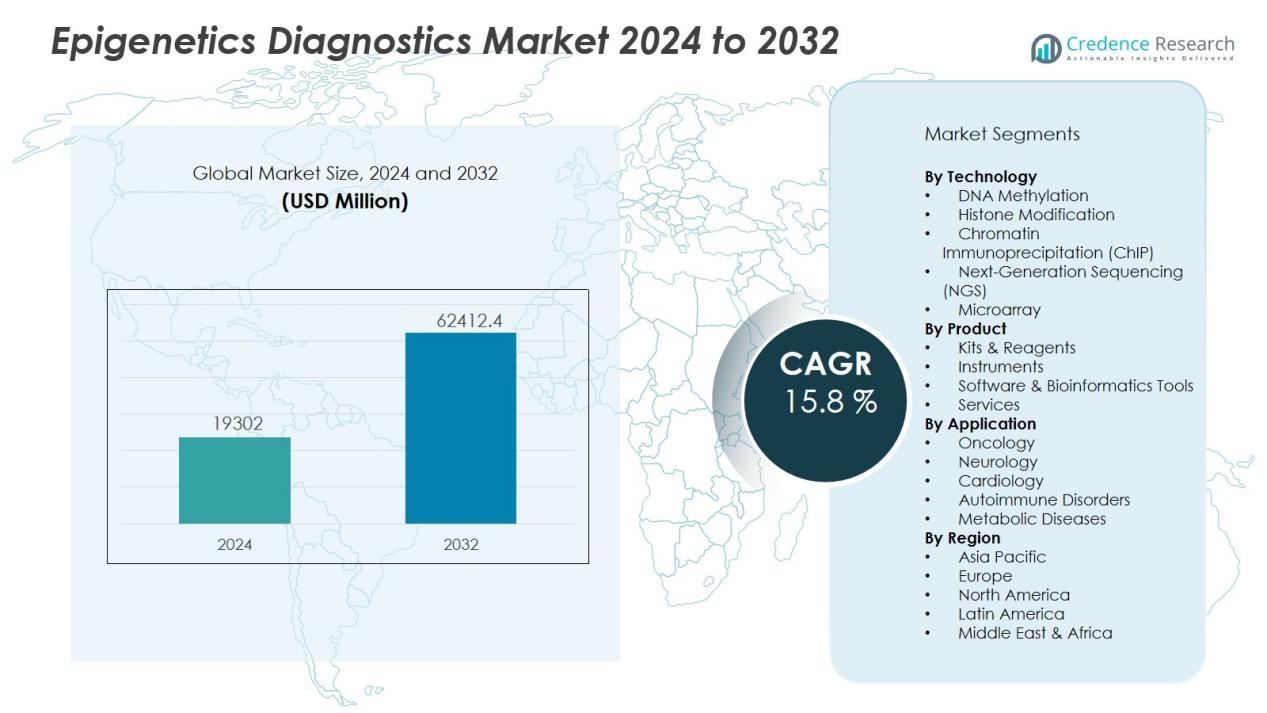
The epigenetics diagnostics market size was valued at USD 19302 million in 2024 and is anticipated to reach USD 62412.4 million by 2032, at a CAGR of 15.8 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Epigenetics Diagnostics Market Size 2024 | USD 19302 Million |
| Epigenetics Diagnostics Market, CAGR | 15.8 % |
| Epigenetics Diagnostics Market Size 2032 | USD 62412.4 Million |
Key drivers of this market include the rising global prevalence of cancer and chronic diseases, where epigenetic modifications serve as critical biomarkers for early diagnosis and treatment monitoring. Increasing demand for non-invasive diagnostic tools, combined with advancements in next-generation sequencing (NGS), DNA methylation assays, and histone modification studies, is fueling rapid adoption. The growth of personalized medicine, supported by ongoing clinical research and collaborations between diagnostic firms and research institutes, further strengthens the market outlook.
Regionally, North America dominates the epigenetics diagnostics market due to strong research infrastructure, high healthcare expenditure, and the presence of leading biotech companies. Europe follows with supportive regulatory frameworks and growing clinical adoption of epigenetic testing in oncology. Asia-Pacific is expected to witness the fastest growth, driven by increasing cancer incidence, expanding healthcare investments in countries like China and India, and rising awareness of early disease detection. Emerging markets in Latin America and the Middle East & Africa are gradually adopting epigenetics diagnostics, supported by improving healthcare infrastructure and international collaborations.
Market Insights:
- The epigenetics diagnostics market was valued at USD 19,302 million in 2024 and is projected to reach USD 62,412.4 million by 2032, reflecting strong growth potential.
- Rising prevalence of cancer and chronic diseases is a primary driver, with epigenetic biomarkers supporting early detection and improved patient outcomes.
- Advancements in next-generation sequencing, chromatin immunoprecipitation, and methylation assays are enhancing diagnostic precision and expanding clinical applications.
- Personalized medicine adoption is increasing, as clinicians and pharmaceutical firms rely on epigenetic data to design targeted therapies and improve treatment effectiveness.
- High costs of advanced testing methods and lack of standardized protocols remain key challenges, limiting accessibility and slowing widespread clinical integration.
- North America leads with 42% market share, supported by robust research infrastructure, favorable reimbursement policies, and strong biotech presence.
- Asia-Pacific is witnessing the fastest growth at 21% market share, driven by rising healthcare investments, cancer screening programs, and adoption of non-invasive diagnostics.
Market Drivers:
Rising Prevalence of Cancer and Chronic Diseases Driving Diagnostic Demand:
The epigenetics diagnostics market benefits from the growing global burden of cancer and chronic diseases, where early and accurate detection plays a critical role in treatment outcomes. Epigenetic biomarkers, such as DNA methylation and histone modifications, provide valuable insights for identifying disease onset at an early stage. It supports the development of targeted therapies and personalized medicine strategies, improving patient survival rates. Increasing healthcare focus on preventive and precision diagnostics continues to strengthen adoption.
- For instance, Volition's Nu.Q™ assay-an epigenetic blood test-demonstrated 74% sensitivity and 90% specificity for early-stage colorectal cancer detection in a pilot study of 58 asymptomatic patients, supporting improved non-invasive screening protocols.
Advancements in Molecular and Sequencing Technologies Enhancing Applications:
Continuous progress in molecular biology and sequencing platforms significantly contributes to the growth of the epigenetics diagnostics market. Techniques such as next-generation sequencing, chromatin immunoprecipitation, and methylation assays improve the sensitivity and specificity of diagnostics. It enables more comprehensive analysis of epigenetic modifications, expanding their application across oncology, neurology, and autoimmune disorders. Lower costs and faster turnaround times are further encouraging clinical and research use.
- For instance, Illumina’s NovaSeq 6000 sequencer produces up to 20 billion reads per run with over 90% of bases above Q30 quality, substantially increasing throughput and enabling whole genome sequencing in under 44 hours for enhanced clinical research applications.
Growing Adoption of Personalized Medicine and Targeted Therapies:
The rise of personalized medicine is fueling strong demand within the epigenetics diagnostics market. Clinicians rely on epigenetic information to design targeted therapies that match individual patient profiles. It allows healthcare providers to optimize treatment plans, reduce adverse effects, and improve therapeutic effectiveness. Pharmaceutical companies are also integrating epigenetic testing into drug development pipelines to enhance precision in clinical trials.
Supportive Research Investments and Collaborations Accelerating Growth:
Expanding investments in healthcare research and strategic collaborations among biotech firms, diagnostic companies, and academic institutions are accelerating innovation in the epigenetics diagnostics market. Funding initiatives encourage the development of advanced diagnostic platforms and clinical validation of epigenetic biomarkers. It strengthens the transition of research outcomes into commercialized diagnostic solutions. The supportive ecosystem ensures continuous innovation and wider accessibility of cutting-edge diagnostic tools.
Market Trends:
Integration of Epigenetic Biomarkers into Clinical Diagnostics and Precision Medicine:
The epigenetics diagnostics market is witnessing a strong shift toward clinical adoption of epigenetic biomarkers for disease detection and management. Healthcare providers increasingly recognize the role of DNA methylation, histone modifications, and non-coding RNA in identifying cancer, neurological disorders, and rare genetic conditions. It supports the development of companion diagnostics that guide targeted therapy selection and improve treatment outcomes. Pharmaceutical companies are embedding epigenetic testing in clinical trials to stratify patient populations and enhance drug efficacy. The growing acceptance of liquid biopsy-based epigenetic assays is expanding non-invasive diagnostic options, improving patient comfort and compliance. This trend is reinforcing the position of epigenetics as a cornerstone in precision medicine strategies.
- For instance, Illumina’s Infinium MethylationEPIC array enables profiling of over 850,000 CpG sites per sample, offering researchers a high-resolution view of the methylome in a single workflow. This capability has accelerated early-stage cancer detection studies, with over 95% concordance versus whole-genome bisulfite sequencing in multicenter trials.
Technological Innovations and Expansion into Emerging Healthcare Markets:
Rapid advancements in sequencing technologies and bioinformatics tools are shaping the evolution of the epigenetics diagnostics market. Automation, high-throughput platforms, and AI-driven data analysis are enabling faster, more accurate interpretation of epigenetic modifications. It broadens the scope of diagnostic applications beyond oncology into cardiology, immunology, and metabolic diseases. Increasing collaborations between diagnostic firms and research institutions are accelerating the validation of novel biomarkers and commercialization of advanced kits. Emerging markets in Asia-Pacific and Latin America are adopting these solutions at a faster pace due to rising healthcare investments and awareness of early disease detection. This expansion is creating significant opportunities for market players to diversify their offerings and establish a stronger global footprint.
- For instance, in 2023, Qiagen launched the EpiTect Methyl II PCR Array platform, which enables simultaneous analysis of up to 94 methylated DNA regions in a single run, significantly reducing turnaround times for clinical epigenetic diagnostics.
Market Challenges Analysis:
High Costs and Technical Complexity Limiting Widespread Adoption:
The epigenetics diagnostics market faces significant challenges due to the high costs and technical complexity of advanced testing methods. Next-generation sequencing, methylation assays, and bioinformatics tools require substantial investments in infrastructure, skilled personnel, and maintenance. It creates barriers for smaller laboratories and healthcare facilities in resource-limited regions. The cost of tests remains high for patients, reducing accessibility in developing countries. Limited reimbursement policies in many healthcare systems further restrict clinical adoption. These financial and operational constraints slow down the widespread use of epigenetics-based diagnostics in routine practice.
Regulatory Hurdles and Lack of Standardization Affecting Clinical Integration:
Regulatory challenges and the absence of standardized protocols also hinder the growth of the epigenetics diagnostics market. Diagnostic tests must undergo rigorous clinical validation to meet approval standards, delaying commercialization timelines. It increases uncertainty for companies investing in new biomarker discoveries and assay development. Variability in testing methods and interpretation across laboratories reduces reliability and consistency of results. Limited global harmonization of regulatory frameworks complicates market entry for companies targeting multiple regions. The lack of universally accepted guidelines slows clinical integration and limits physician confidence in adopting epigenetic diagnostics for patient care.
Market Opportunities:
Expanding Role of Epigenetic Biomarkers in Early Detection and Personalized Medicine:
The epigenetics diagnostics market presents strong opportunities through the growing demand for early disease detection and personalized treatment strategies. Epigenetic biomarkers enable identification of cancers, neurological disorders, and metabolic conditions at pre-symptomatic stages, offering significant clinical value. It supports the development of companion diagnostics that guide therapy decisions and improve treatment effectiveness. Pharmaceutical and biotechnology companies are increasingly integrating epigenetic testing into drug development pipelines, creating new avenues for collaboration. The rising focus on precision medicine and patient-tailored solutions strengthens the relevance of epigenetic diagnostics in clinical practice. Growing awareness of non-invasive diagnostic methods such as liquid biopsy further enhances adoption potential.
Adoption in Emerging Markets and Advancements in Diagnostic Technologies:
Emerging economies provide substantial growth opportunities for the epigenetics diagnostics market due to rising healthcare investments and improving infrastructure. Governments and private organizations are increasing funding for cancer screening and research programs, creating a supportive environment for adoption. It encourages diagnostic firms to expand their presence in regions such as Asia-Pacific, Latin America, and the Middle East. Advances in sequencing platforms, automation, and AI-driven bioinformatics enhance accuracy and efficiency, making epigenetic tests more accessible. Partnerships between global players and local healthcare providers are accelerating technology transfer and market penetration. The convergence of affordability, innovation, and expanding healthcare access positions epigenetic diagnostics for accelerated global growth.
Market Segmentation Analysis:
By Technology:
The epigenetics diagnostics market is segmented by technology into DNA methylation, histone modification, chromatin immunoprecipitation, and next-generation sequencing (NGS). DNA methylation assays dominate due to their wide application in cancer detection and monitoring. It plays a crucial role in identifying abnormal gene expression and early disease onset. Histone modification analysis is gaining traction for its ability to provide insights into neurodegenerative and autoimmune disorders. NGS platforms are expanding adoption with high accuracy, scalability, and reduced costs. These technologies collectively drive clinical and research applications of epigenetic testing.
- For instance, Illumina’s NovaSeq 6000 platform delivers up to 6Tb output per run, empowering large-scale epigenetic sequencing projects for clinical genomics laboratories.
By Product:
Products in the epigenetics diagnostics market include reagents, kits, instruments, and software solutions. Kits and reagents hold the largest share, driven by their routine use in laboratories and diagnostic centers. Instruments such as sequencers and PCR systems support high-throughput applications and advanced biomarker analysis. It ensures reliability and efficiency in clinical workflows. Software solutions integrated with bioinformatics tools are essential for data interpretation, expanding their importance in diagnostics. Continuous innovation across product categories is improving usability and accessibility.
- For instance, QIAGEN’s CLC Genomics Workbench provides epigenomics analysis workflows capable of processing datasets with more than 500 million sequencing reads, supporting accurate methylation calling and biomarker identification.
By Application:
Applications of the epigenetics diagnostics market span oncology, neurology, cardiology, and autoimmune diseases. Oncology remains the largest application area due to the high burden of cancer and the role of epigenetic biomarkers in early detection and treatment monitoring. Neurology applications are expanding with growing prevalence of Alzheimer’s and Parkinson’s disease. It strengthens demand for early diagnostic solutions. Cardiology and autoimmune disease diagnostics are emerging segments, benefiting from research into gene regulation and immune responses. The expanding clinical scope highlights the market’s potential across diverse medical fields.
Segmentations:
By Technology:
- DNA Methylation
- Histone Modification
- Chromatin Immunoprecipitation (ChIP)
- Next-Generation Sequencing (NGS)
- Microarray
By Product:
- Kits & Reagents
- Instruments
- Software & Bioinformatics Tools
- Services
By Application:
- Oncology
- Neurology
- Cardiology
- Autoimmune Disorders
- Metabolic Diseases
By Region:
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Analysis:
North America :
North America holds 42% market share in the epigenetics diagnostics market, supported by advanced healthcare systems and strong R&D capabilities. The United States leads the region with significant adoption of molecular diagnostics and high cancer screening rates. It benefits from supportive reimbursement frameworks and large-scale government initiatives for precision medicine. The presence of leading biotechnology companies and academic institutions drives innovation and commercialization of novel assays. Clinical trials in oncology and neurology frequently integrate epigenetic biomarkers, strengthening clinical adoption. Canada contributes with increasing investments in genomics and personalized healthcare solutions.
Europe :
Europe accounts for 29% market share in the epigenetics diagnostics market, driven by supportive regulatory frameworks and national genomics initiatives. Countries such as Germany, the United Kingdom, and France are investing heavily in precision medicine programs. It benefits from strong collaboration between healthcare providers, research institutes, and diagnostic firms. The European Medicines Agency plays a critical role in validating biomarkers and accelerating clinical adoption. Rising demand for early cancer detection and neurodegenerative disease testing strengthens adoption of epigenetic assays. Eastern Europe is also witnessing growing adoption due to improving healthcare infrastructure and rising diagnostic awareness.
Asia-Pacific :
Asia-Pacific holds 21% market share in the epigenetics diagnostics market, supported by rapid healthcare expansion and rising disease prevalence. China and India lead the region with increasing government funding in genomics and cancer screening programs. It benefits from cost-effective diagnostic solutions and growing private sector participation. Japan contributes with advanced research in molecular diagnostics and widespread integration of biomarkers in clinical practice. Rising patient awareness and the growing burden of lifestyle diseases support strong demand for early diagnostic tools. Southeast Asia is emerging as a key market with expanding healthcare access and increasing adoption of non-invasive diagnostic technologies.
Key Player Analysis:
- Hoffmann- La Roche Ltd.
- Eisai Co. Ltd.
- Thermo Fisher Scientific, Inc.
- Novartis AG
- Cantata Bio (Dovetail Genomics LLC.)
- Element Biosciences, Inc.
- Illumina, Inc.
- Abcam Ltd.
- ValiRx Plc.
Competitive Analysis:
The epigenetics diagnostics market is highly competitive, with global players driving innovation through advanced technologies and strategic collaborations. Key companies include Hoffmann-La Roche Ltd., Eisai Co. Ltd., Thermo Fisher Scientific, Inc., Novartis AG, Cantata Bio (Dovetail Genomics LLC), Element Biosciences, Inc., and Illumina, Inc. These firms focus on expanding their portfolios with DNA methylation assays, next-generation sequencing platforms, and bioinformatics solutions. It is characterized by continuous R&D investments, partnerships with academic institutions, and acquisitions aimed at strengthening market presence. Established companies leverage strong distribution networks and regulatory expertise to accelerate commercialization, while emerging players focus on niche segments and cost-effective solutions. The market emphasizes precision medicine and non-invasive diagnostics, creating opportunities for differentiation through clinical validation and data-driven platforms. Competition is intensifying as firms aim to capture demand from oncology, neurology, and chronic disease diagnostics, positioning themselves for long-term growth.
Recent Developments:
- In May 2025, Hoffmann-La Roche Ltd. received FDA approval for Susvimo (ranibizumab injection), a new treatment for diabetic retinopathy that allows continuous drug delivery and reduces the frequency of treatment visits.
- In February 2025: Thermo Fisher Scientific, Inc. announced plans to acquire Solventum’s Purification & Filtration unit for $4.1 billion to expand its bioprocessing portfolio, with the deal expected to close by the end of 2025.
- In July 2025, Element Biosciences Inc. announced it surpassed 50 global installations of its AVITI24 5D Multiomic System, the only commercially available fully integrated multiomic platform, marking rapid market adoption since its release in December 2024.
Market Concentration & Characteristics:
The epigenetics diagnostics market is moderately concentrated, with a mix of established biotechnology firms, diagnostic companies, and emerging startups competing for share. Leading players dominate through strong portfolios in DNA methylation assays, next-generation sequencing platforms, and companion diagnostics. It is characterized by continuous innovation, high research intensity, and strategic collaborations between industry and academia. The market emphasizes precision medicine, driving adoption of non-invasive tests and biomarker-based assays. Regional players focus on affordability and accessibility, while global leaders invest in advanced technologies and regulatory approvals. Competition remains dynamic, with differentiation driven by test accuracy, clinical validation, and integration with therapeutic pipelines.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Product, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The epigenetics diagnostics market will expand its role in precision medicine through greater integration of biomarker-driven tests in oncology, neurology, and metabolic disorders.
- It will benefit from increasing adoption of liquid biopsy technologies, offering non-invasive and patient-friendly diagnostic alternatives.
- Growing collaborations between pharmaceutical companies and diagnostic developers will accelerate the development of companion diagnostics to guide targeted therapies.
- Advancements in next-generation sequencing and AI-driven bioinformatics will improve test accuracy, speed, and clinical usability.
- Healthcare systems will invest in early detection programs, strengthening demand for epigenetic assays in cancer screening and chronic disease management.
- Regulatory approvals and standardized testing guidelines will enhance clinical confidence and expand adoption in routine diagnostics.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East will drive significant growth due to healthcare investments and rising awareness.
- Academic research will continue to uncover novel epigenetic biomarkers, expanding diagnostic applications beyond oncology into cardiology and autoimmune diseases.
- Cost reduction in sequencing technologies and wider reimbursement coverage will improve patient accessibility and affordability.
- The competitive landscape will remain innovation-driven, with companies focusing on differentiation through advanced platforms, strategic partnerships, and global expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the epigenetics diagnostics market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the epigenetics diagnostics market projected to grow between 2024 and 2032?
Which epigenetics diagnostics market segment held the largest share in 2024?
What are the primary factors fueling the growth of the epigenetics diagnostics market?
Who are the leading companies in the epigenetics diagnostics market?
Which region commanded the largest share of the epigenetics diagnostics market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Epigenetics Diagnostics Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Epigenetics Diagnostics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 19,302 million → 2032: USD 62,412.4 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Epigenetics Diagnostics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Epigenetics Diagnostics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Epigenetics Diagnostics Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Epigenetics Diagnostics Market Drivers
- 3.3 Epigenetics Diagnostics Market Restraints & Challenges
- 3.4 Epigenetics Diagnostics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Epigenetics Diagnostics Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Epigenetics Diagnostics Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Epigenetics Diagnostics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Epigenetics Diagnostics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Epigenetics Diagnostics Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Epigenetics Diagnostics. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Epigenetics Diagnostics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Epigenetics Diagnostics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Epigenetics Diagnostics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Epigenetics Diagnostics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Epigenetics Diagnostics
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Epigenetics Diagnostics Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Epigenetics Diagnostics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Epigenetics Diagnostics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Epigenetics Diagnostics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Epigenetics Diagnostics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Epigenetics Diagnostics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Epigenetics Diagnostics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Epigenetics Diagnostics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
