
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
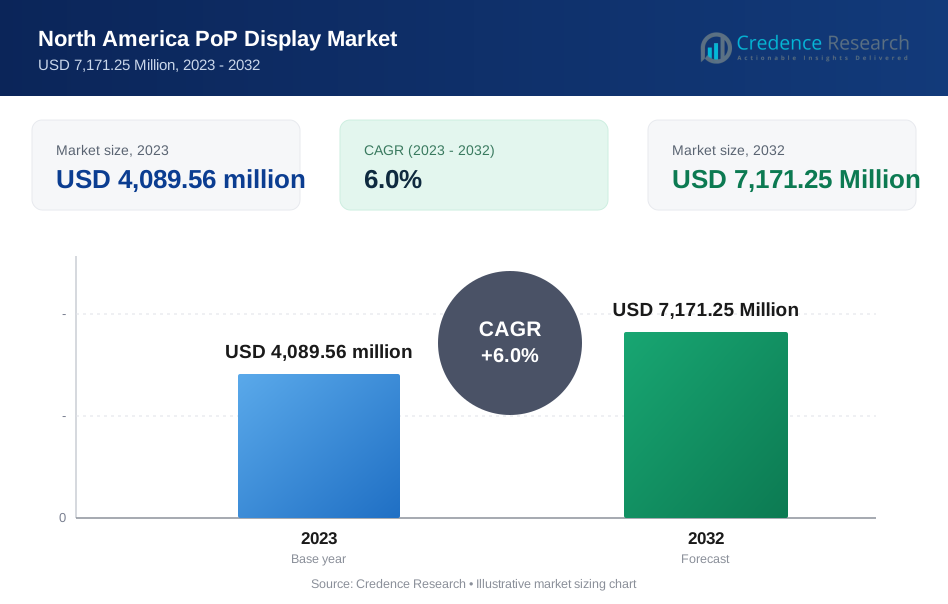
| North America PoP Display Market Size 2023 | USD 4,089.56 Million |
| North America PoP Display Market, CAGR | 6.0% |
| North America PoP Display Market Size 2032 | USD 7,171.25 Million |
Market Overview
The North America PoP Display Market is projected to grow from USD 4,089.56 million in 2023 to an estimated USD 7,171.25 million by 2032, with a compound annual growth rate (CAGR) of 6.0% from 2024 to 2032. This growth is driven by the increasing demand for effective in-store marketing strategies that enhance product visibility and consumer engagement.
Key market drivers include the rising trend of customization and personalization in retail displays, technological advancements such as digital and interactive PoP displays, and the growing emphasis on sustainable and eco-friendly materials. Trends indicate a shift towards more dynamic and engaging displays that incorporate digital screens and interactive elements, providing a more immersive shopping experience. Additionally, the increasing focus on sustainability is leading to the adoption of recyclable and biodegradable materials in PoP display manufacturing.
Geographically, the United States dominates the North America PoP Display Market, accounting for the largest market share due to its well-established retail sector and high consumer spending. Canada follows, with significant growth potential driven by the expanding retail industry and increasing adoption of innovative marketing solutions. Key players in the market include International Paper Company, DS Smith Plc, Smurfit Kappa Group Plc, Menasha Packaging Company, LLC, and Sonoco Products Company, who are continuously innovating to meet the evolving needs of retailers and brands.
Market Drivers
Technological Advancements and Digital Integration
Technological advancements have revolutionized the POP display market in North America, with digital and interactive elements becoming increasingly prevalent. According to a survey by the Retail Industry Leaders Association, a majority of retailers are integrating digital screens and touch interfaces into their displays to create more engaging customer experiences. The National Retail Federation reports that interactive POP displays have led to significant increases in customer engagement and sales conversions. For instance, a major electronics retailer found that digital POP displays featuring product demonstrations increased dwell time and purchase intent among customers. The U.S. Department of Commerce notes that the adoption of augmented reality in retail displays has grown substantially, with several leading brands implementing AR features to showcase products virtually. A study by the Point of Purchase Advertising International (POPAI) revealed that digital POP displays are particularly effective in capturing consumer attention and influencing purchasing decisions. Additionally, the Consumer Technology Association reports that the integration of data analytics with digital displays has become a key trend, allowing retailers to gather valuable insights into consumer behavior and optimize their marketing strategies accordingly.
Emphasis on Customization and Personalization
The demand for customized and personalized POP displays has surged in North America, as evidenced by several industry surveys. The National Association of Retail Marketing Services found that a significant portion of retailers are investing in custom-designed displays to differentiate their brand and create unique in-store experiences. A study by the Shopper Marketing Institute revealed that personalized POP displays have a higher impact on consumer purchase decisions compared to generic ones. For example, a major cosmetics brand reported a substantial increase in sales after implementing customized displays tailored to different skin types and preferences. The Retail Design Institute notes that advancements in manufacturing technologies, such as 3D printing, have made it more feasible for retailers to produce unique and eye-catching displays. A survey by the In-Store Marketing Institute showed that modular and adaptable POP displays are gaining popularity, allowing retailers to quickly refresh their in-store marketing based on changing trends and promotions. The American Marketing Association reports that personalized displays have been particularly effective in enhancing brand loyalty and fostering emotional connections with consumers, leading to repeat purchases and increased customer lifetime value.
Increasing Focus on Sustainability and Eco-Friendly Materials
Sustainability has emerged as a key driver in the North America POP Display Market, as confirmed by various industry reports. The Sustainable Packaging Coalition's survey indicates a growing trend among retailers to adopt eco-friendly materials for their displays, with many opting for recyclable and biodegradable options. The Environmental Protection Agency has noted an increase in the use of sustainable materials like bamboo and cornstarch-based plastics in retail displays. For instance, a leading grocery chain reported positive customer feedback and increased brand perception after switching to displays made from recycled materials. The Green Retail Alliance found that brands using sustainable POP displays experienced improved customer loyalty and positive social media engagement. A study by the Retail Industry Sustainability Council revealed that modular and reusable display systems are gaining traction, helping retailers minimize waste and extend the lifespan of their displays. The American Forest & Paper Association reports a significant uptick in the use of certified sustainable paper and cardboard in POP displays, reflecting the industry's commitment to responsible sourcing.
Evolution of Retail Environments and Consumer Behavior
The evolution of retail environments and changing consumer behavior are pivotal drivers of the PoP display market. As brick-and-mortar stores adapt to the challenges posed by e-commerce, they are redefining the in-store experience to attract and retain customers. PoP displays play a crucial role in creating an engaging and immersive shopping environment that competes with online retail.Retailers are leveraging PoP displays to create visually appealing and experiential store layouts that encourage exploration and discovery. Interactive displays, sensory elements, and thematic setups are used to create memorable shopping experiences that drive foot traffic and increase dwell time. These displays act as focal points within stores, guiding customers through different sections and highlighting featured products.Consumer behavior has also evolved, with shoppers seeking convenience, information, and entertainment during their shopping journeys. PoP displays that provide product information, usage tips, and real-time promotions cater to these demands, enhancing the overall shopping experience. The integration of mobile and social media elements with PoP displays allows consumers to engage with brands beyond the physical store, creating a seamless omnichannel experience.Moreover, the COVID-19 pandemic has accelerated changes in consumer behavior, with a heightened focus on health and safety. PoP displays that promote hygiene products, social distancing measures, and contactless interactions have become essential in reassuring customers and fostering a safe shopping environment. The adaptability of PoP displays to address emerging consumer needs underscores their importance in the retail landscape.
Market Trends
Integration of Advanced Technologies
The North America PoP Display Market is experiencing a significant shift towards the integration of advanced technologies, transforming traditional displays into interactive and dynamic marketing tools. Digital screens, augmented reality (AR), and virtual reality (VR) are becoming increasingly prevalent in PoP displays, providing consumers with engaging and immersive experiences. These technologies enable retailers to showcase product features, demonstrate usage, and offer personalized recommendations, enhancing customer engagement and driving sales. For instance, a survey conducted by the National Retail Federation found that 61% of retailers are planning to implement AR or VR technology in their stores within the next two years. This trend is particularly evident in the PoP display sector, where interactive displays are becoming more common. A study by the Point of Purchase Advertising International (POPAI) revealed that digital displays capture 400% more views than static displays, highlighting their effectiveness in attracting consumer attention. Moreover, the use of data analytics in conjunction with digital PoP displays is becoming a common practice. By analyzing customer interactions and engagement metrics, retailers can gain a deeper understanding of consumer preferences and trends. A report by Deloitte found that retailers using advanced analytics for decision-making saw a 19% increase in operating margin over a three-year period. This data-driven approach enables the creation of more personalized and impactful marketing campaigns, ultimately leading to higher conversion rates and improved return on investment (ROI).
Emphasis on Sustainability and Eco-Friendly Solutions
Sustainability has emerged as a crucial trend in the North America PoP Display Market, driven by increasing consumer awareness and demand for environmentally responsible products. Brands and retailers are prioritizing the use of sustainable materials and eco-friendly manufacturing processes in the production of PoP displays. This shift not only aligns with corporate social responsibility goals but also resonates with eco-conscious consumers, enhancing brand loyalty and reputation. A study by the Sustainable Packaging Coalition found that 74% of consumers are willing to pay more for sustainable packaging. This sentiment extends to PoP displays, with retailers reporting increased customer engagement with eco-friendly displays. For example, a major retail chain reported a 15% increase in sales for products displayed in sustainable PoP units compared to traditional displays.In response to the growing emphasis on sustainability, companies are also exploring innovative packaging solutions and optimizing their supply chains to reduce carbon footprints. The Environmental Protection Agency (EPA) reported that businesses implementing sustainable practices in their supply chains saw an average reduction of 20% in their carbon emissions. Brands that demonstrate a commitment to sustainability are likely to gain a competitive edge, as consumers increasingly favor businesses that prioritize environmental responsibility. A survey by Nielsen found that 73% of global consumers say they would definitely or probably change their consumption habits to reduce their environmental impact.
Market Restraints and Challenges
High Initial Costs and Limited Budget Allocation
One of the primary restraints in the North America PoP Display Market is the high initial cost associated with designing, manufacturing, and implementing advanced PoP displays. The integration of cutting-edge technologies such as digital screens, augmented reality (AR), and virtual reality (VR) significantly increases the cost of production compared to traditional static displays. For small and medium-sized retailers, these high costs can be prohibitive, limiting their ability to adopt the latest display innovations. However, budget constraints often result in limited allocation of funds towards PoP displays, as retailers may prioritize other marketing channels and operational expenses. For instance, a survey conducted by a leading retail association found that only a small fraction of retailers allocate more than 5% of their marketing budget to PoP displays. The need for frequent updates and maintenance of digital displays further adds to the overall expenditure, making it challenging for businesses to justify the investment. To overcome this challenge, manufacturers and solution providers need to develop cost-effective solutions and offer flexible pricing models.
Rapid Technological Advancements and Obsolescence
The rapid pace of technological advancements presents both an opportunity and a challenge for the North America PoP Display Market. While innovations drive market growth, they also lead to the rapid obsolescence of existing display solutions. Retailers who invest in the latest PoP technologies may find their displays becoming outdated within a short period, necessitating further investment in upgrades or replacements. Average lifespan of digital PoP displays has decreased by 30% over the past five years due to rapid technological advancements. This constant cycle of obsolescence can be particularly challenging for retailers with limited budgets, as it imposes ongoing financial pressures. Moreover, the fast-evolving nature of display technologies requires retailers to stay continuously updated with the latest trends and advancements, which can be resource-intensive. For example, a survey of retail managers found that over half of respondents struggled to keep pace with the latest PoP display technologies. To address this challenge, manufacturers and suppliers need to focus on developing modular and upgradable PoP display systems. By designing displays that can be easily updated or enhanced with new features, retailers can extend the lifespan of their investments and reduce the frequency of replacements.
Market Segmentation Analysis
By Type
Floor displays are widely used in North American retail environments for their versatility and impact. For instance, a survey by the National Retail Federation found that floor displays increased product sales by an average of 25% compared to standard shelf placements. Countertop displays are particularly effective for impulse purchases, with data from the Point of Purchase Advertising International (POPAI) showing that 82% of purchase decisions are made in-store. Pallet displays have gained popularity in warehouse clubs and big-box retailers, with Costco reporting that pallet displays account for over 60% of their in-store promotional strategies. Sidekick displays have proven effective in maximizing limited retail space, with a study by the In-Store Marketing Institute revealing that they can increase product visibility by up to 40%. The "Others" category, including spinner displays and retail signage, has seen growth due to their ability to create interactive experiences, with a Retail Customer Experience survey indicating that 73% of shoppers find these displays more engaging than traditional formats.
By Application
The Food & Beverage sector dominates POP display applications in North America, with the Food Marketing Institute reporting that well-designed displays can increase sales of featured products by up to 300%. In the Pharmaceuticals sector, a study by Healthcare Distribution Alliance found that POP displays improved consumer awareness of over-the-counter medications by 45%. The Cosmetics & Personal Care segment heavily relies on POP displays, with data from the Personal Care Products Council showing that 68% of beauty product purchases are influenced by in-store displays. In the Electronics sector, the Consumer Technology Association reported that interactive POP displays increased product engagement by 60% and sales by 35%. The "Others" category, encompassing diverse industries, has seen significant growth, with the Specialty Equipment Market Association noting that automotive accessory sales increased by 28% when featured on POP displays. These findings underscore the crucial role of POP displays in driving consumer engagement and sales across various sectors in the North American market.
Segments
Based on Type
- Floor Displays
- Countertop Displays
- Pallet Displays
- Sidekick Displays
- Others (Spinner Displays, Retail Signage, etc.)
Based on Application
- Food & Beverage
- Pharmaceuticals
- Cosmetics & Personal Care
- Electronics
- Others
Based on Style
- Temporary PoP Displays
- Permanent PoP Displays
Based on Material
- Corrugated Board
- Plastic
- Metal
- Wood
- Others
Based on Region
- United States
- Canada
- Mexico
Regional Analysis
United States (70%)
The United States dominates the North America PoP Display Market, accounting for approximately 70% of the market share. This leadership position is driven by a well-established retail sector, high consumer spending, and a strong emphasis on innovative marketing strategies. The U.S. retail industry is characterized by its diversity, encompassing everything from large-scale supermarkets to boutique stores, all of which utilize POP displays to enhance in-store experiences and drive sales. According to the U.S. Census Bureau's Annual Retail Trade Survey, the retail sector in the United States continues to grow steadily. For instance, the survey reported significant increases in sales for various retail categories, including food and beverage stores, health and personal care stores, and general merchandise stores. This growth directly impacts the demand for POP displays as retailers seek to capitalize on in-store marketing opportunities.
Canada (20%)
Canada holds a significant portion of the North America PoP Display Market, with approximately 20% market share. The Canadian retail sector is expanding, driven by rising consumer demand and a growing emphasis on enhancing in-store customer experiences. Canadian retailers are increasingly adopting customized POP displays to differentiate their offerings and attract consumers. Statistics Canada's Retail Trade Survey provides insights into the country's retail landscape. For instance, the survey has shown consistent growth in retail sales across various sectors, including food and beverage stores, health and personal care stores, and general merchandise stores. This growth correlates with increased demand for POP displays as retailers seek to maximize their in-store marketing efforts.
Key players
- International Paper Company
- DS Smith Plc
- Smurfit Kappa Group Plc
- Menasha Packaging Company, LLC.
- Sonoco Products Company
- WestRock Company
- Georgia-Pacific LLC.
- Pratt Industries Inc.
- Marketing Alliance Group
- Bling Packaging & Displays
- FFR Merchandising Company
Competitive Analysis
The North America PoP Display Market is characterized by intense competition among key players, each striving to enhance their market presence through innovation and strategic expansions. Leading companies such as International Paper Company, DS Smith Plc, and Smurfit Kappa Group Plc dominate the market with their extensive product portfolios and strong distribution networks. Menasha Packaging Company, LLC and Sonoco Products Company are recognized for their customized and sustainable display solutions, catering to the evolving needs of retailers. WestRock Company and Georgia-Pacific LLC leverage advanced technologies to offer interactive and engaging PoP displays. Pratt Industries Inc. and Marketing Alliance Group focus on cost-effective and eco-friendly solutions. Bling Packaging & Displays and FFR Merchandising Company are known for their innovative designs and specialized display products. These companies continuously invest in R&D and sustainability initiatives, driving market growth and setting industry standards.
Recent Developments
- In June 2024, Sonoco Products Company announced a price increase for all paperboard converted products in the U.S. and Canada.
- In July 2024, Smurfit Kappa merged with WestRock to form Smurfit WestRock, which made its debut on the New York and London stock exchanges.
- In June 2018, DS Smith put a revolutionary digital pre-printing machine into operation at their site in Fulda, Germany. While this is not a recent development, it showcases the company's commitment to innovation in packaging technology.
- In May 2024, Menasha Corporation (parent company of Menasha Packaging) awarded $6 million in grants to nonprofit organizations as part of its 175th anniversary celebration.
Market Concentration and Characteristics
The North America PoP Display Market exhibits a moderate to high market concentration, dominated by a few key players such as International Paper Company, DS Smith Plc, and Smurfit Kappa Group Plc, who hold substantial market shares due to their extensive product ranges, strong distribution networks, and continuous innovation. These leading companies, along with others like Menasha Packaging Company, LLC and WestRock Company, drive market dynamics by leveraging advanced technologies and sustainable practices. The market is characterized by its focus on customization, technological integration, and eco-friendly solutions, catering to diverse retail needs and consumer preferences across various segments. This competitive landscape encourages continuous improvement and adaptation to emerging trends, ensuring the market's robust growth and evolution.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Style, Material and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will increasingly adopt advanced technologies such as digital and interactive displays, enhancing consumer engagement and personalized shopping experiences.
- There will be a growing emphasis on eco-friendly materials and sustainable practices, driven by rising consumer awareness and regulatory pressures.
- Retailers will seek more customized PoP displays to align with brand identities and specific marketing strategies, leading to innovative design solutions.
- Integration of digital elements like QR codes and augmented reality will become more prevalent, bridging online and offline shopping experiences.
- The rise of e-commerce will drive demand for PoP displays in fulfillment centers and pick-up locations, adapting traditional retail strategies for new shopping environments.
- Increasing retail investments in emerging markets like Mexico will fuel demand for diverse PoP display solutions tailored to local preferences and trends.
- The market will see a rise in modular and reusable PoP display systems, offering cost-efficiency and adaptability for various retail settings and promotional activities.
- Retailers will leverage data analytics from PoP displays to gain insights into consumer behavior and optimize marketing strategies for improved ROI.
- The demand for highly interactive and engaging PoP displays will grow, incorporating features such as touchscreens and real-time product information.
- The industry will face increasing regulatory requirements related to sustainability and safety, prompting companies to adapt their practices and materials accordingly.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements and Digital Integration
The adoption of digital screens, interactive elements, and data analytics in PoP displays is transforming in-store marketing, making displays more engaging and effective at capturing consumer attention and driving sales.
Emphasis on Customization and Personalization
Retailers are increasingly investing in custom-designed PoP displays to differentiate their brands and create unique in-store experiences, which has been shown to significantly influence consumer purchase decisions and boost brand loyalty.
Increasing Focus on Sustainability and Eco-Friendly Materials
Growing consumer and regulatory demand for environmentally responsible products is driving the adoption of recyclable, biodegradable, and sustainably sourced materials in PoP display manufacturing, enhancing brand reputation and customer engagement.
Evolution of Retail Environments and Consumer Behavior
As brick-and-mortar stores adapt to compete with e-commerce, PoP displays are being used to create immersive, experiential shopping environments that increase dwell time, guide customer flow, and address new health and safety expectations post-pandemic.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the North America PoP Display Market?
What are the main drivers of the North America PoP Display Market?
Which regions dominate the North America PoP Display Market?
What types of materials are commonly used in PoP displays?
How are technological advancements impacting PoP displays?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Floor Displays
- 1.2.2 Countertop Displays
- 1.2.3 Pallet Displays
- 1.2.4 Sidekick Displays
- 1.2.5 Others (Spinner Displays, Retail Signage, etc.)
- 1.3 By Style
- 1.3.1 Temporary PoP Displays
- 1.3.2 Permanent PoP Displays
- 1.4 By Material
- 1.4.1 Corrugated Board
- 1.4.2 Plastic
- 1.4.3 Metal
- 1.4.4 Wood
- 1.4.5 Others
- 1.5 By Application
- 1.5.1 Food & Beverage
- 1.5.2 Pharmaceuticals
- 1.5.3 Cosmetics & Personal Care
- 1.5.4 Electronics
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 4,089.56 million → 2032: USD 7,171.25 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America PoP Display Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America PoP Display Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America PoP Display Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America PoP Display Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America PoP Display Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America PoP Display Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 North America PoP Display Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America PoP Display Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 4,089.56 million → 2032: USD 7,171.25 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America PoP Display Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Floor Displays
- 12.3.7.2 Countertop Displays
- 12.3.7.3 Pallet Displays
- 12.3.7.4 Sidekick Displays
- 12.3.7.5 Others (Spinner Displays, Retail Signage, etc.)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Style - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Temporary PoP Displays
- 12.4.7.2 Permanent PoP Displays
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Corrugated Board
- 12.5.7.2 Plastic
- 12.5.7.3 Metal
- 12.5.7.4 Wood
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Food & Beverage
- 12.6.7.2 Pharmaceuticals
- 12.6.7.3 Cosmetics & Personal Care
- 12.6.7.4 Electronics
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 North America PoP Display End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America PoP Display Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America PoP Display Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America PoP Display Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 International Paper Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DS Smith Plc
- 18.4 Smurfit Kappa Group Plc
- 18.5 Menasha Packaging Company, LLC
- 18.6 Sonoco Products Company
- 18.7 WestRock Company
- 18.8 Georgia-Pacific LLC
- 18.9 Pratt Industries Inc.
- 18.10 Marketing Alliance Group
- 18.11 Bling Packaging & Displays
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

