
Market Overview
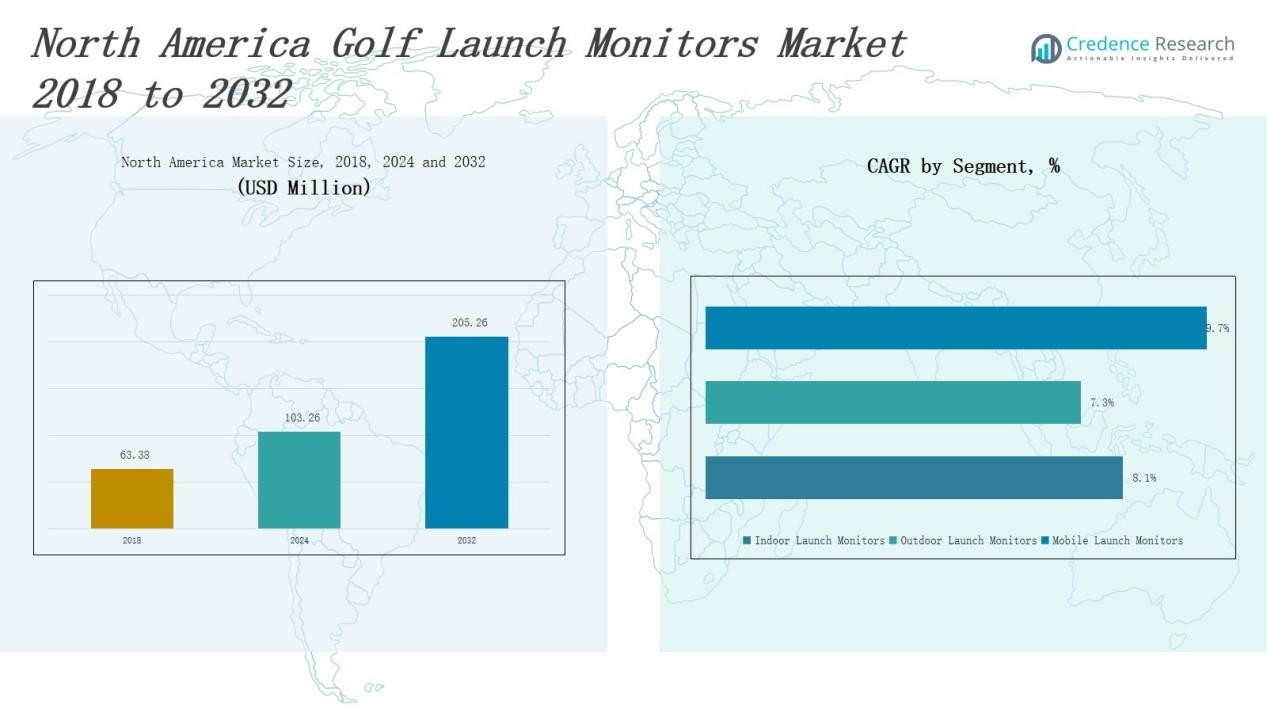
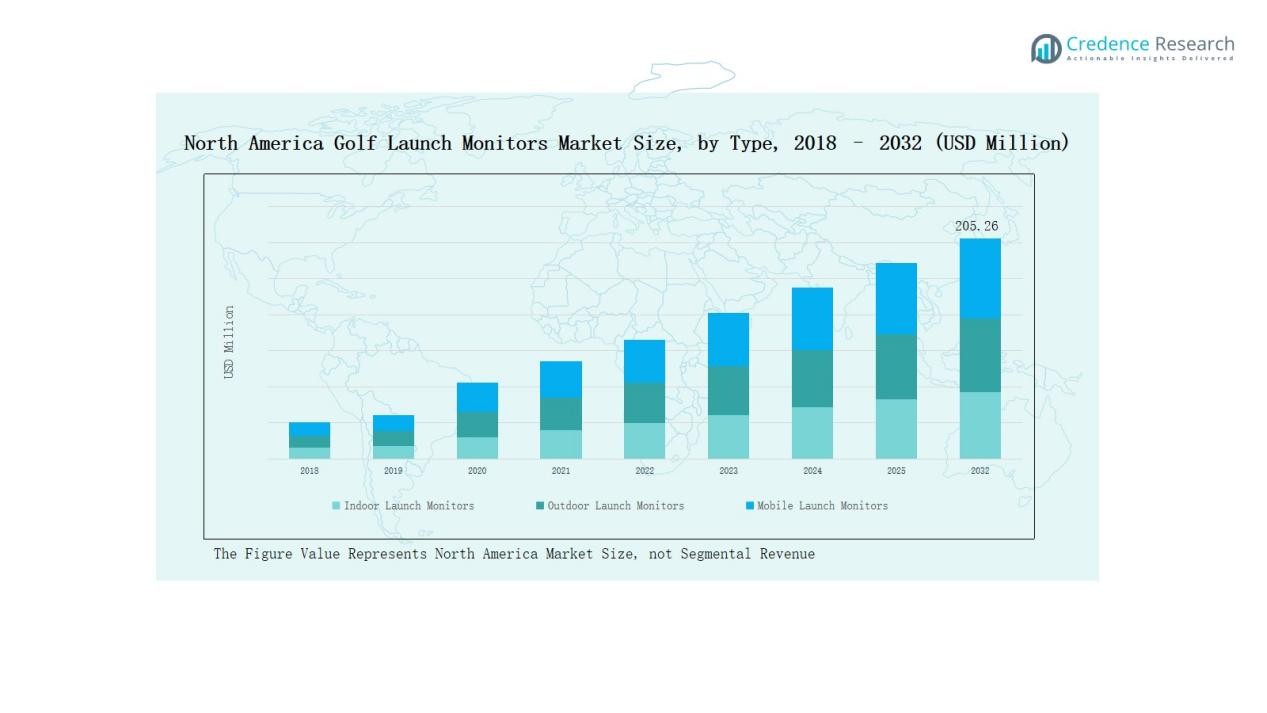
North America Golf Launch Monitors Market size was valued at USD 63.38 million in 2018 to USD 103.26 million in 2024 and is anticipated to reach USD 205.26 million by 2032, at a CAGR of 8.4 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Golf Launch Monitors Market Size 2024 | USD 103.26Million |
| North America Golf Launch Monitors Market, CAGR | 18.4 % |
| North America Golf Launch Monitors Market Size 2032 | USD 205.26 Million |
The North America Golf Launch Monitors Market features leading players such as Foresight Sports, SkyTrak, Full Swing Golf, TruGolf, Ernest Sports, VOICE Caddie, Garmin Approach, Optishot, FlightScope, and Rapsodo. These companies drive market growth through continuous innovation, advanced technology integration, and strategic partnerships. North America holds the largest regional share, commanding 42.5% of the global market. The United States leads this region due to high adoption rates among professional and amateur golfers, widespread golf facility infrastructure, and strong demand for data-driven performance analysis. This dominant position supports sustained investment and product development from key players operating within the market.
Market Insights
- The North America Golf Launch Monitors Market grew from USD 63.38 million in 2018 to USD 103.26 million in 2024 and is expected to reach USD 205.26 million by 2032, at a CAGR of 8.4%.
- Leading companies such as Foresight Sports, SkyTrak, Full Swing Golf, TruGolf, Ernest Sports, VOICE Caddie, Garmin Approach, Optishot, FlightScope, and Rapsodo drive growth through innovation and strategic partnerships.
- Rising demand for data-driven performance analysis among golfers fuels adoption, with users seeking precise metrics to improve techniques and optimize gameplay.
- Technological advancements, including AI analytics and mobile app connectivity, make launch monitors more accurate, affordable, and accessible to a broader user base.
- Expansion of golf facilities, indoor simulators, and driving ranges across North America supports increased launch monitor demand, especially in urban areas with climate-driven indoor golf activities.
Market Segment Insights
By Type:
In the North America Golf Launch Monitors Market, indoor launch monitors dominate the segment, capturing the largest market share due to their suitability for year-round use in controlled environments. Their popularity stems from the increasing adoption of indoor golf simulators for training and entertainment. Outdoor launch monitors follow, benefiting from their portability and accuracy in real course conditions. Mobile launch monitors, while growing, hold a smaller share as users increasingly seek convenience and real-time data access through compact devices. The demand for versatile, user-friendly products drives growth across all type segments.
- For instance, companies like Foresight Sports and SkyTrak offer indoor launch monitors with high accuracy and comprehensive swing analysis, prominently adopted by training facilities and amateur players.
By Technology:
Radar-based technology leads the North America market segment, holding the highest market share thanks to its precise ball tracking and comprehensive data output. It remains favored by both professionals and amateurs for on-course use and advanced analytics. Camera-based systems gain traction due to improvements in image processing and affordability, making them popular for indoor applications. Infrared sensors and Doppler technology hold smaller shares but grow steadily as manufacturers integrate these technologies for enhanced accuracy and diverse functionality.
- For instance, TrackMan's radar system offers exceptional outdoor accuracy with full ball flight tracking and is preferred by tour professionals globally.
Key Growth Drivers
Rising Demand for Data-Driven Performance Analysis
The North America Golf Launch Monitors Market grows rapidly due to increasing demand for data-driven performance improvement among golfers. Professionals and amateurs alike seek precise metrics such as ball speed, launch angle, and spin rate to refine techniques and optimize gameplay. Enhanced accuracy and real-time feedback enable users to track progress and tailor training sessions effectively. This data-centric approach drives adoption across individual players, coaching centers, and golf facilities, fueling continuous market expansion.
- For instance, Rapsodo launch monitors help golfers analyze swing data to identify issues like inconsistent clubface angles and track improvements over time, enabling targeted practice.
Technological Advancements and Innovation
Continuous advancements in sensor technology, software algorithms, and user interfaces stimulate growth in the North American market. Innovations such as AI-powered analytics, augmented reality integration, and mobile app connectivity enhance user experience and accessibility. These improvements make launch monitors more affordable, accurate, and versatile, appealing to a broader customer base. Leading companies invest heavily in R&D to maintain competitive advantage and expand applications beyond professional sports into entertainment and leisure sectors.
- For instance, GCQuad by Foresight Sports combines multi-dimensional sensors with sophisticated software algorithms and mobile app integration, enabling highly accurate and versatile data collection that appeals to leisure and entertainment sectors beyond just professional sports.
Expansion of Golf Facilities and Simulators
The proliferation of golf facilities, indoor simulators, and driving ranges across North America supports the demand for launch monitors. Facility operators incorporate these devices to attract customers by offering advanced training and entertainment options. Urbanization and climate conditions drive growth in indoor golfing venues, where launch monitors play a critical role in replicating real-world experiences. This infrastructure development creates a conducive environment for sustained market growth by increasing product adoption in commercial settings.
Key Trends and Opportunitis
Integration of Mobile and Portable Devices
The market witnesses a strong trend toward compact, mobile launch monitors that offer portability without compromising accuracy. These devices appeal to users seeking convenience and flexibility, allowing on-course data collection and instant analysis through smartphones and tablets. This trend aligns with broader consumer preferences for connected and user-friendly technology, creating opportunities for manufacturers to diversify product portfolios and target casual golfers and technology enthusiasts.
- For instance, the FlightScope Mevo+ is praised for its lightweight design and quick setup, fitting easily into golf bags while offering reliable data for practice on the course or range, meeting the needs of golfers looking for flexibility and connected technology integration.
Growth in Amateur and Recreational Golf Segments
Expanding interest in golf among amateur and recreational players opens significant growth opportunities. Affordable and easy-to-use launch monitors enable these segments to access advanced training tools previously limited to professionals. Golf coaching centers and community clubs increasingly adopt launch monitors to enhance player engagement and skill development. This democratization of golf technology fosters market expansion by tapping into a larger, less saturated customer base.
- For instance, Garmin's Approach R50 combines launch monitor functionality with built-in golf simulator capabilities, offering user-friendly, data-rich practice for recreational golfers at a comparatively lower price point, encouraging more to engage seriously with skill development.
Key Challenges
High Cost of Advanced Launch Monitors
Despite growing demand, the relatively high price of sophisticated launch monitors limits accessibility for many amateur golfers and smaller facilities. Premium devices with comprehensive features remain cost-prohibitive, restricting market penetration beyond professional users. This pricing barrier challenges manufacturers to balance technology complexity with affordability while addressing customer expectations for quality and performance.
Technical Complexity and User Training
The advanced features and data output of golf launch monitors can overwhelm novice users, requiring proper training to maximize benefits. Complexity in device setup, calibration, and interpretation of analytics presents obstacles to widespread adoption among casual golfers and smaller coaching centers. Manufacturers and service providers must invest in user education and develop intuitive interfaces to reduce learning curves and enhance user satisfaction.
Market Fragmentation and Competition
The North America market faces fragmentation due to numerous players offering varied technologies and price points. Intense competition pressures companies to innovate rapidly while managing costs, risking product overlap and customer confusion. Differentiating offerings and maintaining brand loyalty become critical challenges in sustaining market share amidst evolving consumer preferences and emerging new entrants.
Regional Analysis
United States
The United States dominates the North America Golf Launch Monitors Market, capturing the largest share due to a well-established golf culture and widespread adoption of advanced training technologies. It accounts for 75% of the regional market. High disposable incomes, extensive golf course infrastructure, and strong presence of key market players drive demand. Additionally, growing interest in data-driven performance improvement among both professional and amateur golfers supports sustained market growth. The U.S. market benefits from continuous innovation and investment, making it the pivotal contributor to North America’s overall market expansion.
Canada
Canada holds the second-largest share in the North America Golf Launch Monitors Market, representing 18% of the regional market. The country experiences increasing adoption of golf simulators and launch monitors, especially in urban areas with harsh winters, encouraging indoor golf activities. Rising recreational participation and investments by golf facilities to enhance training and entertainment options contribute to growth. Canadian golfers’ growing preference for technology-based performance tracking further drives demand. The market in Canada steadily expands, supported by rising disposable incomes and increasing awareness of advanced golf technologies.
Mexico
Mexico accounts for the remaining 7% share of the North America Golf Launch Monitors Market. The market here grows due to increasing popularity of golf as a sport and rising tourism focused on golf resorts. Investments in upscale golf facilities and driving ranges stimulate demand for launch monitors. While adoption rates remain lower compared to the U.S. and Canada, growing interest among amateur golfers and improved accessibility to affordable devices offer significant growth potential. The Mexican market is poised for gradual expansion as infrastructure and technology awareness improve.
Market Segmentations:
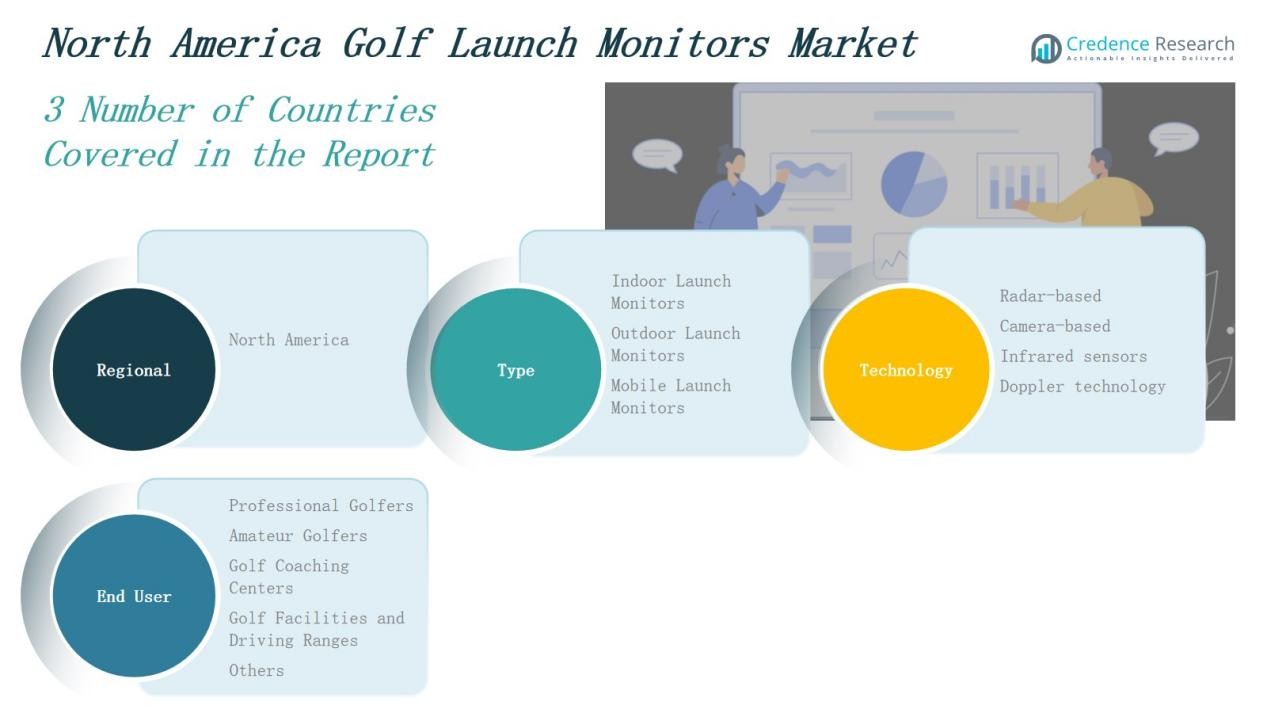
By Type
- Indoor Launch Monitors
- Outdoor Launch Monitors
- Mobile Launch Monitors
By Technology
- Radar-based
- Camera-based
- Infrared Sensors
- Doppler Technology
By End User
- Professional Golfers
- Amateur Golfers
- Golf Coaching Centers
- Golf Facilities and Driving Ranges
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the North America Golf Launch Monitors Market features a mix of established industry leaders and innovative emerging players. Companies such as Foresight Sports, SkyTrak, Full Swing Golf, TruGolf, and FlightScope dominate through advanced product portfolios, continuous technological innovation, and strategic partnerships. These key players invest heavily in research and development to enhance accuracy, user experience, and connectivity features, maintaining their market leadership. Additionally, firms like Garmin Approach, VOICE Caddie, Optishot, Ernest Sports, and Rapsodo contribute to market diversity by targeting different user segments, including professionals, amateurs, and recreational players. Intense competition drives price adjustments and rapid product launches, compelling companies to differentiate through unique features, ease of use, and integration with mobile platforms. The market also witnesses collaboration between technology providers and golf facilities, boosting adoption rates. Overall, the competitive environment encourages innovation while expanding accessibility, supporting steady growth in North America.
Key Players
- Foresight Sports
- SkyTrak
- Full Swing Golf
- TruGolf
- Ernest Sports
- VOICE Caddie
- Garmin Approach
- Optishot
- FlightScope
- Rapsodo
Recent Developments
- In early 2024, Garmin launched the Approach R50, featuring a 10-inch touchscreen, a three-camera system, and built-in simulator capabilities designed to enhance golfer training.
- In May 2024, OptiShot introduced the Nova Simulator, which uses Taylormade TP5 pix golf balls for precise spin axis measurement and offers access to 20 courses without requiring subscription fees.
- In 2024, SkyTrak released the SkyTrak+, integrating photometric and Doppler radar technologies to boost shot accuracy and provide detailed club and ball data.
- On February 6, 2024, Foresight Sports unveiled the Falcon, an overhead launch monitor equipped with quadrascopic camera technology that delivers over a dozen data points per shot with improved accuracy and a larger hitting zone than its predecessor, the GCHawk.
- On December 12, 2024, Foresight Sports formed a strategic partnership with Whoosh to offer a comprehensive simulator management solution by combining advanced simulation technology with Whoosh’s booking and operations software.
Market Concentration & Characteristics
The North America Golf Launch Monitors Market demonstrates a moderately concentrated structure, dominated by a few key players such as Foresight Sports, SkyTrak, and Full Swing Golf that command a significant portion of the market share. These companies lead through continuous innovation, strong brand presence, and extensive distribution networks. It features a diverse product range catering to professional golfers, amateurs, coaching centers, and commercial facilities. The market emphasizes advanced technology integration, including radar and camera-based systems, to deliver accurate performance data. Competitive dynamics encourage ongoing investment in research and development to enhance device precision, portability, and user interface. The market also experiences steady growth driven by rising consumer demand for data-driven training tools and the expansion of golf infrastructure. It maintains a balance between high-end, premium products and more affordable options targeting broader user segments, ensuring accessibility and fostering wider adoption across North America.
Report Coverage
The research report offers an in-depth analysis based on Type, Technology, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The North America Golf Launch Monitors Market will expand due to increasing demand for precise performance tracking.
- Innovation in sensor technology will drive development of more accurate and user-friendly devices.
- Mobile and portable launch monitors will gain popularity among amateur and recreational golfers.
- Integration with mobile applications and cloud platforms will enhance user experience and data accessibility.
- Golf coaching centers and facilities will increasingly adopt launch monitors to improve training quality.
- Rising interest in indoor golf simulators will boost demand for indoor launch monitors.
- Expansion of golf infrastructure in urban areas will support market growth.
- Product affordability will improve, making launch monitors accessible to a wider audience.
- Collaboration between manufacturers and golf facilities will accelerate technology adoption.
- Increasing awareness of data-driven training benefits will encourage broader use among all skill levels.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Data-Driven Performance Analysis
Golfers at all skill levels increasingly seek precise metrics such as ball speed, launch angle, and spin rate to refine their techniques and optimize gameplay. This focus on measurable improvement fuels adoption of launch monitors across individual users, coaching centers, and golf facilities.
Technological Advancements and Innovation
Continuous improvements in sensor technology, AI-powered analytics, and mobile app integration have made launch monitors more accurate, affordable, and user-friendly. These innovations expand the market by appealing to both professionals and recreational golfers.
Expansion of Golf Facilities and Indoor Simulators
The growth of indoor golf venues and driving ranges, especially in urban areas and regions with challenging climates, drives demand for launch monitors. Facility operators use these devices to enhance training and entertainment offerings, increasing product adoption.
Growth in Amateur and Recreational Golf Segments
Affordable and easy-to-use launch monitors are making advanced golf technology accessible to amateurs and recreational players. This democratization of technology expands the customer base and supports market growth beyond the professional segment.
Integration of Mobile and Portable Devices
The trend toward compact, portable launch monitors that connect with smartphones and tablets meets consumer demand for convenience and flexibility. This enables on-course data collection and instant analysis, attracting new users and supporting broader adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for North America Golf Launch Monitors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America Golf Launch Monitors Market projected to grow between 2025 and 2032?
Which North America Golf Launch Monitors Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the North America Golf Launch Monitors Market?
Who are the leading companies in the North America Golf Launch Monitors Market?
Which region commanded the largest share of the North America Golf Launch Monitors Market market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Indoor Launch Monitors
- 1.2.2 Outdoor Launch Monitors
- 1.2.3 Mobile Launch Monitors
- 1.3 By End User
- 1.3.1 Professional Golfers
- 1.3.2 Amateur Golfers
- 1.3.3 Golf Coaching Centers
- 1.3.4 Golf Facilities and Driving Ranges
- 1.3.5 Others
- 1.4 By Technology
- 1.4.1 Radar-based
- 1.4.2 Camera-based
- 1.4.3 Infrared Sensors
- 1.4.4 Doppler Technology
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 103.26 million → 2032: USD 205.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Golf Launch Monitors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Golf Launch Monitors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Golf Launch Monitors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Golf Launch Monitors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Golf Launch Monitors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Golf Launch Monitors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Golf Launch Monitors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Golf Launch Monitors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 103.26 million → 2032: USD 205.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Golf Launch Monitors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Indoor Launch Monitors
- 12.3.7.2 Outdoor Launch Monitors
- 12.3.7.3 Mobile Launch Monitors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Professional Golfers
- 12.4.7.2 Amateur Golfers
- 12.4.7.3 Golf Coaching Centers
- 12.4.7.4 Golf Facilities and Driving Ranges
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Radar-based
- 12.5.7.2 Camera-based
- 12.5.7.3 Infrared Sensors
- 12.5.7.4 Doppler Technology
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 North America Golf Launch Monitors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Golf Launch Monitors Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Golf Launch Monitors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Golf Launch Monitors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Foresight Sports
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SkyTrak
- 18.4 Full Swing Golf
- 18.5 TruGolf
- 18.6 Ernest Sports
- 18.7 VOICE Caddie
- 18.8 Garmin Approach
- 18.9 Optishot
- 18.10 FlightScope
- 18.11 Rapsodo
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

