
Market Overview
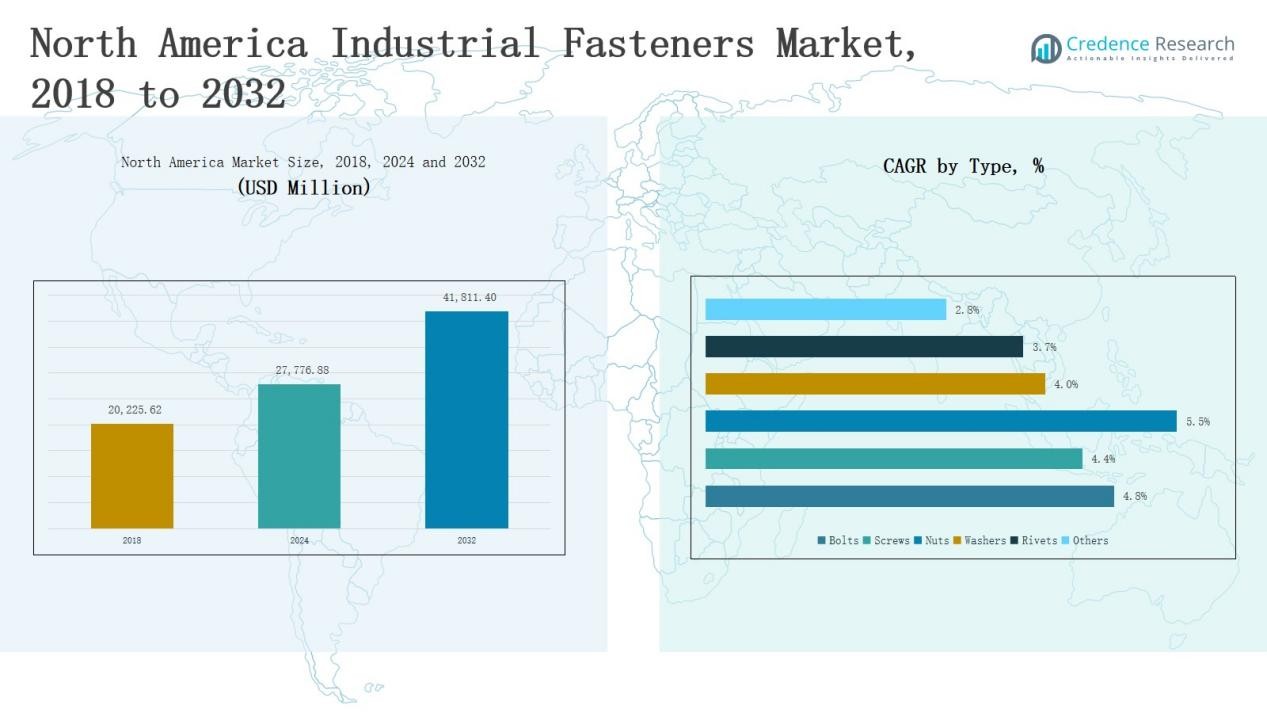
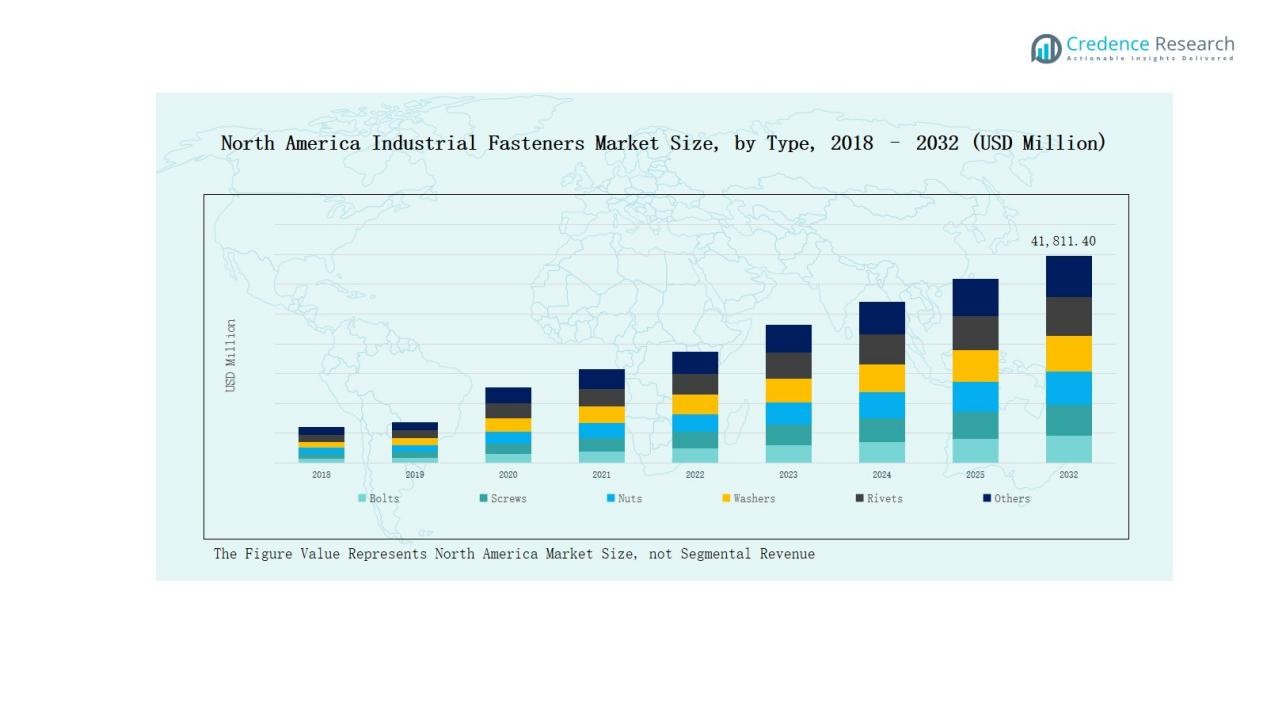
North America Industrial Fasteners Market size was valued at USD 20,225.62 million in 2018, grew to USD 27,776.88 million in 2024, and is anticipated to reach USD 41,811.40 million by 2032, expanding at a CAGR of 4.88% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Industrial Fasteners Market Size 2024 | USD 27,776.88 Million |
| North America Industrial Fasteners Market, CAGR | 4.88% |
| North America Industrial Fasteners Market Size 2032 | USD 41,811.40 Million |
The North America Industrial Fasteners Market is led by prominent companies such as ARaymond Industrial, Marmon Holdings Inc. (Berkshire Hathaway), Fontana Gruppo, Illinois Tool Works Inc., Stanley Black & Decker Inc., and LISI Group. These players maintain leadership through advanced manufacturing technologies, extensive product portfolios, and strategic partnerships across automotive, aerospace, and construction industries. Continuous investment in lightweight, corrosion-resistant, and high-performance fasteners strengthens their competitive edge. The United States emerged as the leading region in 2024, capturing a 76% market share, driven by strong industrial infrastructure and expanding production capabilities.
Market Insights
- The North America Industrial Fasteners Market grew from USD 20,225.62 million in 2018 to USD 27,776.88 million in 2024 and is expected to reach USD 41,811.40 million by 2032, expanding at a CAGR of 4.88%.
- Bolts dominated the market by type in 2024 with a 32% share, driven by their high tensile strength and wide use across automotive, aerospace, and construction industries.
- Externally Threaded Fasteners held the largest product share of 41% in 2024, supported by their reliability, easy maintenance, and use in structural and machinery applications.
- Pre-Applied Fasteners led the category segment with a 57% share in 2024, boosted by automation in assembly lines and growing demand for vibration-resistant, time-saving fastening solutions.
- The United States led the regional market with a 76% share in 2024, backed by robust manufacturing, infrastructure investment, and innovation in high-performance and coated fasteners.
Market Segment Insights
By Type:
Bolts dominated the North America Industrial Fasteners Market in 2024 with a 32% share. Their high tensile strength, versatility, and suitability for heavy-load applications drive adoption across automotive, aerospace, and construction industries. Continuous innovations in coated and stainless-steel bolts improve corrosion resistance and durability. Expanding infrastructure projects and vehicle production further strengthen demand, while customized bolt manufacturing for specialized machinery applications enhances market penetration across the region.
- For instance, Hilti North America introduced its new line of HUS4‑H 3/4" screw bolts, engineered for enhanced load-bearing capacity and simplified installation in structural concrete applications.
By Product:
Externally Threaded Fasteners accounted for the largest market share of 41% in 2024. These fasteners are widely used in automotive assemblies, machinery, and structural applications requiring strong mechanical bonding. Their ability to provide high clamping force and easy maintenance supports their dominance. Increasing use of advanced materials and precision-engineered designs also improves load-bearing performance. Rising investments in aerospace and defense manufacturing further stimulate demand for high-strength externally threaded fasteners.
- For instance, Ankit Group manufactures high-grade aerospace fasteners from materials like alloy steel and titanium, meeting stringent NADCAP quality standards to withstand extreme environments in defense and satellite systems.
By Category:
Pre-Applied Fasteners led the market in 2024 with a 57% share, driven by rising automation in assembly lines and growing focus on reducing installation time. These fasteners come with pre-applied adhesives or sealants, ensuring consistent torque and vibration resistance. They are increasingly preferred in automotive, electronics, and industrial equipment manufacturing. Demand is supported by cost efficiency, enhanced safety, and reduced maintenance needs, making pre-applied solutions the preferred choice among OEMs and large-scale producers.
Key Growth Drivers
Expansion in Automotive and Aerospace Production
The North America Industrial Fasteners Market grows steadily with increased automotive and aerospace output. Rising production of electric vehicles, aircraft, and defense systems fuels fastener demand for precision and high-strength components. Manufacturers adopt lightweight alloys and corrosion-resistant coatings to meet performance standards. Continuous R&D in advanced fastening technologies ensures structural safety and supports automation. This industrial expansion, combined with government-backed manufacturing initiatives, significantly strengthens fastener consumption across the region’s transportation and aviation sectors.
- For instance, in aerospace, major players like Boeing and Lockheed Martin continuously require advanced fastening solutions; Howmet Aerospace introduced new high-performance fasteners tailored for aerospace applications in the recent years, emphasizing innovations in lightweight alloys and corrosion-resistant coatings.
Increasing Adoption of High-Performance Materials
Demand for durable and corrosion-resistant fasteners drives market growth. Industries prefer stainless steel, titanium, and engineered polymer fasteners for superior performance under extreme temperatures and stress conditions. The shift toward lightweight materials in aerospace and electric vehicles enhances fuel efficiency and sustainability. Moreover, the integration of smart coating technologies improves longevity and maintenance cycles. These innovations enable manufacturers to meet strict quality and safety standards, fostering greater adoption of high-performance fastening solutions in critical industrial applications.
- For instance, Boeing expanded its use of titanium fasteners in the 777X aircraft program to achieve higher strength-to-weight ratios and improve performance under thermal stress.
Infrastructure Development and Construction Activities
Rising infrastructure investment across North America creates strong demand for industrial fasteners. Public projects in transportation, renewable energy, and commercial construction use heavy-duty bolts, nuts, and anchors for long-term stability. Increasing adoption of prefabricated building systems also boosts fastener consumption. Governments in the U.S. and Canada continue to fund highway, bridge, and energy infrastructure upgrades. This sustained construction momentum directly contributes to the expansion of the regional fastener market, supporting both domestic production and import opportunities.
Key Trends & Opportunities
Shift Toward Smart and Coated Fasteners
Manufacturers increasingly focus on developing coated and sensor-embedded fasteners for predictive maintenance. Smart coatings reduce corrosion and enhance load monitoring, enabling real-time data collection on stress or fatigue. This technological shift aligns with Industry 4.0 trends in connected manufacturing. The aerospace, automotive, and renewable sectors benefit from enhanced safety, reduced downtime, and longer component lifespans, creating major opportunities for innovation-driven fastener producers across North America.
- For instance, CORROSHIELD®, CS Series coating offers superior anti-corrosion protection, enduring over 1000 hours in salt spray tests and 15 cycles in sulfur dioxide chambers, making it ideal for outdoor use in automotive and aerospace sectors.
Growing Penetration of E-Commerce and Direct Distribution
The digital transformation of supply chains fuels growth opportunities in online fastener distribution. E-commerce platforms simplify bulk ordering and improve supply visibility for industrial buyers. Direct-to-customer models reduce procurement time and expand manufacturer reach. Growing preference for digital inventory management, coupled with the availability of customizable fasteners, strengthens sales networks. This trend enhances competitiveness among local suppliers and encourages integration of logistics automation across North America’s fastener industry.
- For instance, MSC Industrial Supply upgraded its e-commerce interface with advanced search filters for specification-based fasteners, improving product accessibility and accelerating procurement for industrial users.
Key Challenges
Fluctuating Raw Material Prices
Volatility in steel, aluminum, and alloy prices poses a persistent challenge for fastener manufacturers. Supply chain disruptions and global trade tensions influence production costs, affecting profit margins. Many suppliers struggle to balance pricing with customer demand amid market instability. The industry increasingly relies on long-term supplier contracts and recycled materials to stabilize expenses. However, continuous price fluctuations remain a critical barrier to achieving consistent profitability in the North America Industrial Fasteners Market.
Rising Competition from Low-Cost Imports
Manufacturers in North America face growing competition from Asian producers offering cheaper alternatives. These imports exert pricing pressure and challenge domestic firms to maintain quality and delivery efficiency. Local companies respond by emphasizing customized products, faster lead times, and advanced materials. However, the cost gap remains substantial. Strategic trade policies and investment in automation are crucial to sustaining the region’s competitiveness against foreign fastener manufacturers.
Labor Shortages and Production Constraints
Skilled labor shortages in manufacturing and metalworking continue to hinder productivity. Advanced fastener production requires precision machining and process expertise, which are increasingly difficult to source. The ongoing labor gap leads to delays, reduced output, and higher operational costs. Automation adoption offers partial relief but demands high capital investment. To address this challenge, companies are expanding training programs and exploring robotics integration to maintain steady production levels and meet growing regional demand.
Regional Analysis
United States
The United States dominated the North America Industrial Fasteners Market in 2024 with a 76% share. Strong industrial manufacturing, expanding automotive output, and aerospace advancements drive market growth. The country’s established supply base and high investment in infrastructure projects sustain demand for metal and specialty fasteners. It benefits from the presence of major manufacturers and distribution networks supporting diverse industrial needs. Growth in electric vehicle production and renewable energy installations further strengthens market expansion. The U.S. also leads innovation in coated and high-performance fasteners, reinforcing its competitive edge.
Canada
Canada accounted for a 24% share of the regional market in 2024, supported by rising construction activities and industrial automation. Its fast-growing aerospace and energy sectors generate consistent demand for durable fastening solutions. Increasing investments in green buildings and transportation infrastructure create new growth opportunities for local producers. It benefits from cross-border trade and technological cooperation with the U.S., ensuring stable supply and product diversification. Manufacturers in Canada focus on stainless steel and corrosion-resistant fasteners for long-term performance in harsh climates. Expanding distribution channels and government-backed industrial modernization initiatives continue to enhance market potential.
Market Segmentations:
By Type:
- Bolts
- Screws
- Nuts
- Washers
- Rivets
- Others
By Product:
- Externally Threaded Fasteners
- Internally Threaded Fasteners
- Non-Threaded Fasteners
- Aerospace Grade Fasteners
By Category:
- Pre-Applied Fasteners
- Post-Applied Fasteners
By Material:
- Metal
- Plastic
By Application:
- Automotive
- Aerospace
- Building & Construction
- Industrial Machinery
- Electronics & Energy
- Others
By Distribution Channel:
- Direct
- Indirect
By Region:
- U.S.
- Canada
Competitive Landscape
The North America Industrial Fasteners Market is highly competitive, with global and regional players focusing on product innovation, material advancement, and expansion of manufacturing capacities. Leading companies such as ARaymond Industrial, Marmon Holdings Inc. (Berkshire Hathaway), Fontana Gruppo, Illinois Tool Works Inc., Stanley Black & Decker Inc., and LISI Group dominate through wide product portfolios and strong client relationships across automotive, aerospace, and construction industries. It experiences growing consolidation as firms pursue mergers, acquisitions, and partnerships to expand geographic reach and technological expertise. Manufacturers increasingly invest in lightweight alloys, coated fasteners, and smart fastening systems to meet evolving industrial requirements. Emerging players strengthen competitiveness by offering cost-effective customized solutions and digital procurement platforms. Strategic collaborations, automation in production, and focus on sustainability remain key differentiators shaping the long-term competitive dynamics of the North America Industrial Fasteners Market.
Key Players
- ARaymond Industrial
- Marmon Holdings Inc. (Berkshire Hathaway)
- Fontana Gruppo
- Illinois Tool Works Inc.
- Stanley Black & Decker Inc.
- LISI Group
- Nifco Inc.
- Birmingham Fastener Inc.
- Portland Bolt & Manufacturing Company Inc.
- BTM Manufacturing
- L3Harris Technologies Inc.
- Astronics Corporation
- Ducommun Incorporated
- KD Fasteners Inc
- Buckeye Fasteners Company
Recent Developments
- In July 2025, Spartan Fastener acquired American Jebco to expand its specialty fasteners and rivets portfolio across North America.
- In April 2024, TR Fastenings launched its new Plas-Tech 30-20 screw designed for high-performance plastic applications.
- In July 2025, Signature Engineered Solutions entered a partnership to distribute Unbrako fasteners throughout the North American market.
- In July 2024, Lamons completed the acquisition of Auge Industrial Fasteners to enhance its global fastening solutions portfolio.
Report Coverage
The research report offers an in-depth analysis based on Type, Product Category, Material, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for lightweight and high-strength fasteners will increase across automotive and aerospace industries.
- Manufacturers will focus on automation and robotics to improve production efficiency and consistency.
- The adoption of corrosion-resistant coatings will expand in marine and construction applications.
- Digital procurement platforms will streamline supply chains and enhance customer accessibility.
- Smart fasteners with embedded sensors will gain traction in advanced manufacturing systems.
- Sustainability goals will drive the use of recyclable materials and energy-efficient processes.
- Infrastructure investments across the U.S. and Canada will create steady demand for heavy-duty fasteners.
- Partnerships between OEMs and fastener suppliers will strengthen localized production networks.
- Expansion of e-commerce distribution will improve market penetration for small and mid-sized producers.
- Continuous innovation in design and materials will define competitive advantage among leading market players.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion in Automotive and Aerospace Production
Increased output of vehicles and aircraft in North America is driving demand for high-strength, precision fasteners. The shift toward electric vehicles and advanced aerospace systems requires innovative fastening solutions that meet stringent safety and performance standards.
Increasing Adoption of High-Performance Materials
Industries are prioritizing fasteners made from stainless steel, titanium, and engineered polymers for their durability and resistance to corrosion and extreme conditions. This trend is especially strong in aerospace, automotive, and energy applications, supporting market growth for advanced material fasteners.
Infrastructure Development and Construction Activities
Ongoing investments in transportation, renewable energy, and commercial construction across the U.S. and Canada are fueling demand for heavy-duty and specialty fasteners. Public infrastructure projects and the adoption of prefabricated building systems further boost fastener consumption.
Shift Toward Smart and Coated Fasteners
Manufacturers are developing coated and sensor-embedded fasteners that offer enhanced corrosion resistance and enable predictive maintenance. These innovations align with Industry 4.0 trends and are increasingly adopted in automotive, aerospace, and renewable energy sectors.
Growing Penetration of E-Commerce and Direct Distribution
Digital transformation of supply chains and the rise of e-commerce platforms are making it easier for industrial buyers to source fasteners efficiently. Direct-to-customer models and online procurement are expanding market reach and streamlining distribution.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for North America Industrial Fasteners Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America Industrial Fasteners Market projected to grow between 2025 and 2032?
Which North America Industrial Fasteners Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the North America Industrial Fasteners Market?
Who are the leading companies in the North America Industrial Fasteners Market?
Which region commanded the largest share of the North America Industrial Fasteners Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Bolts
- 1.2.2 Screws
- 1.2.3 Nuts
- 1.2.4 Washers
- 1.2.5 Rivets
- 1.2.6 Others
- 1.3 By Product
- 1.3.1 Externally Threaded Fasteners
- 1.3.2 Internally Threaded Fasteners
- 1.3.3 Non-Threaded Fasteners
- 1.3.4 Aerospace Grade Fasteners
- 1.4 By Material
- 1.4.1 Metal
- 1.4.2 Plastic
- 1.5 By Application
- 1.5.1 Automotive
- 1.5.2 Aerospace
- 1.5.3 Building & Construction
- 1.5.4 Industrial Machinery
- 1.5.5 Electronics & Energy
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 27,776.88 million → 2032: USD 41,811.40 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North American Industrial Fasteners Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North American Industrial Fasteners Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North American Industrial Fasteners Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North American Industrial Fasteners Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North American Industrial Fasteners Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North American Industrial Fasteners Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North American Industrial Fasteners Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North American Industrial Fasteners Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 27,776.88 million → 2032: USD 41,811.40 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North American Industrial Fasteners Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bolts
- 12.3.7.2 Screws
- 12.3.7.3 Nuts
- 12.3.7.4 Washers
- 12.3.7.5 Rivets
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Externally Threaded Fasteners
- 12.4.7.2 Internally Threaded Fasteners
- 12.4.7.3 Non-Threaded Fasteners
- 12.4.7.4 Aerospace Grade Fasteners
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Metal
- 12.5.7.2 Plastic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Automotive
- 12.6.7.2 Aerospace
- 12.6.7.3 Building & Construction
- 12.6.7.4 Industrial Machinery
- 12.6.7.5 Electronics & Energy
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 North American Industrial Fasteners End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North American Industrial Fasteners Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North American Industrial Fasteners Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North American Industrial Fasteners Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ARaymond Industrial
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Marmon Holdings Inc. (Berkshire Hathaway)
- 18.4 Fontana Gruppo
- 18.5 Illinois Tool Works Inc.
- 18.6 Stanley Black & Decker Inc.
- 18.7 LISI Group
- 18.8 Nifco Inc.
- 18.9 Birmingham Fastener Inc.
- 18.10 Portland Bolt & Manufacturing Company Inc.
- 18.11 BTM Manufacturing
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

