
Market Overview
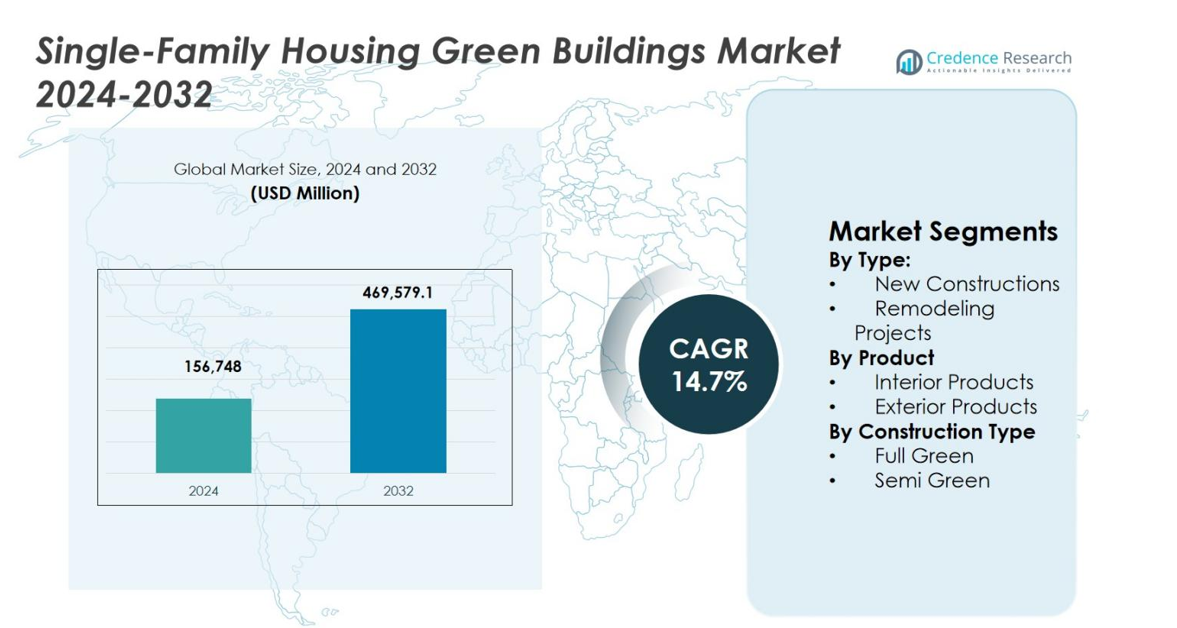
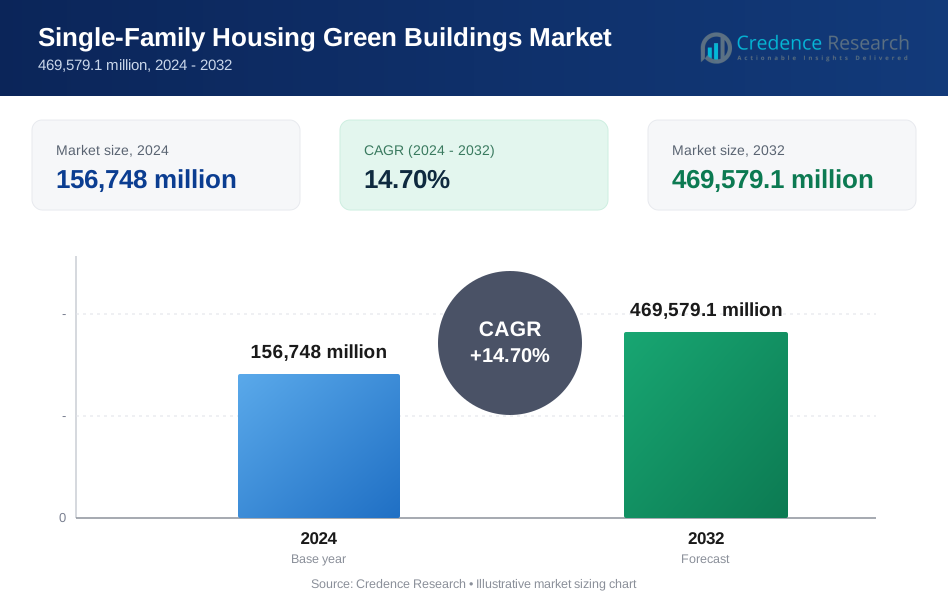
The Single-Family Housing Green Buildings Market size was valued at USD 156,748 million in 2024 and is anticipated to reach USD 469,579.1 million by 2032, growing at a CAGR of 14.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Single-Family Housing Green Buildings Market Size 2024 | USD 156,748 million |
| Single-Family Housing Green Buildings Market, CAGR | 14.7% |
| Single-Family Housing Green Buildings Market Size 2032 | USD 469,579.1 million |
Single-Family Housing Green Buildings Market is shaped by the strong presence of established construction and engineering firms such as Turner Construction Co., Skanska USA, AECOM, The Gilbane Building Co., Clark Group, Hensel Phelps, Whiting-Turner Contracting Co., Holder Construction, Webcor Builders, and Structure Tone. These companies focus on energy-efficient residential designs, green certification expertise, and integration of smart and sustainable building technologies to support single-family housing developments. North America leads the market with a 34.6% share, driven by stringent energy regulations, high consumer awareness, and advanced green construction practices. Europe follows with a 29.8% share, supported by climate-focused policies and mandatory sustainability standards, while Asia-Pacific accounts for a 24.1% share, reflecting accelerating adoption of green single-family housing across emerging and developed economies.
Market Insights
- Single-Family Housing Green Buildings Market was valued at USD 156,748 million in 2024 and is projected to reach USD 469,579.1 million by 2032, growing at a CAGR of 14.7% during the forecast period.
- Market growth is driven by strict energy-efficiency regulations, government incentives, rising energy costs, and increasing preference for sustainable and low-carbon single-family homes.
- Key market trends include higher adoption of smart energy management systems, green-certified materials, and integrated sustainable design, with New Constructions leading at 64.2% segment share in 2024.
- The market features strong participation from large construction firms focusing on green certifications, smart technologies, and lifecycle efficiency, while high initial costs and skilled labor gaps act as restraints.
- Regionally, North America leads with 34.6% market share, followed by Europe at 29.8% and Asia-Pacific at 24.1%, reflecting strong regulatory support and expanding green housing adoption.
Market Segmentation Analysis:
By Type:
The Single-Family Housing Green Buildings Market shows clear dominance of New Constructions, which accounted for 64.2% market share in 2024, driven by rising adoption of energy-efficient designs at the planning stage. New green homes integrate solar panels, advanced insulation, smart HVAC systems, and sustainable materials more effectively than retrofits, ensuring compliance with green building codes and certifications. Government incentives, tax benefits, and stricter energy-efficiency regulations further support new green residential developments. In contrast, Remodeling Projects remain important but are limited by higher retrofit costs and structural constraints compared to purpose-built green homes.
- For instance, Nathan Good Architects designed the Cannon Beach Home in Oregon with a 5.9kW photovoltaic solar system, high insulation, sustainable salvaged materials, and a rooftop garden for rainwater filtration, prioritizing environmental impact reduction from the outset.
By Product:
Within the Single-Family Housing Green Buildings Market, Interior Products dominated with a 58.6% market share in 2024, supported by strong demand for energy-efficient lighting, insulation, flooring, low-VOC paints, and smart home systems. Homeowners prioritize interior upgrades that directly reduce energy consumption, improve indoor air quality, and enhance living comfort. Growing awareness of health benefits and long-term operational cost savings continues to drive interior product adoption. Exterior Products, including green roofing and sustainable cladding, maintain steady growth but contribute a smaller share due to higher upfront installation costs.
- For instance, Benjamin Moore's Eco Spec interior paint features a zero-VOC formula with less than 5g of volatile organic compounds per liter, certified Green Seal and asthma/allergy friendly to minimize emissions and improve indoor air quality.
By Construction Type:
The Full Green segment led the Single-Family Housing Green Buildings Market with a 61.8% market share in 2024, driven by comprehensive sustainability integration across energy, water, materials, and waste management systems. Full green homes achieve higher certification levels and deliver superior lifecycle cost savings, making them attractive to environmentally conscious buyers. Increasing availability of green financing and supportive policy frameworks accelerates adoption. Meanwhile, Semi Green constructions remain relevant for cost-sensitive buyers but offer limited performance benefits compared to fully integrated green residential structures.
Major Key Growth Drivers
Government Regulations and Incentive Programs
The Single-Family Housing Green Buildings Market benefits strongly from supportive government regulations and financial incentive programs promoting sustainable residential construction. Policies mandating higher energy-efficiency standards, carbon reduction targets, and green building certifications encourage developers to adopt environmentally responsible designs. Tax credits, subsidies, and low-interest green mortgages reduce upfront costs for homeowners and builders, improving affordability. Public sector initiatives focused on net-zero housing and climate resilience further accelerate adoption, creating a favorable regulatory environment that consistently stimulates demand for green single-family homes across developed and emerging markets.
- For instance, Ashok B Lall Architects developed the Net Zero Carbon Homes pilot with five 2BHK single-family units achieving an Energy Performance Intensity of 32 kWh/m²/year through low-carbon materials and smart technologies.
Rising Energy Costs and Long-Term Cost Savings
Escalating energy prices significantly drive growth in the Single-Family Housing Green Buildings Market by increasing the economic appeal of energy-efficient homes. Green buildings reduce electricity and water consumption through high-performance insulation, solar integration, efficient HVAC systems, and smart energy management. These features lower long-term utility expenses and protect homeowners from energy price volatility. Growing awareness of lifecycle cost benefits strengthens buyer preference for sustainable housing, encouraging developers to incorporate green technologies as standard features rather than optional upgrades.
- For instance, Chinburg Properties built high-performance green homes in New Hampshire seacoast developments using advanced insulation and energy-efficient systems.
Growing Consumer Awareness and Sustainability Preferences
Increasing consumer awareness regarding environmental impact and health benefits strongly supports expansion of the Single-Family Housing Green Buildings Market. Homebuyers increasingly prioritize indoor air quality, natural lighting, non-toxic materials, and reduced carbon footprints. Sustainability has become a key purchasing criterion, particularly among younger homeowners and environmentally conscious families. This shift in buyer behavior motivates builders to differentiate projects through green certifications and eco-friendly features, reinforcing demand and encouraging wider adoption of sustainable construction practices in the single-family housing sector.
Key Trends & Opportunities
Integration of Smart Home and Energy Management Technologies
The Single-Family Housing Green Buildings Market is witnessing a strong trend toward integrating smart home technologies with green construction. Advanced energy management systems, smart thermostats, automated lighting, and real-time energy monitoring optimize resource consumption and enhance user convenience. These technologies improve energy efficiency while enabling homeowners to track and control usage patterns. The convergence of digitalization and sustainability creates opportunities for technology providers and builders to offer value-added, future-ready green homes that align with evolving consumer expectations.
- For instance, Google's Nest Learning Thermostat achieved 12% average electricity savings for heating in 174 Oregon homes equipped with heat pumps, by learning occupancy patterns and adjusting temperatures automatically.
Expansion of Green Financing and Mortgage Solutions
The growing availability of green financing solutions presents a major opportunity within the Single-Family Housing Green Buildings Market. Financial institutions increasingly offer preferential mortgage rates, extended loan tenures, and sustainability-linked financing for certified green homes. These instruments lower ownership costs and expand accessibility for middle-income buyers. As lenders integrate environmental criteria into risk assessment models, green homes gain financial advantages over conventional housing, encouraging broader market adoption and supporting long-term growth.
- For instance, Union Bank of India’s Union Green Home loan provides a 10 basis point interest rate concession for IGBC- or other certified green homes, with no regulatory cap on loan amount and eligibility extending to both new construction and purchase of certified residential properties.
Key Challenges
High Initial Construction and Material Costs
High upfront costs remain a significant challenge in the Single-Family Housing Green Buildings Market. Sustainable materials, energy-efficient systems, and certification processes often increase initial construction expenses compared to conventional homes. These costs can deter price-sensitive buyers and small-scale developers, particularly in emerging markets. Although long-term savings offset initial investments, limited awareness and financing gaps restrict widespread adoption, slowing market penetration in cost-conscious regions.
Limited Skilled Workforce and Standardization Gaps
The Single-Family Housing Green Buildings Market faces challenges related to shortages of skilled labor and inconsistent construction standards. Green building practices require specialized expertise in energy modeling, sustainable materials, and integrated system design. Insufficient training and certification programs limit workforce readiness, increasing project timelines and costs. Additionally, varying regional standards and certification frameworks create complexity for developers operating across multiple markets, hindering scalability and uniform implementation of green housing solutions.
Regional Analysis
North America
The Single-Family Housing Green Buildings Market in North America accounted for 34.6% market share in 2024, supported by strong regulatory enforcement and high sustainability awareness. The region has demonstrated steady expansion since 2018, driven by strict energy-efficiency building codes and widespread adoption of certified green homes. The United States leads regional demand due to favorable incentives, advanced construction practices, and increasing development of net-zero single-family housing. High penetration of smart energy systems and long-term decarbonization goals continue to reinforce market growth.
Europe
Europe held a 29.8% share of the Single-Family Housing Green Buildings Market in 2024, underpinned by stringent climate policies and mandatory green construction standards. The market has expanded consistently since 2018, led by Germany, the UK, and France. Strong emphasis on low-emission housing, sustainable materials, and energy-efficient renovation programs supports adoption. Alignment with ESG objectives and regulatory compliance requirements continues to position Europe as a mature and stable regional market for green single-family housing.
Asia-Pacific
Asia-Pacific captured a 24.1% market share in 2024, emerging as a key growth region in the Single-Family Housing Green Buildings Market. The region has experienced rapid expansion since 2018, driven by urbanization, rising household incomes, and government-led green housing initiatives. China, India, Japan, and Australia play central roles in advancing sustainable residential development. Increasing awareness of energy efficiency and expanding investments in eco-friendly housing infrastructure continue to strengthen regional adoption.
Latin America
Latin America accounted for 6.8% market share in 2024, reflecting steady progress in sustainable single-family housing adoption since 2018. Brazil, Mexico, and Chile lead regional activity through urban sustainability programs and improving access to green financing. Rising energy costs and alignment with international green building standards encourage developers to incorporate energy-efficient designs. Despite slower adoption compared to developed regions, the market shows consistent momentum supported by policy and infrastructure improvements.
Middle East & Africa
The Middle East & Africa held a 4.7% share of the Single-Family Housing Green Buildings Market in 2024, with gradual expansion since 2018. Growth is concentrated in Gulf countries where sustainability-driven housing policies and energy-efficiency initiatives are gaining importance. Increasing investment in green infrastructure and climate-resilient residential projects supports market development, while broader regional adoption remains influenced by cost sensitivity and varying regulatory maturity.
Market Segmentations:
By Type:
- New Constructions
- Remodeling Projects
By Product
- Interior Products
- Exterior Products
By Construction Type
- Full Green
- Semi Green
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Single-Family Housing Green Buildings Market includes major participants such as Turner Construction Co., Skanska USA, AECOM, The Gilbane Building Co., Clark Group, Hensel Phelps, Whiting-Turner Contracting Co., Holder Construction, Webcor Builders, and Structure Tone. The market features a mix of large integrated construction firms and specialized green building contractors focusing on energy-efficient residential development. Companies compete through sustainable design expertise, green certification capabilities, and adoption of advanced construction technologies. Strategic partnerships with material suppliers, technology providers, and local developers strengthen project execution and scalability. Investment in smart energy systems, prefabrication, and low-carbon construction materials enhances differentiation. Firms increasingly emphasize compliance with regional green standards and lifecycle cost efficiency to attract environmentally conscious homeowners. Continuous innovation, portfolio diversification, and expansion into emerging sustainable housing markets remain central to maintaining long-term competitive positioning.
Key Player Analysis
- Webcor Builders
- Skanska USA
- Holder Construction
- Turner Construction Co.
- Structure Tone
- Whiting-Turner Contracting Co.
- Hensel Phelps
- Clark Group
- The Gilbane Building Co.
- AECOM
Recent Developments
- In April 2025, the U.S. Green Building Council launched LEED v5, an updated green building rating system that strengthens performance and technology criteria for residential projects, including single-family green homes.
- In October 2025, Turner Construction Company was ranked the #1 Green Builder in the United States by Engineering News-Record for the 18th consecutive year, reinforcing its leadership in sustainable building practices.
- In August 2025, International Finance Corporation (IFC) and HDFC Capital partnered to boost green affordable housing finance in India through a dedicated sustainable housing fund, advancing green residential development.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, Construction Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Single-Family Housing Green Buildings Market will continue expanding as sustainability becomes a standard requirement in residential construction.
- Energy-efficient design and low-carbon materials will gain wider adoption across new single-family housing projects.
- Government policies and building codes will increasingly mandate green compliance, supporting long-term market stability.
- Smart home and energy management technologies will become integral components of green residential developments.
- Demand for net-zero and climate-resilient single-family homes will strengthen across both developed and emerging regions.
- Green financing and preferential mortgage schemes will improve affordability and broaden buyer participation.
- Builders will focus on integrated design approaches to optimize lifecycle performance and operational efficiency.
- Prefabrication and modular construction methods will support faster and more sustainable project delivery.
- Consumer preference for healthier indoor environments will drive adoption of non-toxic and low-emission materials.
- Collaboration between developers, technology providers, and policymakers will accelerate innovation and market maturity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Single-Family Housing Green Buildings Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Single-Family Housing Green Buildings Market projected to grow between 2024 and 2032?
What factors are driving the growth of the single-family housing green building market?
What trends are shaping the landscape of single-family housing green building?
What drives the growth of single-family green building from an economic perspective?
What challenges does the single-family housing green building market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Single-Family Housing Green Buildings Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Single-Family Housing Green Buildings Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: 156,748 million → 2032: 469,579.1 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Single-Family Housing Green Buildings Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Single-Family Housing Green Buildings Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Single-Family Housing Green Buildings Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Single-Family Housing Green Buildings Market Drivers
- 3.3 Single-Family Housing Green Buildings Market Restraints & Challenges
- 3.4 Single-Family Housing Green Buildings Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Single-Family Housing Green Buildings Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Single-Family Housing Green Buildings Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Single-Family Housing Green Buildings category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Single-Family Housing Green Buildings Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Single-Family Housing Green Buildings Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Single-Family Housing Green Buildings. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Single-Family Housing Green Buildings Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Single-Family Housing Green Buildings Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Single-Family Housing Green Buildings Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Single-Family Housing Green Buildings (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Single-Family Housing Green Buildings
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Single-Family Housing Green Buildings Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Single-Family Housing Green Buildings Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Single-Family Housing Green Buildings Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Single-Family Housing Green Buildings Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Single-Family Housing Green Buildings Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Single-Family Housing Green Buildings Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Single-Family Housing Green Buildings Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Single-Family Housing Green Buildings Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
