
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Radar and LiDAR Technology for Railways Application market Size 2024 | USD 1,502.25 million |
| Radar and LiDAR Technology for Railways Application market, CAGR | 9.3% |
| Radar and LiDAR Technology for Railways Application market Size 2032 | USD 3,059.87 million |
Market Overview
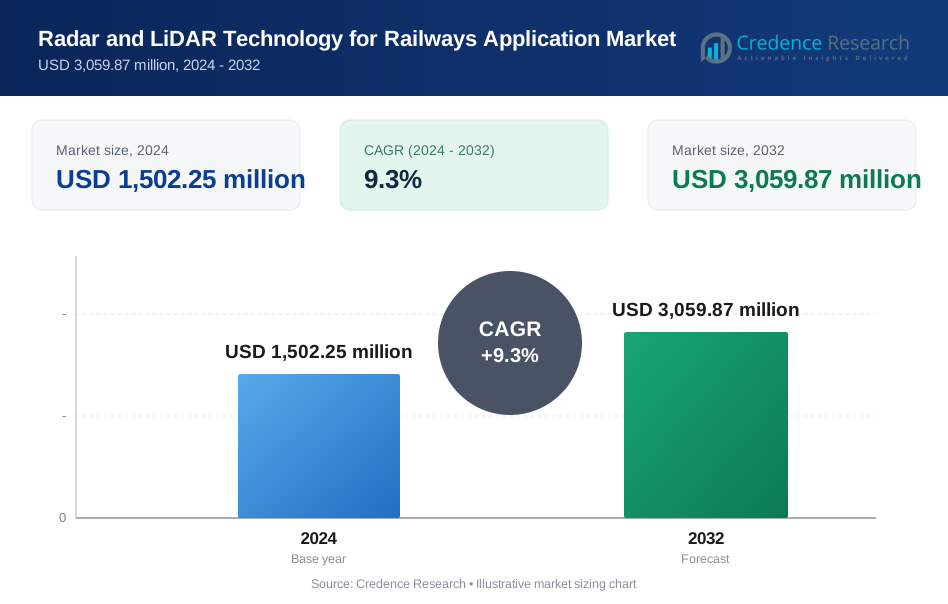
The global Radar and LiDAR Technology for Railways Application market is projected to grow from USD 1,502.25 million in 2024 to USD 3,059.87 million by 2032, registering a CAGR of 9.3% during the forecast period.
The Radar and LiDAR Technology for Railways Application market is driven by the growing emphasis on enhancing railway safety and operational efficiency. Increasing investments in advanced railway infrastructure, coupled with the rising demand for automated and predictive maintenance systems, are fostering the adoption of these technologies. Radar and LiDAR systems offer precise detection and monitoring capabilities, enabling real-time obstacle detection and track condition analysis, which are critical for reducing accidents and delays. Moreover, the integration of artificial intelligence and machine learning in these systems is further enhancing their functionality, driving market growth. The push toward sustainable and smart transportation solutions is also encouraging the use of such advanced technologies, aligning with global efforts to reduce carbon emissions. Additionally, expanding railway networks in emerging economies and the modernization of existing ones in developed regions are creating lucrative opportunities for market players.
The geographical adoption of Radar and LiDAR technologies for railway applications is particularly strong in regions like North America and Europe, where advanced rail networks and a push for automation drive demand for enhanced safety and operational efficiency. In North America, significant investments in smart transportation infrastructure and autonomous train systems are boosting the market for these technologies. Europe, with its strong focus on sustainability and rail modernization, is similarly embracing radar and LiDAR systems for track monitoring, collision avoidance, and predictive maintenance. Key players in this space include DEUTA-WERKE GmbH, Bosch Mobility Solutions, Navtech Radar, Leica Geosystems AG, and BlackBerry Limited, among others. These companies are at the forefront of innovation, providing critical solutions for the rail industry. Additionally, regional players such as Earth Radar Pty Ltd and Radarxense BV contribute to the growing adoption of these advanced technologies, ensuring the continuous development of rail safety and efficiency across global markets.
Market Insights
- The Radar and LiDAR technology market for railway applications is expected to grow from USD 1,502.25 million in 2024 to USD 3,059.87 million by 2032, at a CAGR of 9.3%.
- Increasing demand for autonomous trains and smart transportation systems is driving market growth.
- Radar and LiDAR sensors help improve safety by enabling collision avoidance and real-time track monitoring.
- The integration of AI and machine learning with radar and LiDAR technology enhances predictive maintenance and operational efficiency.
- High initial costs for hardware, installation, and ongoing maintenance are major market restraints.
- Adverse weather conditions and electromagnetic interference can impact the performance of radar and LiDAR systems.
- North America and Europe are leading markets, driven by strong investments in rail infrastructure and advanced rail technologies.
Market Drivers
Enhanced Safety
Radar and LiDAR technologies significantly enhance railway safety by offering collision avoidance capabilities. These sensors detect obstacles, such as other trains, vehicles, or debris on the tracks, enabling early warning systems and automatic braking to prevent accidents. For instance, Indian Railways has implemented a ₹3,200 crore LiDAR technology project to enhance track safety by identifying fractures, faults, and missing sections on railway tracks. Additionally, point detection is crucial, as these technologies can accurately identify and track specific points along the railway line, ensuring safe and efficient train operations. LiDAR’s ability to monitor the condition of tracks is another vital safety feature, identifying potential hazards like cracks, damage, or obstructions. Timely detection of these issues leads to proactive maintenance, reducing derailment risks and ensuring a safe railway environment.
Increased Passenger Comfort
In addition to operational and safety improvements, Radar and LiDAR technologies enhance passenger comfort. LiDAR sensors can accurately detect platform edges, preventing accidents and ensuring passenger safety during boarding and disembarking. Furthermore, these technologies are useful for passenger counting, which helps optimize train capacity and improve service planning. For instance, Bosch Engineering has developed assistance systems that combine radar, LiDAR, and camera technologies to monitor vehicle surroundings and platform areas, enhancing passenger safety and comfort. By accurately tracking the number of passengers entering and exiting trains, operators can better manage crowding, resulting in a more comfortable and efficient travel experience.
Improved Operational Efficiency
Radar and LiDAR technologies play a key role in improving operational efficiency by enhancing train control. These sensors provide real-time data on train location, speed, and surrounding conditions, which is essential for advanced train control systems. This data allows for optimized traffic management, reducing delays and improving overall operational flow. Furthermore, these technologies aid in asset management by monitoring the condition of railway infrastructure, such as bridges, tunnels, and overhead lines. This capability enables proactive maintenance, reducing downtime and extending the lifespan of critical infrastructure. Radar and LiDAR systems are also fundamental in the development of autonomous train operations, which can reduce labor costs, increase efficiency, and improve system reliability.
Emerging Trends and Opportunities
Several emerging trends are driving further opportunities for Radar and LiDAR technology in the railway sector. The integration of AI and machine learning with radar and LiDAR data enhances predictive maintenance and decision-making by enabling advanced analytics. Additionally, the advent of high-speed 5G networks is poised to facilitate real-time data transmission, further elevating the capabilities of these technologies. Multi-sensor fusion, which combines radar and LiDAR data with other sensor modalities like cameras and GPS, provides a more comprehensive understanding of the railway environment, improving both safety and efficiency.
Market Trends
Passenger Comfort and Technological Integration
In addition to safety and operational benefits, Radar and LiDAR technologies significantly enhance passenger comfort by ensuring safer and more efficient boarding processes. LiDAR sensors can accurately detect platform edges, preventing accidents during passenger boarding and alighting, thereby ensuring a safer environment at stations. These technologies also aid in passenger counting, tracking the number of people entering and exiting trains, which helps optimize train capacity and improve service planning to prevent overcrowding. The integration of these technologies with artificial intelligence (AI) and machine learning is opening new avenues for predictive maintenance, advanced analytics, and enhanced decision-making. AI algorithms can process and analyze the data collected by Radar and LiDAR sensors, facilitating smarter decision-making for railway operators. For instance, the integration of AI and IoT with radar and LiDAR systems is enabling real-time data analysis and predictive maintenance, significantly enhancing operational efficiency. Additionally, high-speed 5G connectivity enables real-time data transmission and processing, making it possible to implement more sophisticated applications of Radar and LiDAR technology. Multi-sensor fusion, which combines data from Radar, LiDAR, cameras, and GPS, is also enhancing the ability to understand and respond to the dynamic railway environment, further improving both safety and efficiency.
Enhanced Safety and Operational Efficiency
Radar and LiDAR technologies are revolutionizing railway safety and operational efficiency by enabling advanced safety systems and real-time monitoring capabilities. Collision avoidance is a key driver, as these sensors detect obstacles such as other trains, vehicles, or debris on the tracks, triggering automatic braking and early warning systems to prevent accidents. Point detection and tracking further enhance safety, allowing for precise identification of points along the railway line to ensure smooth and efficient train operations. LiDAR’s ability to monitor track conditions is equally important, identifying potential hazards like cracks or obstructions, which facilitates proactive maintenance and reduces derailment risks. On the operational side, Radar and LiDAR systems provide real-time data on train location, speed, and environmental conditions, supporting advanced train control systems. These systems optimize traffic management, reduce delays, and improve overall operational flow. Additionally, the integration of these technologies into asset management allows for continuous monitoring of infrastructure such as bridges, tunnels, and overhead lines. This capability enables predictive maintenance, reducing downtime and extending the lifespan of critical railway components.
Market Challenges Analysis
High Initial Costs and Ongoing Maintenance Challenges
One of the primary challenges in adopting radar and LiDAR technology for railways is the high initial investment required for hardware, installation, and system integration. The costs of purchasing and setting up radar and LiDAR sensors can be substantial, especially when integrating these systems into existing railway infrastructure. Additionally, the ongoing maintenance and calibration of these sensors further add to operational expenses. Specialized expertise and resources are required to ensure that the sensors are functioning optimally, which increases the overall cost burden for railway operators. As these technologies evolve, continual investment in maintenance and upgrades is necessary to keep pace with advancements, further intensifying financial challenges for the industry.
Environmental, Technical, and Regulatory Barriers
Environmental factors such as adverse weather conditions can severely impact the performance of radar and LiDAR systems, especially LiDAR, which may struggle to operate effectively in heavy rain, fog, or snow. These weather-related challenges create potential reliability issues, which can hinder the overall effectiveness of these technologies in real-time railway operations. Electromagnetic interference from nearby electronic devices or communication systems also poses a threat to radar system performance, further complicating the deployment of these solutions. On the technical side, the large volumes of data generated by radar and LiDAR sensors require sophisticated processing techniques and high-performance computing resources. Additionally, integrating data from multiple sensors, including cameras and GPS, involves complex challenges related to data synchronization and calibration. The lack of standardized protocols and interfaces between different systems and components from various vendors also creates interoperability issues, complicating the seamless exchange of sensor data across different stakeholders. Furthermore, regulatory hurdles related to safety certification and compliance with data privacy and security standards must be navigated. These regulatory processes can be time-consuming and costly, slowing down the adoption of radar and LiDAR technologies. Finally, the need for a skilled workforce capable of operating and maintaining these advanced systems adds another layer of complexity, requiring significant investment in training and development programs to ensure that personnel are adequately prepared.
Market Opportunities
Radar and LiDAR technologies for railway applications present significant market opportunities driven by increasing investments in smart and automated transportation systems. As the global demand for safer, more efficient, and sustainable railway infrastructure grows, these technologies play a pivotal role in enhancing operational efficiency and safety. The expanding use of autonomous trains is one of the most promising opportunities, as radar and LiDAR are essential for real-time environmental sensing, obstacle detection, and track monitoring. With the growing trend toward automation in the transportation sector, the demand for these technologies is expected to rise, creating opportunities for companies specializing in radar and LiDAR systems to expand their offerings. Moreover, the need for predictive maintenance solutions is driving the integration of these technologies into asset management systems. LiDAR sensors, in particular, enable continuous monitoring of railway infrastructure, detecting issues such as track wear and damage before they become critical, which is essential for reducing downtime and improving reliability.
Furthermore, advancements in AI, machine learning, and 5G connectivity are unlocking new opportunities for radar and LiDAR systems. The integration of these technologies with AI allows for the development of more intelligent and efficient railway systems that can autonomously manage train operations, traffic flow, and maintenance schedules. The deployment of 5G networks will further enhance the capabilities of radar and LiDAR systems by enabling real-time data transmission and processing, leading to more sophisticated applications and quicker decision-making. Additionally, the growing focus on sustainable transportation solutions presents opportunities for radar and LiDAR technologies to contribute to reducing energy consumption, emissions, and improving overall operational performance in the railway industry.
Market Segmentation Analysis:
By Radar Technology:
The Radar Technology segment in the railway sector is primarily divided into radar sensor modules and services. Radar sensor modules include speed measurement radar sensors and distance measurement radar sensors, which are essential for train control, traffic management, and obstacle detection. Speed measurement radar sensors are crucial for ensuring train speed limits are adhered to, enhancing operational safety, while distance measurement radar sensors help in monitoring the proximity of objects on the tracks. These sensors contribute to real-time decision-making and collision avoidance systems, which improve railway efficiency and safety. Additionally, the services segment comprises integration & installation services and support services. Integration & installation services are vital for seamlessly incorporating radar systems into existing railway infrastructure, while support services ensure the smooth operation of radar systems through regular maintenance, calibration, and troubleshooting, enhancing the longevity and functionality of the technology. Together, these segments cater to the growing need for enhanced safety and operational efficiency in railways.
By LiDAR Technology:
The LiDAR technology segment in the railway market includes various devices, processing software, and services. LiDAR devices are categorized into mobile LiDAR scanners, aerial LiDAR drones, and on-board LiDAR sensors. Mobile LiDAR scanners are used for track monitoring and asset management, offering precise data for evaluating track conditions. Aerial LiDAR drones provide an efficient means of capturing high-resolution data for extensive rail network surveys, while on-board LiDAR sensors are crucial for real-time monitoring of track conditions, detecting potential hazards, and ensuring safe train operations. LiDAR processing & mapping software plays a critical role in converting raw LiDAR data into actionable insights, supporting maintenance and planning decisions. The services segment includes LiDAR survey & mapping services, consulting services, and support services. LiDAR survey & mapping services are essential for accurate track condition assessments, while consulting services guide the adoption and integration of LiDAR technologies into railway systems. Support services ensure the ongoing performance and reliability of LiDAR systems, which are essential for maintaining railway infrastructure safety and operational efficiency.
Segments:
Based on Radar Technology:
- Radar Sensor Modules
- Speed Measurement Radar Sensors
- Distance Measurement Radar Sensors
- Service
- Integration & Installation Services
- Support Services
Based on LiDAR Technology:
- Devices
- Mobile LiDAR Scanners
- Aerial LiDAR Drones
- On-board LiDAR Sensors
- LiDAR Processing & Mapping Software
- Services
- LiDAR Survey & Mapping Services
- Consulting Services
- Support Services
Based on Application:
- Railway Track Faults Detection
- Rail Collision
- Pedestrian Detection
- Train Tracking & Control
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American region holds a significant share in the Radar and LiDAR technology market for railway applications, accounting for approximately 35% of the global market in 2024. This dominance is primarily driven by the advanced technological infrastructure in the United States and Canada, where rail transport plays a critical role in both freight and passenger services. The increasing demand for autonomous trains and advanced safety systems has led to widespread adoption of radar and LiDAR technologies in this region. Rail operators in North America are increasingly integrating these technologies into their systems to enhance operational efficiency, ensure track safety, and improve passenger experience. Furthermore, the push toward smart transportation solutions and the growing emphasis on predictive maintenance and automation in rail networks are key drivers of market growth. The development of 5G networks and the integration of AI and machine learning further enhance the performance and application of radar and LiDAR systems, making North America a leading market for these technologies. Additionally, government initiatives focused on improving railway safety and reducing accidents are expected to support the region’s continued market leadership.
Europe
Europe also represents a substantial portion of the global market for radar and LiDAR technology in railway applications, with a market share of around 30% in 2024. The region's commitment to sustainable and smart transportation solutions, as well as its strong focus on railway modernization, drives the adoption of radar and LiDAR technologies. European countries such as Germany, France, and the UK are at the forefront of implementing autonomous train systems, advanced track monitoring, and collision avoidance systems, all of which rely heavily on radar and LiDAR technologies. The ongoing investments in railway infrastructure and the push for reducing carbon emissions through efficient rail transport contribute to the high demand for these systems. Moreover, Europe’s stringent safety regulations and emphasis on improving operational reliability drive the market for advanced sensor technologies. With the integration of AI and 5G connectivity in the railway sector, European rail operators are increasingly leveraging radar and LiDAR systems to optimize traffic management, enhance predictive maintenance, and improve passenger safety. The region is expected to continue experiencing growth due to these technological advancements and its commitment to modernizing rail networks.
Key Player Analysis
- DEUTA-WERKE GmbH
- BlackBerry Limited
- Earth Radar Pty Ltd
- Leica Geosystems AG
- Bosch Mobility Solutions
- Hupac Intermodal
- Radarxense BV
- Navtech Radar
- Radar Vision
- ELVA-1
Competitive Analysis
The competitive landscape for Radar and LiDAR technology in railway applications is marked by the presence of several leading players who specialize in advanced sensor solutions. Key players in the market include DEUTA-WERKE GmbH, Bosch Mobility Solutions, Navtech Radar, Leica Geosystems AG, BlackBerry Limited, Earth Radar Pty Ltd, Radarxense BV, Radar Vision, ELVA-1, and Hupac Intermodal. Companies in this sector are continually innovating to offer advanced radar and LiDAR systems that enable improved track monitoring, collision avoidance, and real-time data processing. These systems are essential for enabling autonomous train operations, optimizing traffic management, and ensuring safe and efficient train operations. The integration of radar and LiDAR technology with AI and machine learning algorithms plays a critical role in providing predictive maintenance capabilities, reducing delays, and preventing accidents. Moreover, the growing demand for smart transportation solutions and the ongoing development of railway infrastructure are key factors driving market competition. Companies are also focusing on developing comprehensive sensor fusion systems that combine radar and LiDAR with other modalities like cameras and GPS, allowing for a more complete understanding of the railway environment. Regulatory compliance, such as meeting safety certifications and standards, remains a significant competitive advantage. As the industry embraces new technologies, market players continue to enhance their offerings by focusing on system reliability, data accuracy, and scalability to meet the evolving needs of railway operators and ensure safer, more efficient rail networks.
Market Concentration & Characteristics
The market for Radar and LiDAR technology in railway applications is characterized by moderate concentration, with a few key players dominating the landscape while several smaller and regional players contribute to innovation and growth. The leading companies in this market focus on providing highly specialized solutions tailored to the unique needs of the railway sector, such as collision avoidance, track monitoring, and autonomous train operations. These technologies offer significant advantages in terms of improving safety, operational efficiency, and predictive maintenance. The market is also marked by continuous innovation, with companies integrating AI, machine learning, and sensor fusion technologies to enhance the functionality and performance of radar and LiDAR systems. While large companies with established portfolios dominate the market, smaller players, particularly those focused on niche technologies such as mobile LiDAR scanners or LiDAR drones, are carving out a space by offering unique solutions and services. These companies often partner with railway operators or infrastructure developers to implement custom solutions. The market's characteristics reflect a growing demand for advanced, scalable systems that can integrate with existing railway infrastructure and provide real-time data for improved decision-making. As demand for automation and smart transportation continues to rise, the market is expected to see increased competition, collaboration, and innovation in the coming years.
Report Coverage
The research report offers an in-depth analysis based on Radar Technology, LiDAR Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market for Radar and LiDAR technology in railway applications is expected to see continued growth, driven by increasing demand for autonomous and smart rail systems.
- Integration with AI and machine learning will enhance data processing, enabling more accurate predictive maintenance and operational optimization.
- Enhanced safety features, such as real-time track monitoring and collision avoidance, will become more prevalent across global rail networks.
- The development of autonomous trains will lead to greater reliance on advanced Radar and LiDAR systems for navigation and decision-making.
- Growing investments in rail infrastructure and modernization will create new opportunities for Radar and LiDAR technology adoption.
- Increased collaboration between technology providers and rail operators will lead to more tailored, efficient solutions for the railway sector.
- The introduction of 5G connectivity will enable faster and more reliable data transmission, further improving the capabilities of Radar and LiDAR systems.
- LiDAR systems will play a significant role in enhancing asset management by providing detailed insights into the condition of railway infrastructure.
- Regional markets, especially in North America and Europe, will continue to lead the adoption of these technologies, with Asia-Pacific emerging as a fast-growing market.
- Ongoing advancements in multi-sensor fusion will improve the accuracy and reliability of railway safety and operational systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Radar and LiDAR Technology for Railways Application market?
What factors are driving the growth of the Radar and LiDAR Technology for Railways Application market?
What are the key segments within the Radar and LiDAR Technology for Railways Application market?
What are some challenges faced by the Radar and LiDAR Technology for Railways Application market?
Who are the major players in the Radar and LiDAR Technology for Railways Application market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Radar and LiDAR Technology for Railways Application Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Radar and LiDAR Technology for Railways Application Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,502.25 million → 2032: USD 3,059.87 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Radar and LiDAR Technology for Railways Application Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Radar and LiDAR Technology for Railways Application Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Radar and LiDAR Technology for Railways Application Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Radar and LiDAR Technology for Railways Application Market Drivers
- 3.3 Radar and LiDAR Technology for Railways Application Market Restraints & Challenges
- 3.4 Radar and LiDAR Technology for Railways Application Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Radar and LiDAR Technology for Railways Application Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Radar and LiDAR Technology for Railways Application Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Radar and LiDAR Technology for Railways Application category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Radar and LiDAR Technology for Railways Application Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Radar and LiDAR Technology for Railways Application Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Radar and LiDAR Technology for Railways Application. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Radar and LiDAR Technology for Railways Application Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Radar and LiDAR Technology for Railways Application Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Radar and LiDAR Technology for Railways Application Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Radar and LiDAR Technology for Railways Application (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Radar and LiDAR Technology for Railways Application
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Radar and LiDAR Technology for Railways Application Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Radar and LiDAR Technology for Railways Application Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Radar and LiDAR Technology for Railways Application Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Radar and LiDAR Technology for Railways Application Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Radar and LiDAR Technology for Railways Application Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Radar and LiDAR Technology for Railways Application Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Radar and LiDAR Technology for Railways Application Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Radar and LiDAR Technology for Railways Application Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
