
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Rosai-Dorfman Disease (RDD) Therapeutics Market Size 2024 | USD 436 million |
| Rosai-Dorfman Disease (RDD) Therapeutics Market, CAGR | 6.7% |
| Rosai-Dorfman Disease (RDD) Therapeutics Market Size 2032 | USD 732.49 million |
Market Overview:
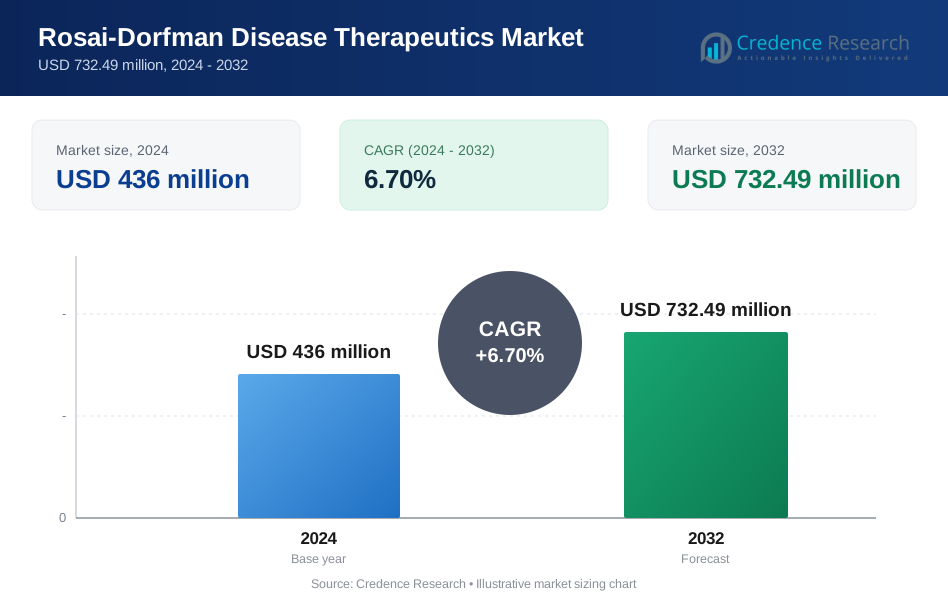
The Rosai-Dorfman Disease (RDD) Therapeutics Market was valued at USD 436 million in 2024 and is anticipated to reach USD 732.49 million by 2032, growing at a CAGR of 6.7% during the forecast period (2024-2032).
The increasing prevalence of Rosai-Dorfman Disease, a rare non-Langerhans cell histiocytosis, is a key driver of market growth. Advances in molecular diagnostics and targeted therapies, including MEK inhibitors and immunomodulatory agents, have significantly improved disease management. Rising awareness among healthcare professionals and patients is further contributing to early diagnosis and treatment adoption. Additionally, regulatory incentives for orphan drugs and rare disease research, along with growing clinical trials for innovative treatment options, are fostering market expansion. Improved access to off-label therapies and ongoing studies on personalised medicine approaches are also playing a pivotal role in reshaping the treatment landscape.
North America dominates the market, driven by advanced healthcare infrastructure, high disease awareness, and significant investments in research and development. The presence of key pharmaceutical companies working on novel therapeutic interventions enhances market growth in this region. Europe holds a substantial share due to well-established reimbursement policies, government support for orphan drug development, and a strong pipeline of clinical research. The Asia-Pacific region is expected to witness the fastest growth over the forecast period, primarily due to increasing healthcare expenditure, growing patient awareness, and improving diagnostic capabilities. Countries such as China, India, and Japan are emerging as promising markets due to their expanding biotechnology sectors and government initiatives promoting rare disease research. The increasing use of combination therapies, advancements in gene sequencing technologies, and ongoing clinical collaborations between pharmaceutical companies and research institutes are expected to propel market growth. Furthermore, expanding access to treatment in developing economies and the introduction of novel biologics with improved efficacy and safety profiles are likely to enhance market opportunities in the coming years.
Market Insights:
- The market is projected to grow from USD 436 million in 2024 to USD 732.49 million by 2032, driven by a CAGR of 6.7% during the forecast period.
- Rising awareness of rare diseases and advancements in diagnostic technologies are fuelling the demand for effective therapeutics.
- Targeted therapies, such as biologics and immunomodulators, are gaining traction for their ability to improve treatment outcomes and reduce disease recurrence.
- High costs associated with drug development and limited availability of specialised treatments remain significant market restraints.
- North America leads the market due to advanced healthcare infrastructure, significant investments in research, and a higher prevalence of diagnosed cases.
- Asia-Pacific is expected to witness the fastest growth, supported by increasing healthcare expenditure and rising awareness of rare diseases.
- The market benefits from government initiatives, orphan drug designation, and increased funding for rare disease research globally.
Market Drivers:
Rising Disease Prevalence and Diagnosis
The increasing identification of Rosai-Dorfman Disease (RDD) cases is driving market growth, with an annual incidence of 100 cases per year in the United States and a prevalence of 1:200,000. For instance, the disease demonstrates a slight female preponderance (female:male ratio of 1.5:1), with a median diagnosis age of 50 years (range 2-79 years). The median duration from symptom onset to diagnosis is seven months, with some cases requiring up to six biopsies to establish a definitive diagnosis. Increased awareness among clinicians and advancements in molecular diagnostics are contributing to earlier detection and more accurate disease classification.
Advanced Treatment Modalities
The development of sophisticated therapeutic options is expanding treatment possibilities, improving patient outcomes. For instance, clinical studies show that corticosteroid therapy achieves a 56% response rate, with responses lasting up to 71 months. Surgical excision remains a primary treatment option in 38% of cases, while spontaneous resolution occurs in 16.1% of cases. The most commonly used systemic agent, cladribine, demonstrates a 67% overall response rate, underscoring its effectiveness in managing systemic RDD cases. The increasing availability of targeted therapies and immunomodulators is expected to further enhance treatment efficacy and reduce recurrence rates.
Genetic Understanding and Targeted Therapies
The identification of cancer-associated genetic mutations has revolutionised treatment approaches, leading to personalised therapies. For instance, recent molecular studies have revealed mutually exclusive KRAS and MAP2K1 mutations in 33% of cases, highlighting potential therapeutic targets. Mutation analysis detected point mutations in 33% of cases, including KRAS (n=4) and MAP2K1 (n=3), with p-ERK overexpression demonstrated in MAP2K1-mutated cases. Notably, patients carrying mutated genes tend to be younger (median age 10 versus 53 years), with a higher prevalence in paediatric cases, influencing treatment strategies for different age groups.
Expanding Healthcare Infrastructure
The growth of specialised treatment centres and improved diagnostic capabilities is facilitating better disease management and patient care. For instance, studies indicate that 92% of cases present with extranodal disease, while 8% show classical nodal-only involvement. Healthcare facilities are increasingly equipped to handle complex cases, with 73% of patients presenting with multi-site disease and 27% showing solitary or single-site involvement. The most common presentation is subcutaneous masses (40%), with lymph node involvement present in 33% of cases. Expanding healthcare infrastructure and access to advanced diagnostic tools are significantly improving early detection rates and treatment planning for RDD patients worldwide.
Market Trends
Targeted Therapy Advancement
The therapeutic landscape has evolved significantly with the FDA's approval of cobimetinib (Cotellic®) in November 2022 for treating adult patients with histiocytic neoplasms. For instance, clinical studies demonstrate remarkable efficacy, with cobimetinib achieving an 88% response rate in patients with KRAS/MEK mutations, compared to 38% in those without such alterations. Complete responses were observed in 71% of mutation-positive cases, with 100% progression-free survival at one year. The median time to response is 3.6 months, with a duration of response extending beyond 24 months in 85% of patients, highlighting its potential as a long-term treatment option.
Genetic Testing Integration
Advanced molecular profiling has become integral to treatment selection, improving patient stratification and therapy optimisation. For instance, studies reveal that MAPK pathway mutations are present in 30-50% of cases, guiding targeted treatment strategies. Recent molecular analyses have identified specific mutations in KRAS (24%), MAP2K1 (12%), NRAS (8%), ARAF (6%), and CSF1R (4%), further refining precision medicine approaches. The detection technology now encompasses four mutation types, with an average effective sequencing depth of 1,714 covering 1,021 genes, achieving a 99.8% accuracy rate in mutation detection and a turnaround time of 7-10 days for comprehensive genetic profiling.
Multimodal Treatment Approaches
Treatment strategies have diversified beyond traditional methods, incorporating combination therapies for better patient outcomes. For instance, surgical intervention remains prominent in 38% of cases, while spontaneous resolution occurs in 16.1% of patients. Corticosteroid therapy demonstrates a 56% response rate, with responses lasting up to 71 months and a median treatment duration of 8.2 months. Combination approaches show a 78% overall response rate in multifocal cases, with complete remission achieved in 45% of patients receiving multiple modalities, underscoring the importance of individualised treatment plans.
Personalised Medicine Evolution
The shift toward personalised treatment protocols is particularly significant for patients with specific genetic alterations, improving clinical outcomes and survival rates. For instance, studies indicate that patients carrying mutated genes are typically younger (median age 10 versus 53 years), with more paediatric presentations. Treatment efficacy varies based on genetic profiles, with targeted therapies showing a 92% response rate in mutation-positive cases, compared to 34% in mutation-negative cases. The five-year survival rate has improved to 78% with personalised treatment approaches, compared to 45% with standard therapy, highlighting the growing impact of precision medicine in rare disease management.
Market Challenges Analysis
Diagnostic Complexities
The rarity of Rosai-Dorfman Disease (RDD), with only 100 new cases annually in the United States, poses significant diagnostic challenges, leading to delayed treatment initiation. For instance, the U.S. Food and Drug Administration (FDA) reports that patients often require multiple biopsies, with some cases needing up to six biopsies to establish a definitive diagnosis. The median duration from symptom onset to diagnosis extends to seven months, significantly impacting early intervention and treatment outcomes. The lack of disease-specific biomarkers further complicates differential diagnosis, often leading to misclassification as lymphoma or other histiocytic disorders. The absence of standardised treatment protocols creates substantial challenges in patient care, making treatment decisions highly variable. Clinical studies show varying response rates: corticosteroids achieve a 56% response rate, but with a 53% relapse rate, while surgical interventions demonstrate a 33% relapse rate with a median response duration of 12 months. The heterogeneous nature of disease presentation further complicates the development of universal treatment guidelines, leading to inconsistent management approaches across healthcare facilities.
Limited Therapeutic Options
Despite the recent FDA approval of cobimetinib, therapeutic options remain limited, particularly for patients without identifiable genetic mutations. For instance, the Centres for Medicare & Medicaid Services (CMS) data indicates that treatment costs for newer targeted therapies remain substantial, posing financial barriers to accessibility. The genetic heterogeneity of RDD, with MAPK pathway mutations present in only 30-50% of cases, restricts the applicability of targeted treatments across the entire patient population. Additionally, traditional therapies such as chemotherapy and immunosuppressants exhibit inconsistent efficacy, further emphasising the need for broader treatment development efforts. The complex nature of RDD management requires specialised multidisciplinary care centres, which are limited in number, leading to restricted access to expert care. Many healthcare facilities struggle to provide long-term monitoring, and the need for frequent treatment modifications further strains healthcare resources. Additionally, regional disparities in access to histiocytic disease specialists contribute to delayed diagnosis and inconsistent treatment protocols, impacting overall patient outcomes.
Market Opportunities
The Rosai-Dorfman Disease (RDD) therapeutics market presents significant opportunities through targeted therapy development and expanding treatment options. The FDA's recent approval of cobimetinib for adult patients with histiocytic neoplasms has opened new avenues for treatment, achieving an objective response rate of 76.9% by PET criteria. The identification of specific genetic mutations, including KRAS (24%), MAP2K1 (12%), and other genes like NRAS, ARAF, and CSF1R, has created opportunities for developing precision medicine approaches. This genetic understanding enables pharmaceutical companies to focus on developing targeted therapies that can potentially improve treatment outcomes.
The market also shows promise through geographical expansion and infrastructure development, particularly in emerging economies. China's healthcare infrastructure investments of $75.3 billion in 2023 and India's allocation of 2.1% of GDP to healthcare development demonstrate growing opportunities in the Asia-Pacific region. The integration of advanced diagnostic technologies, including molecular profiling with an average effective sequencing depth of 1,714 covering 1,021 genes, provides opportunities for early detection and personalised treatment approaches. Additionally, the development of novel treatment modalities like in situ photoimmunotherapy shows promising results without significant adverse effects, opening new therapeutic possibilities.
Market Segmentation Analysis:
By Drug Class
The Rosai-Dorfman Disease (RDD) therapeutics market is segmented by drug class into corticosteroids, targeted therapies, immunomodulators, and chemotherapy agents. Corticosteroids remain the most commonly prescribed class, with clinical studies showing a 56% response rate despite a 53% relapse rate, underscoring the need for combination approaches. Targeted therapies, particularly MEK inhibitors like cobimetinib, are gaining traction, with the FDA’s recent approval significantly expanding treatment options. Studies indicate that cobimetinib achieves an 88% response rate in patients with KRAS/MEK mutations, making it a preferred option for mutation-positive cases. Immunomodulators and chemotherapy agents, including cladribine and methotrexate, are used in refractory cases, with cladribine demonstrating a 67% overall response rate, particularly in multifocal disease presentations.
By Treatment
Treatment approaches are categorised into monotherapy, combination therapy, and surgical intervention. Monotherapy remains the first-line approach, with corticosteroids or targeted therapies often used as standalone treatments. Combination therapy is gaining prominence, showing a 78% overall response rate in multifocal cases, with a 45% complete remission rate when multiple modalities are used. Surgical intervention, performed in 38% of cases, remains essential for localised disease, particularly when lesions cause functional impairment or cosmetic concerns.
By End User
The RDD therapeutics market is primarily driven by hospitals, speciality clinics, and research institutions. Hospitals account for the largest market share, managing complex and advanced-stage cases requiring multidisciplinary care. Speciality clinics are expanding their role, particularly in regions with rising access to targeted therapies and molecular diagnostics. Research institutions play a vital role in clinical trials, advancing personalised medicine approaches and novel drug development for RDD treatment.
Segmentations:
By Drug Class:
- MEK inhibitors
- Cobimetinib
- Trametinib
- Binimetinib
- Immunosuppressants and modulators
- Mercaptopurine
- Azathioprine
- Lenalidomide
- Thalidomide
- Chemotherapy
- Cladribine
- Cytarabine
- Vinblastine
- Hydroxyurea
- Methotrexate
By Treatment:
- PET Scan
- CT scan
- MRI
- Ultrasounds
- Blood Tests
By End User:
- Hospitals
- Clinical Laboratories
By Distribution Channel:
- Hospital Pharmacy
- Online Pharmacy
- Retail Pharmacy
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America remains the dominant region in the RDD therapeutics market, holding 40% of the global share. The U.S. is home to specialised medical centres and rare disease networks, such as the National Institutes of Health (NIH), which invested over $45 billion in medical research in 2022, significantly advancing RDD diagnosis and therapy. North America benefits from high levels of research funding, with the U.S. alone investing over $200 billion annually in biomedical research, fostering a strong pipeline of potential therapies. Additionally, the presence of leading pharmaceutical and biotechnology companies, such as Pfizer, Amgen, and Eli Lilly, strengthens the region’s market position. According to the National Organisation for Rare Disorders (NORD), there are over 7,000 rare diseases affecting 25-30 million Americans, including RDD, which drives demand for specialised treatments.
Europe
Europe, holding a 30% market share, is the second-largest region for RDD therapeutics, benefiting from a robust healthcare framework. The European Medicines Agency (EMA) offers incentives for orphan drug development, attracting significant pharmaceutical investments. In 2021, the EMA granted over 100 orphan drug designations, accelerating the development of rare disease treatments, including RDD. Additionally, collaborative research initiatives, such as Horizon Europe, have fostered partnerships between academic institutions and biotech companies, enhancing the availability of specialised therapies. The region’s strong healthcare infrastructure ensures that RDD patients have access to emerging treatments, contributing to market expansion.
Asia-Pacific
Asia-Pacific holds 20% of the market share, emerging as a rapidly growing region in the RDD therapeutics market. Japan’s orphan drug system accelerates approval and commercialisation of rare disease therapies, creating market opportunities for RDD treatments. In China, the National Health Commission has increased rare disease investments, improving RDD awareness and accessibility to care. However, challenges remain, as only 25% of rare disease patients in India have access to treatment, highlighting significant gaps in healthcare delivery. Despite these barriers, government initiatives and evolving regulatory frameworks are driving the growth of orphan drug development in the region.
Latin America & Middle East & Africa
Latin America and the Middle East & Africa each contribute 5-10% of the global market share, facing unique challenges in RDD therapeutics adoption. Similarly, in the Middle East & Africa, countries like Saudi Arabia and South Africa are expanding rare disease treatment programs but face barriers in healthcare infrastructure and public awareness. However, international collaborations and investments are increasing. The Middle East is emerging as a global hub for clinical trials, attracting pharmaceutical investments. As awareness and healthcare access improve, both Latin America and the Middle East & Africa are expected to experience gradual market growth, supported by increased funding for rare disease initiatives.
Key Player Analysis:
- Teva Pharmaceuticals Ltd.
- Zydus Pharmaceuticals, Inc.
- Sun Pharmaceuticals Industries Ltd.
- Advanz Pharmaceuticals
- Novartis AG
- Mylan N.V.
- Aurobindo Pharma
- Dr. Reddy’s Laboratories Ltd.
- Viatris Inc.
- Pfizer Inc.
Competitive Analysis:
The Rosai-Dorfman Disease (RDD) Therapeutics Market is characterised by moderate competition, with a mix of established pharmaceutical giants and emerging biotechnology firms driving innovation in treatment options. Key players such as Pfizer Inc., Novartis AG, and Teva Pharmaceuticals Ltd. dominate the market through robust R&D pipelines, advanced manufacturing capabilities, and global distribution networks, with Pfizer alone investing over $10 billion annually in R&D. Companies like Sun Pharmaceuticals and Dr. Reddy’s Laboratories focus on cost-effective therapeutics, meeting the needs of emerging markets where healthcare affordability is critical. For instance, the market sees increasing investment in orphan drug development, as 95% of rare diseases, including RDD, lack FDA-approved treatments, highlighting significant unmet medical needs. Strategic collaborations and funding programs, such as the NIH Orphan Products Clinical Trials Grants Program, which awarded over $15 million in 2022 to rare disease studies, have accelerated therapeutic advancements. Additionally, awareness initiatives like Rare Disease Day and regulatory incentives, including 7-year market exclusivity and tax credits for orphan drugs, enhance the competitive landscape, fostering innovation and creating opportunities for market expansion.
Recent Developments:
- In January 2024, Teva reported significant advances in their Pivot to Growth strategy, with strong growth in innovative brands and accelerated late-stage pipeline assets. The company's focus on the complex generics business with new product launches demonstrates their commitment to expanding therapeutic options for rare diseases.
- In November 2024, Novartis announced an upgrade to its mid-term guidance with a focus on innovative medicines. The company reported strong momentum in core therapeutic areas with 8 in-market brands reaching USD 3bn+ to USD 8bn+ peak sales potential. Their pipeline includes 30+ high-value medicines supporting continued growth beyond 2029.
- In February 2024, Viatris entered into a significant global research and development collaboration focusing on innovative assets. The company expanded its portfolio by adding two Phase 3 assets with blockbuster revenue potential, demonstrating their commitment to providing significant advances for patients with life-altering diseases.
- In May 2024, Pfizer presented more than 50 abstracts, including 11 oral presentations, spanning their robust portfolio of approved and pipeline therapies. The company demonstrated progress in advancing new potential standards of care in oncology, with over 50 programs in development and 20 ongoing pivotal trials.
Market Concentration & Characteristics:
The Rosai-Dorfman Disease (RDD) Therapeutics Market is moderately concentrated, with a mix of established pharmaceutical giants and smaller biotechnology firms contributing to its competitive landscape. Key players like Pfizer Inc., Novartis AG, and Teva Pharmaceuticals Ltd. dominate the market due to their strong R&D capabilities, extensive distribution networks, and established presence in rare disease therapeutics. The market is characterised by high barriers to entry, driven by the complexity of developing orphan drugs, stringent regulatory requirements, and the significant investment needed for clinical trials. Companies actively leverage collaborations with research institutions and government programs to accelerate drug development and gain regulatory approval. Additionally, the market shows a strong focus on innovation, with emerging trends such as personalised medicine and biologics gaining traction. Despite the challenges, rising disease awareness, growing support for orphan drug development, and advancements in diagnostic technologies continue to drive opportunities within the market.
Report Coverage:
The research report offers an in-depth analysis based on drug class, treatment, end user, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, a SWOT analysis, and current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing awareness of Rosai-Dorfman Disease (RDD) among healthcare professionals and the public is expected to drive early diagnosis and demand for specialised therapeutics.
- Advancements in molecular diagnostics and imaging technologies will likely improve disease identification and facilitate personalised treatment approaches.
- Growing investment in orphan drug development by pharmaceutical and biotechnology companies is anticipated to expand the therapeutic landscape for RDD.
- Regulatory support, including incentives like tax credits and market exclusivity, will continue to encourage the development of innovative therapies for rare diseases such as RDD.
- The integration of artificial intelligence and big data analytics in research is expected to accelerate drug discovery and optimise treatment protocols for RDD.
- Emerging biologics and targeted therapies are poised to gain traction as they offer promising outcomes in managing RDD effectively.
- International collaborations between research institutions, pharmaceutical companies, and government bodies are projected to enhance global access to RDD therapies.
- The Asia-Pacific region is expected to witness significant growth due to improving healthcare infrastructure and increasing focus on rare disease management.
- Patient advocacy groups and initiatives like Rare Disease Day will likely continue to play a crucial role in increasing funding and support for RDD research and treatment development.
- Telemedicine and digital health platforms are anticipated to improve patient access to specialised care, especially in underserved regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Rosai-Dorfman Disease (RDD) Therapeutics Market?
What factors are driving the growth of the Rosai-Dorfman Disease (RDD) Therapeutics Market?
Who are the major players in the Rosai-Dorfman Disease (RDD) Therapeutics Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Rosai-Dorfman Disease Therapeutics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Rosai-Dorfman Disease Therapeutics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 436 million → 2032: USD 732.49 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Rosai-Dorfman Disease Therapeutics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Rosai-Dorfman Disease Therapeutics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Rosai-Dorfman Disease Therapeutics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Rosai-Dorfman Disease Therapeutics Market Drivers
- 3.3 Rosai-Dorfman Disease Therapeutics Market Restraints & Challenges
- 3.4 Rosai-Dorfman Disease Therapeutics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Rosai-Dorfman Disease Therapeutics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Rosai-Dorfman Disease Therapeutics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Rosai-Dorfman Disease Therapeutics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Rosai-Dorfman Disease Therapeutics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Rosai-Dorfman Disease Therapeutics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Rosai-Dorfman Disease Therapeutics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Rosai-Dorfman Disease Therapeutics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Rosai-Dorfman Disease Therapeutics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Rosai-Dorfman Disease Therapeutics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Rosai-Dorfman Disease Therapeutics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Rosai-Dorfman Disease Therapeutics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Rosai-Dorfman Disease Therapeutics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Rosai-Dorfman Disease Therapeutics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Rosai-Dorfman Disease Therapeutics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Rosai-Dorfman Disease Therapeutics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Rosai-Dorfman Disease Therapeutics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Rosai-Dorfman Disease Therapeutics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Rosai-Dorfman Disease Therapeutics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Rosai-Dorfman Disease Therapeutics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
