
Market Overview
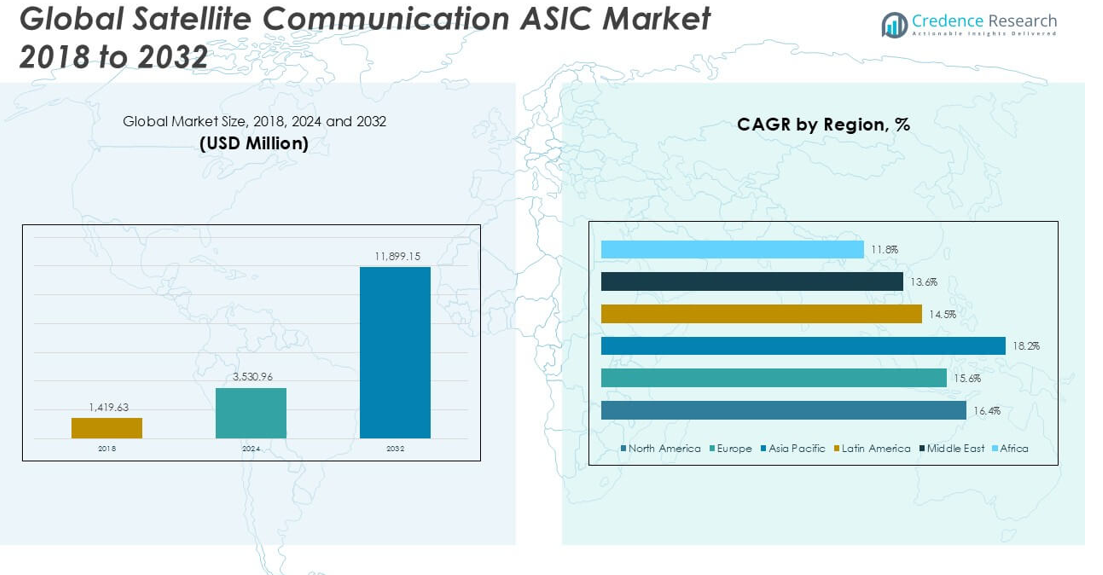
The Satellite Communication ASIC market size was valued at USD 1,419.63 million in 2018, increased to USD 3,530.96 million in 2024, and is anticipated to reach USD 11,899.15 million by 2032, at a CAGR of 16.40% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Satellite Communication ASIC Market Size 2024 | USD 3,530.96 million |
| Satellite Communication ASIC Market, CAGR | 16.40% |
| Satellite Communication ASIC Market, Size 2032 | USD 11,899.15 million |
The Satellite Communication ASIC market is led by prominent players such as Thales Group, L3Harris Technologies, Viasat, Cobham, Honeywell International, General Dynamics, Gilat Satellite Networks, Hughes Network Systems, ST Engineering iDirect, and Comtech Telecommunications. These companies dominate through advanced technological capabilities, strong global presence, and a focus on innovation in satellite hardware and communication systems. Strategic partnerships, R&D investments, and product differentiation remain key competitive strategies. North America emerges as the leading region, holding a 42.7% share of the global market in 2024, driven by strong defense spending, growing satellite launches, and the presence of top aerospace and semiconductor firms.
Market Insights
- The Satellite Communication ASIC market was valued at USD 1,419.63 million in 2018, reached USD 3,530.96 million in 2024, and is projected to hit USD 11,899.15 million by 2032, growing at a CAGR of 16.40% during the forecast period.
- Growth is primarily driven by rising demand for high-speed internet in remote regions, increasing satellite deployments, and the integration of 5G and IoT technologies into satellite networks.
- A key trend includes the adoption of software-defined satellites and low-Earth orbit constellations that require efficient and programmable ASICs for enhanced performance.
- Market competition is led by Thales Group, L3Harris Technologies, and Viasat, while high ASIC design costs and limited skilled workforce remain key restraints to widespread adoption.
- North America held the largest share in 2024 at 42.7%, while the Ku-band and Equipment segments dominated their respective categories due to broad commercial and defense applications.
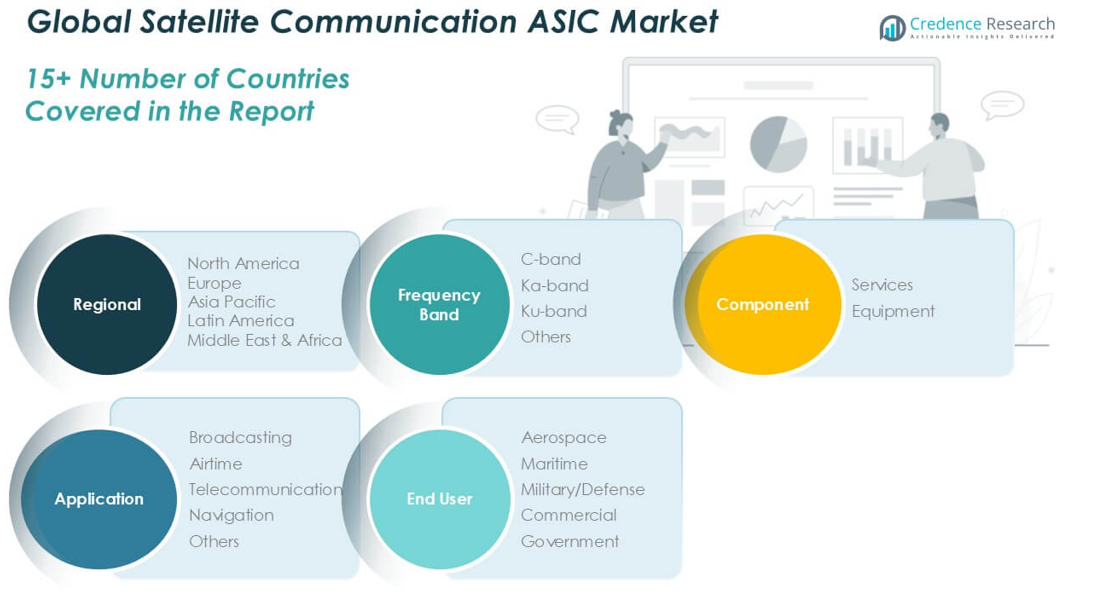
Market Segmentation Analysis:
By Frequency Band
The Satellite Communication ASIC market is segmented into C-band, Ka-band, Ku-band, and Others. Among these, the Ku-band segment holds the dominant market share, attributed to its widespread use in broadcasting and broadband communication services. Its balance between coverage area and bandwidth efficiency makes it suitable for commercial and defense applications. Increasing demand for high-throughput satellite services and growing investments in satellite internet are fueling the adoption of Ku-band. Meanwhile, the Ka-band is gaining traction due to its high data rate capabilities, making it ideal for high-capacity satellite communication networks.
- For instance, Viasat’s ViaSat‑2 satellite-operating in Ka‑band and Ku‑band achieves a total payload capacity of 260 Gbps and delivers user speeds up to 100 Mbps.
By Component
The market is bifurcated into Services and Equipment. The Equipment segment leads the market, accounting for the largest revenue share due to the growing deployment of advanced satellite transceivers, modulators, and signal processors. The rising need for efficient and compact ASIC-based communication systems in satellite payloads has accelerated equipment demand. Increased satellite launches for broadband, navigation, and surveillance purposes, especially by commercial players, are further supporting this segment’s growth. However, the Services segment is expected to witness notable expansion as satellite communication networks scale globally, demanding long-term service integration and maintenance.
- For instance, Cobham Advanced Electronic Solutions integrates radiation-hardened ASICs into its payload equipment capable of supporting multi‑Gbps data processing for satellite systems, such as processors with up to 64 cores tailored for in-orbit communication resilience.
By Application
The application segment includes Broadcasting, Airtime, Telecommunications, Navigation, and Others. Telecommunications is the dominant sub-segment, driven by the surging demand for satellite-based internet and voice services across underserved and remote regions. Governments and telecom operators are leveraging satellite ASICs to expand connectivity, especially for 5G backhaul and rural broadband. Broadcasting follows closely, fueled by the continued need for satellite TV and radio services. Navigation and airtime applications are also growing steadily due to their use in aviation, maritime, and defense, where real-time, secure communication is critical for operational success.
Market Overview
Rising Demand for High-Speed Connectivity in Remote Regions
The growing global need for high-speed internet access in remote and underserved regions is a major growth driver for the Satellite Communication ASIC market. As traditional terrestrial networks struggle with coverage limitations in rural and offshore areas, satellite communication provides a reliable alternative. ASIC-based solutions enhance data processing speed and power efficiency in satellites, enabling seamless connectivity. Governments and private players are increasingly investing in satellite broadband initiatives, further accelerating the demand for robust and specialized ASICs tailored to support continuous, high-speed, and low-latency communications.
- For instance, Hughes Network Systems deployed JUPITER 3-a Ka‑band geostationary satellite delivering 500 Gbps total capacity with user speeds up to 100 Mbps across the Americas.
Expanding Satellite Constellations for Commercial and Defense Use
The rapid deployment of Low Earth Orbit (LEO) satellite constellations by commercial players and government agencies is significantly boosting the market. These constellations require compact, power-efficient, and high-performance ASICs to handle large volumes of data with minimal latency. In the defense sector, secure and real-time communication needs have led to greater adoption of ASIC-powered satellite systems. The miniaturization of hardware and enhanced computational capabilities provided by ASICs make them critical to supporting next-generation satellite operations, particularly in mission-critical and high-throughput communication environments.
- For instance, Lockheed Martin integrated ASIC‑based chipsets into SDA Tranche 0 Transport Layer satellites, enabling encrypted cross‑link data at 1.2 Gbps per link across more than 10 satellites (program specifications).
Integration of 5G and IoT with Satellite Networks
The convergence of 5G and Internet of Things (IoT) technologies with satellite networks presents a substantial growth opportunity. ASICs play a central role in enabling real-time data transmission, low-power operation, and high-speed processing necessary for 5G backhaul and IoT sensor networks. Satellite communication is increasingly integrated into global IoT ecosystems to provide seamless connectivity across geographically dispersed assets, such as maritime fleets, oil rigs, and defense systems. This integration is fostering demand for highly customized and scalable ASICs capable of supporting diverse communication protocols and large device volumes.
Key Trends & Opportunities
Proliferation of Software-Defined Satellites (SDS)
A notable trend in the Satellite Communication ASIC market is the emergence of software-defined satellites, which offer flexible payload configurations and dynamic bandwidth allocation. These satellites require programmable and highly efficient ASICs that can adapt to changing signal conditions and communication demands. The increasing preference for SDS platforms, especially in commercial applications, is creating new opportunities for ASIC designers to develop reconfigurable architectures, enhancing satellite mission versatility and lifespan while lowering operational costs.
- For instance, Thales Alenia Space has delivered over 23,200 travelling wave tubes across its Space INSPIRE product line, and its ASTRA 1Q satellite incorporates dual Ku-/Ka-band amplifiers, enabling in-orbit reconfiguration across 32 frequency channels-a clear demonstration of ASIC-driven flexibility and performance in modern SDS platforms.
Growth in Private Sector Participation and Satellite-as-a-Service Models
The entry of private space technology firms and the rise of satellite-as-a-service (SaaS) models are expanding market opportunities. As companies like SpaceX and OneWeb drive satellite launches and services, demand grows for cost-effective and high-performance ASICs to optimize onboard data processing and communication. This democratization of space technology enables small and mid-sized enterprises to access satellite capabilities, thereby increasing the scale and diversity of ASIC requirements across verticals such as agriculture, logistics, and disaster management.
- For instance, OneWeb’s LEO network uses ASIC-equipped modems delivering 200 Mbps per user terminal and supports over 600 MHz of aggregated bandwidth for enterprise and government clients
Key Challenges
Complexity and High Cost of ASIC Design and Fabrication
One of the key challenges in this market is the high cost and complexity involved in designing and fabricating satellite-grade ASICs. These chips must withstand extreme space environments, offer long operational life, and comply with rigorous regulatory standards, significantly increasing development time and expenses. Moreover, the customization required for each satellite mission limits economies of scale, making ASIC deployment a costly proposition for smaller operators, thereby constraining broader market adoption.
Limited Availability of Skilled Workforce and Technical Expertise
The design and implementation of advanced ASICs for satellite communication require specialized skills in microelectronics, RF design, and system integration. However, the industry faces a talent gap due to the niche nature of this expertise. The shortage of experienced professionals can slow down innovation, product development, and time-to-market for new solutions. Training and retaining skilled engineers is essential to meet the increasing demand for ASIC-enabled satellite communication systems across varied applications.
Stringent Regulatory and Licensing Constraints
Regulatory hurdles related to satellite spectrum allocation, cross-border data transmission, and launch approvals pose ongoing challenges. Compliance with international standards, such as ITU regulations, adds complexity to satellite ASIC development and deployment. Delays in securing necessary licenses and approvals can postpone satellite projects, affecting revenue timelines and increasing costs. These constraints can deter smaller players and startups from entering the market, limiting innovation and competitive diversity.
Regional Analysis
North America
North America held the largest share in the Satellite Communication ASIC market, accounting for approximately 42.7% of the global revenue in 2024, with a market value of USD 1,506.64 million, rising from USD 612.19 million in 2018. By 2032, the region is expected to reach USD 5,091.59 million, growing at a CAGR of 16.4%. The region’s dominance is driven by strong government and private investments in satellite constellations, advanced defense communication systems, and high demand for satellite-based internet services. The presence of key aerospace and semiconductor players also enhances technological innovation and deployment speed.
Europe
Europe accounted for approximately 28.6% of the global Satellite Communication ASIC market in 2024, reaching USD 1,010.25 million, up from USD 420.69 million in 2018. The market is projected to attain USD 3,214.11 million by 2032, registering a CAGR of 15.6%. The region benefits from its well-established aerospace infrastructure, supportive policy framework for space programs, and growing demand for secure communication systems across defense and maritime sectors. Additionally, the European Union’s initiatives to develop sovereign satellite capabilities further contribute to consistent market expansion across multiple end-use industries.
Asia Pacific
Asia Pacific is the fastest-growing region in the Satellite Communication ASIC market, with a robust CAGR of 18.2% during the forecast period. The market expanded from USD 273.21 million in 2018 to USD 736.50 million in 2024, accounting for 20.9% of global market share that year. It is projected to grow significantly to USD 2,810.88 million by 2032. This growth is driven by rising satellite deployments across China, India, and Japan, increasing government focus on space technology, and expanding telecom infrastructure. The region's rapid digitization and investments in IoT and 5G applications are accelerating ASIC demand.
Latin America
Latin America contributed approximately 4.3% of the global Satellite Communication ASIC market in 2024, with a market value of USD 151.35 million, rising from USD 61.68 million in 2018. The region is projected to reach USD 446.25 million by 2032, growing at a CAGR of 14.5%. The market is driven by increasing use of satellite communication in remote education, disaster management, and agriculture. Government initiatives and collaborations with global satellite operators are enhancing connectivity in rural areas. However, infrastructure challenges and limited local manufacturing capabilities may moderate the growth pace compared to other regions.
Middle East
The Middle East accounted for 2.3% of the Satellite Communication ASIC market in 2024, with its size growing from USD 35.82 million in 2018 to USD 80.59 million. It is expected to reach USD 223.98 million by 2032, registering a CAGR of 13.6%. The region’s growth is primarily supported by the adoption of satellite technology in oil & gas, defense, and government applications. Increasing geopolitical tensions and security needs are driving demand for advanced communication systems. Furthermore, national space programs in the UAE and Saudi Arabia are encouraging domestic satellite production and supporting ASIC deployment.
Africa
Africa held the smallest share in the Satellite Communication ASIC market, contributing around 1.3% in 2024, with a market value of USD 45.62 million, up from USD 16.04 million in 2018. It is projected to reach USD 112.34 million by 2032, growing at a CAGR of 11.8%. While the region faces infrastructure and investment constraints, growing demand for connectivity in remote and underserved areas is gradually fostering satellite adoption. International partnerships, particularly in education, agriculture, and emergency response, are aiding the expansion of satellite communication services, which in turn is creating a niche demand for ASIC solutions.
Market Segmentations:
By Frequency Band
- C-band
- Ka-band
- Ku-band
- Others
By Component
- Services
- Equipment
By Application
- Broadcasting
- Airtime
- Telecommunications
- Navigation
- Others
By End User
- Aerospace
- Maritime
- Military/Defense
- Commercial
- Government
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Satellite Communication ASIC market is characterized by the presence of established defense contractors, advanced semiconductor firms, and specialized satellite communication providers. Leading companies such as Thales Group, L3Harris Technologies, Viasat, and Honeywell International dominate through strong R&D capabilities, diverse product portfolios, and strategic collaborations. These firms are focused on enhancing ASIC performance to support evolving satellite technologies, including high-throughput satellites and low-Earth orbit constellations. Emerging players and regional specialists are also gaining traction by offering customized and energy-efficient ASIC solutions for specific applications in aerospace, defense, and commercial communications. Mergers, acquisitions, and joint ventures remain key strategies to expand technological capabilities and market reach. Additionally, the integration of AI and 5G into satellite systems is prompting companies to invest in next-generation ASIC development. With rising demand for satellite-based connectivity, competition is intensifying, leading to accelerated innovation and greater emphasis on cost-effective, scalable, and mission-specific ASIC solutions.
Key Player Analysis
- Thales Group
- L3Harris Technologies
- Viasat
- Cobham
- Honeywell International
- General Dynamics
- Gilat Satellite Networks
- Hughes Network Systems
- ST Engineering iDirect
- Comtech Telecommunications
Recent Developments
- In July 2025, Honeywell’s Aspire 350 hybrid satcom system, newly selected by Dassault Aviation, features advancements in integrated ASICs to deliver seamless, high-speed satellite connectivity for aviation, supporting both cockpit and cabin voice/data via the Iridium Certus network.
- In June 2025, Thales Alenia Space, a joint venture between Thales and Leonardo, began developing the SOLiS high-throughput laser communications demonstrator. This project, part of the France 2030 program, focuses on optical payloads and utilizes advanced ASIC and system-on-chip technology to achieve ultra-secure, high-speed (up to 1 Tbps) data transfer between ground terminals via geostationary satellites.
- In May 2025, L3Harris was awarded a U.S. government contract to develop a next-generation security processor ASIC for secure communication devices globally. These advancements aim to improve secure satellite and communication hardware for defense systems against emerging cyber threats.
- In April 2025, Viasat enhanced its multi-orbit service roadmap by integrating LEO constellations with advanced satellite ASICs and IP cores. This development improves high-throughput, low-latency communication, including near-1 Tbps optical applications, and enhances resilience for defense and mobility users. The improvements focus on ASIC modem and IP core technology.
- In March 2025, Cobham Satcom announced upgraded TACTICAL TRACKER antenna systems at Satellite Show 2025, which include advanced ASIC-enabled control and signal processing modules for WGS (Wideband Global SATCOM) certification. These enhancements support higher data rates and adaptive communications for military and government users
Market Concentration & Characteristics
The Satellite Communication ASIC market exhibits a moderately concentrated structure, dominated by a few multinational players with strong technological capabilities and global reach. These companies hold significant market share due to their ability to deliver advanced, mission-specific ASIC solutions for space applications. It features high entry barriers stemming from complex design requirements, rigorous space-grade testing, and substantial capital investment. Leading firms maintain their positions through continuous innovation, strategic partnerships, and government contracts. The market demonstrates strong demand across defense, aerospace, and commercial sectors, where reliability, power efficiency, and performance are critical. It benefits from increasing investments in satellite constellations, broadband connectivity, and 5G integration. While new entrants find it difficult to scale due to regulatory compliance and IP constraints, niche players gain footholds by offering specialized or lower-cost ASICs. The competitive landscape reflects a balance between established defense contractors and emerging semiconductor innovators.
Report Coverage
The research report offers an in-depth analysis based on Frequency Band, Component, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience strong growth due to rising demand for satellite-based broadband and communication services.
- Integration of 5G networks with satellite infrastructure will drive the adoption of advanced ASIC solutions.
- Low Earth Orbit (LEO) satellite deployments will create significant demand for compact and power-efficient ASICs.
- Defense and military sectors will continue to prioritize ASIC-based satellite systems for secure and real-time communication.
- Increasing investments in national space programs will support long-term market expansion across regions.
- Software-defined satellite systems will require programmable ASICs with enhanced flexibility and performance.
- Private space companies will play a larger role in market dynamics through commercial satellite services.
- Demand for low-latency communication in maritime, aviation, and remote areas will accelerate ASIC innovation.
- Strategic partnerships between aerospace firms and chip manufacturers will strengthen supply chains and product development.
- Regulatory support and global focus on connectivity will create new opportunities for ASIC vendors worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Satellite Broadband and Connectivity Initiatives
Governments and private companies are investing heavily in satellite broadband to provide high-speed internet access in remote and underserved regions, driving demand for advanced ASICs that enable efficient, high-throughput satellite communication.
Proliferation of Low Earth Orbit (LEO) Satellite Constellations
The rapid deployment of LEO constellations for commercial and defense applications requires compact, power-efficient, and high-performance ASICs to manage large data volumes and low-latency communications, significantly boosting market growth.
Integration of 5G and IoT with Satellite Networks
The convergence of 5G and IoT technologies with satellite infrastructure necessitates specialized ASICs for real-time data transmission, low-power operation, and support for diverse communication protocols, expanding the market's scope and application base.
Adoption of Software-Defined Satellites (SDS)
The shift toward software-defined satellites, which require programmable and flexible ASICs for dynamic bandwidth allocation and in-orbit reconfiguration, is creating new opportunities for ASIC innovation and deployment.
Rising Defense and Security Requirements
Growing defense spending and the need for secure, resilient, and real-time satellite communications in military and government sectors are driving the adoption of advanced ASIC-based solutions tailored for mission-critical applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Satellite Communication ASIC Market?
What is the projected growth rate of the Satellite Communication ASIC Market?
What factors are driving the growth of the Satellite Communication ASIC Market?
What are the key segments within the Satellite Communication ASIC Market?
Who are the major players in the Satellite Communication ASIC Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Aerospace
- 1.2.2 Maritime
- 1.2.3 Military/Defense
- 1.2.4 Commercial
- 1.2.5 Government
- 1.3 By Component
- 1.3.1 Services
- 1.3.2 Equipment
- 1.4 By Application
- 1.4.1 Broadcasting
- 1.4.2 Airtime
- 1.4.3 Telecommunications
- 1.4.4 Navigation
- 1.4.5 Others
- 1.5 By Frequency Band
- 1.5.1 C-band
- 1.5.2 Ka-band
- 1.5.3 Ku-band
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,530.96 million → 2032: USD 11,899.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Satellite Communication ASIC Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Satellite Communication ASIC Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Satellite Communication ASIC Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Satellite Communication ASIC Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Satellite Communication ASIC Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Satellite Communication ASIC Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Satellite Communication ASIC Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Satellite Communication ASIC Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,530.96 million → 2032: USD 11,899.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Satellite Communication ASIC Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Aerospace
- 12.3.7.2 Maritime
- 12.3.7.3 Military/Defense
- 12.3.7.4 Commercial
- 12.3.7.5 Government
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Services
- 12.4.7.2 Equipment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Broadcasting
- 12.5.7.2 Airtime
- 12.5.7.3 Telecommunications
- 12.5.7.4 Navigation
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Frequency Band - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 C-band
- 12.6.7.2 Ka-band
- 12.6.7.3 Ku-band
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Satellite Communication ASIC End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Satellite Communication ASIC Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Satellite Communication ASIC Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Satellite Communication ASIC Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thales Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 L3Harris Technologies
- 18.4 Viasat
- 18.5 Cobham
- 18.6 Honeywell International
- 18.7 General Dynamics
- 18.8 Gilat Satellite Networks
- 18.9 Hughes Network Systems
- 18.10 ST Engineering iDirect
- 18.11 Comtech Telecommunications
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

