
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Silent Scan Technology Market Size 2024 | USD 719 Million |
| Silent Scan Technology Market ,CAGR | 2.4% |
| Silent Scan Technology Market Size 2032 | USD 869.2 Million |
Market Overview:
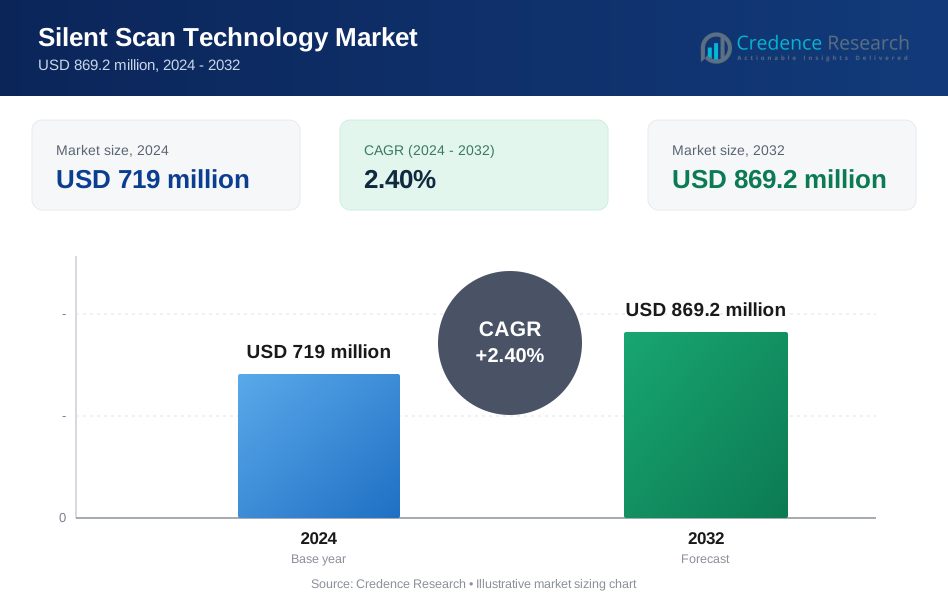
Silent Scan Technology Market size was valued at USD 719 million in 2024 and is anticipated to reach USD 869.2 million by 2032, at a CAGR of 2.4% during the forecast period (2024-2032).
Key drivers of the Silent Scan Technology Market include growing technological advancements in MRI equipment and increasing emphasis on patient-centric care. Traditional MRI machines produce noise levels of up to 120 decibels, often causing discomfort and anxiety in patients. Silent scan technology addresses this challenge by substantially reducing acoustic noise during imaging, without compromising image quality. This has led to increased preference for silent MRI systems across hospitals, diagnostic centers, and outpatient clinics. Furthermore, rising healthcare expenditure, favorable reimbursement policies in developed markets, and increasing investments in healthcare infrastructure are supporting the adoption of advanced imaging technologies. Partnerships between imaging equipment manufacturers and software developers are also contributing to continuous innovation and product enhancements. The demand for enhanced diagnostic accuracy and reduced scan retakes is encouraging wider acceptance of silent scan-enabled systems. As healthcare systems move toward value-based care models, silent scan solutions offer measurable benefits in terms of patient experience and throughput efficiency.
Regionally, North America dominates the Silent Scan Technology Market, supported by a well-established healthcare infrastructure, high awareness levels, and early adoption of advanced imaging technologies. Europe holds the second-largest market share, driven by increasing demand for non-invasive diagnostics and supportive government policies. The Asia Pacific region is expected to witness the fastest growth during the forecast period, fueled by a growing patient population, rising healthcare investments, and expanding access to modern diagnostic facilities across countries like China, India, and Japan. Increasing collaborations between global OEMs and local healthcare providers are aiding market penetration in emerging markets. Government initiatives to enhance diagnostic imaging capabilities in rural and underserved areas are boosting regional uptake.
Market Insights:
- The Silent Scan Technology Market was valued at USD 719 million in 2024 and is anticipated to reach USD 869.2 million by 2032, growing at a CAGR of 2.4% during the forecast period.
- Silent scan technology significantly reduces MRI system noise, enhancing patient comfort, particularly for pediatric, geriatric, and claustrophobic patients.
- Technological advancements, such as noise-canceling algorithms and AI integration, improve image quality and operational efficiency in silent MRI systems.
- Growing healthcare expenditure and favorable government support enable the adoption of advanced diagnostic technologies, including silent scan systems.
- Strong collaborations between imaging manufacturers and software developers drive continuous innovation and product enhancements in silent scan technology.
- High installation and maintenance costs remain a challenge, limiting adoption in resource-constrained settings, especially in low- and middle-income countries.
- North America leads the market due to a well-developed healthcare infrastructure, high diagnostic imaging volumes, and early adoption of advanced technologies.
Market Drivers:
Rising Demand for Patient Comfort in Diagnostic Imaging
The Silent Scan Technology Market is expanding due to growing awareness about patient comfort in medical imaging procedures. Traditional MRI systems generate high noise levels, often reaching 120 decibels, which can lead to patient anxiety and non-cooperation during scans. Silent scan technology significantly reduces acoustic noise, improving the patient experience during MRI exams. Healthcare providers increasingly prioritize patient-centric care, making quiet imaging systems more desirable. Pediatric, geriatric, and claustrophobic patients especially benefit from silent scan features, improving scan success rates. This growing focus on comfort and compliance is encouraging hospitals and diagnostic centers to adopt silent MRI systems.
Technological Advancements in MRI Systems Driving Innovation
Rapid advancements in MRI hardware and software are transforming the Silent Scan Technology Market. Innovations in gradient coil design, noise-canceling algorithms, and optimized pulse sequences are enabling quieter scans without compromising image quality. Leading manufacturers continue to invest in R&D to develop systems that integrate silent scan features with high-resolution imaging. The integration of artificial intelligence and machine learning further enhances image processing and operational efficiency. Hospitals are replacing older systems with next-generation MRI units that incorporate silent scanning. It supports the increasing demand for improved diagnostic accuracy and operational performance.
- For instance, Spectrum Health in Grand Rapids, Michigan, became the first facility globally to implement GE’s Silent Scan, achieving a reduction in MRI scan noise from over 110 dBA to 76 dBA during routine head examinations.
Rising Healthcare Expenditure and Government Support
Governments and private healthcare providers are investing heavily in modern diagnostic infrastructure, creating strong growth prospects for the Silent Scan Technology Market. Expanding healthcare budgets and favorable reimbursement policies are enabling institutions to invest in advanced imaging technologies. Several developed countries have introduced funding schemes that encourage the adoption of patient-friendly diagnostic tools. Health ministries in emerging economies are also allocating resources to upgrade hospital facilities with noise-reduction imaging solutions. These developments increase market penetration across both urban and rural healthcare centers. Growing public awareness about advanced diagnostic technologies further reinforces demand.
Strategic Collaborations and Product Development Initiatives
The Silent Scan Technology Market benefits from strong collaboration between medical imaging companies and software developers. These partnerships lead to continuous innovation, enhancing both noise-reduction capabilities and image clarity. Major industry players are launching silent scan-enabled MRI machines to meet growing clinical requirements. Customization options and user-friendly interfaces are also becoming standard features in new models. Product differentiation and branding efforts around patient comfort are helping companies gain a competitive edge. It is fueling steady adoption across diverse healthcare environments, from specialized clinics to large hospitals.
- For instance, GE Healthcare’s Silent Scan technology is now available on the Discovery MR750w and Optima MR450w systems, achieving noise levels as low as 77 dB during scans, a substantial reduction from standard MRI noise well over 100 dB.
Market Trends:
Integration of Artificial Intelligence to Enhance Imaging Accuracy and Workflow
A key trend shaping the Silent Scan Technology Market is the integration of artificial intelligence (AI) in MRI systems. AI-powered algorithms support real-time noise reduction, accelerate image reconstruction, and improve diagnostic accuracy. Manufacturers are embedding machine learning tools into MRI platforms to optimize silent scan protocols and minimize manual intervention. This approach helps radiologists obtain high-quality images faster and with greater consistency. It is also improving workflow efficiency by reducing scan times and automating image post-processing. AI integration aligns with hospitals’ need to manage high patient volumes while maintaining clinical precision.
- For instance, with Philips Smart Speed on the Blue Seal scanner, exam times are reduced to under 60 minutes per slot, enabling 2 additional patients to be scanned daily.
Rising Adoption in Pediatric and Geriatric Imaging Applications
Healthcare providers are increasingly using silent scan systems for pediatric and geriatric imaging, recognizing the need for patient-friendly diagnostics. The Silent Scan Technology Market is seeing higher adoption in these segments due to their sensitivity to noise and movement during scans. It supports greater patient cooperation, which reduces the need for sedation and repeat imaging. Hospitals and diagnostic centers are prioritizing silent MRI installations in departments focused on children and older adults. This trend is also reflected in growing demand from rehabilitation centers and long-term care facilities. Rising focus on non-invasive, low-stress imaging is reinforcing silent scan technology as a preferred solution.
- For instance, GE Healthcare’s Silent Scan reduces MRI noise to 70 dB, compared to over 110 dB in traditional MRI systems.
Market Challenges Analysis:
High Installation and Maintenance Costs Limit Adoption in Resource-Constrained Settings
One of the key challenges in the Silent Scan Technology Market is the high cost of installation and maintenance. Silent MRI systems require specialized hardware and software, which significantly increases upfront capital expenditure. Smaller hospitals and diagnostic centers, especially in low- and middle-income countries, often lack the financial capacity to invest in such advanced equipment. It limits the technology’s accessibility beyond premium healthcare institutions. Ongoing maintenance and training costs further strain budgets and slow down widespread deployment. Limited reimbursement in some regions compounds the financial barrier.
Technical Complexity and Limited Skilled Workforce Impact Operational Efficiency
The Silent Scan Technology Market faces operational challenges due to the technical complexity of silent MRI systems. Radiologists and technicians must acquire specialized training to use and interpret images from these systems effectively. It creates a learning curve that may delay integration into existing clinical workflows. Healthcare facilities often struggle to recruit or retain professionals with the required skill set. Technical support availability is also inconsistent across regions, affecting service quality. These issues can lead to underutilization of installed systems and reduced return on investment.
Market Opportunities:
Growing Demand for Non-Invasive Imaging Across Emerging Markets
The Silent Scan Technology Market holds strong growth potential across emerging economies where healthcare infrastructure is rapidly evolving. Governments in countries like India, Brazil, and Indonesia are expanding diagnostic capabilities to meet rising patient needs. It creates opportunities for silent scan systems that offer comfort and efficiency without compromising diagnostic quality. Increasing urbanization and higher health awareness drive patient expectations for advanced imaging solutions. Public-private partnerships and international funding programs are supporting the procurement of modern medical equipment. These dynamics present favorable conditions for market expansion across underserved regions.
Expansion of Outpatient Imaging Centers and Specialized Clinics
The rising number of outpatient imaging centers and specialized diagnostic clinics is creating new avenues for the Silent Scan Technology Market. These facilities seek compact, efficient MRI systems that reduce noise and enhance patient throughput. It aligns well with the operational needs of decentralized healthcare settings focused on convenience and patient experience. Vendors offering scalable and cost-efficient silent scan models can address this demand effectively. Demand is also rising among orthopedic, neurology, and pediatric clinics where patient comfort and diagnostic speed are critical. The outpatient trend supports wider adoption of silent scan solutions in both urban and suburban locations.
Market Segmentation Analysis:
By Strength
The Silent Scan Technology Market is segmented into Low Strength (≤1.5T), Medium Strength (1.5T–3T), and High Strength (>3T). Medium strength systems dominate the market due to their optimal balance between image quality and cost-effectiveness. These systems are widely installed across hospitals and diagnostic centers for routine imaging needs. High strength systems are gaining traction in research institutions and advanced neurological centers that require superior image clarity. Low strength systems are used in smaller clinics and resource-limited settings where cost and basic functionality are key considerations. It is enabling broader market accessibility across diverse clinical environments.
- For instance, the GE SIGNA™ Victor 1.5T MRI scanner incorporates AIR™ Coils and AIR™ Recon DL technology, enabling high patient throughput and 360-degree patient comfort in over 1,000 installations worldwide.
By Application
The Silent Scan Technology Market covers Neurology, Oncology, Cardiology, Musculoskeletal, and Others. Neurology holds the largest share due to the high demand for accurate brain imaging with minimal patient movement. Silent scan technology plays a critical role in detecting conditions like epilepsy, multiple sclerosis, and brain tumors. Oncology and cardiology segments are also expanding rapidly, with silent MRI systems reducing patient anxiety during lengthy scans. Musculoskeletal imaging benefits from clearer visualization of soft tissues, particularly in sports medicine and orthopedic diagnostics. It supports more precise diagnosis across a broad range of clinical specialties.
- For instance, the Philips Fast-SENC MRI sequence combined with MyoStrain analysis enables early detection of heart dysfunction across 48 heart segments in just 10 minutes, providing clinicians with actionable data for individualized heart failure management.
By End-User
The market includes Hospitals, Diagnostic Imaging Centers, and Ambulatory Surgical Centers. Hospitals lead due to their large-scale infrastructure and higher investment capacity. Diagnostic imaging centers follow closely, driven by increasing demand for outpatient services. Ambulatory centers are emerging as a growth segment, offering silent scan capabilities in decentralized care settings. It reflects a shift toward patient-friendly and accessible diagnostic solutions across healthcare tiers.
Segmentations:
By Strength
- Low Strength (≤1.5T)
- Medium Strength (1.5T–3T)
- High Strength (>3T)
By Application
- Neurology
- Oncology
- Cardiology
- Musculoskeletal
- Others
By End-User
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads with Advanced Infrastructure and Early Technology Adoption North America holds 37% of the global Silent Scan Technology Market revenue in 2024, making it the leading regional segment. The region’s dominance is driven by a well-developed healthcare ecosystem, high diagnostic imaging volumes, and early adoption of advanced technologies. It benefits from widespread awareness of patient comfort and strong institutional focus on quality care improvements. The presence of major MRI system manufacturers and continuous innovation accelerates market penetration across hospitals and diagnostic centers. Favorable reimbursement policies and significant investment in healthcare infrastructure support sustained growth. The United States contributes the largest share within the region due to advanced facilities and higher per capita spending on medical technology.
Europe Emphasizes Non-Invasive Diagnostics and Healthcare Efficiency Europe accounts for 29% of the global Silent Scan Technology Market revenue in 2024, positioning it as the second-largest region. Strong demand for non-invasive diagnostic solutions and increasing adoption of silent MRI systems drive growth across public and private healthcare sectors. It aligns with EU healthcare modernization efforts aimed at improving patient experience and reducing diagnostic delays. Countries such as Germany, France, and the United Kingdom lead adoption through significant investment in advanced imaging tools. Supportive policies for equipment procurement and active involvement of regional research institutions contribute to steady market expansion. Collaborative innovation between healthcare providers and medical technology companies continues to refine system performance.
Asia Pacific Emerges as the Fastest-Growing Market with Expanding Healthcare Access Asia Pacific holds 22% of the global Silent Scan Technology Market revenue in 2024 and is projected to experience the fastest growth rate through 2032. Rising healthcare spending, increasing awareness of patient-friendly diagnostics, and rapid infrastructure development support regional expansion. It shows strong momentum in countries like China, India, and Japan, where hospitals are scaling up diagnostic capabilities. Government-led programs to improve imaging access and encourage domestic manufacturing contribute to adoption. The expanding private healthcare sector and growth in medical tourism are also driving silent scan system demand. Collaborations between global manufacturers and regional distributors help extend reach and market availability.
Key Player Analysis:
- GE Healthcare (U.S.)
- Avotec Inc. (U.S.)
- CANON MEDICAL SYSTEMS CORPORATION (Japan)
- Hitachi High-Tech Corporation (Japan)
- Siemens Healthineers (Germany)
- United Imaging Healthcare Co., Ltd. (China)
Competitive Analysis:
The Silent Scan Technology Market is highly competitive, with several leading players focused on enhancing imaging systems to meet patient comfort and diagnostic accuracy. Key manufacturers, including Siemens Healthineers, GE Healthcare, Philips Healthcare, and Canon Medical Systems, are investing in advanced MRI technologies to integrate silent scan features into their existing systems. These companies prioritize continuous innovation in noise reduction algorithms and system design to differentiate their products. It fosters a competitive landscape where technological advancements, customer service, and brand reputation play crucial roles in market positioning. Smaller players and startups are also emerging, offering cost-effective and customizable solutions to cater to specific market segments, particularly in emerging regions. Strategic partnerships, collaborations with healthcare providers, and acquisitions are common strategies to expand market share and gain access to new customer bases. Ongoing product development and superior after-sales support remain essential for maintaining a competitive edge.
Recent Developments:
- In May 2025, GE Healthcare launched CleaRecon DL, an AI-based 3D reconstruction technology designed to improve cone-beam CT image quality.
- In March 2025, Canon Medical Systems received clearance for major AI enhancements on its Aquilion ONE / INSIGHT Edition CT scanner, including the PIQE 1024 matrix and Silver Beam technologies to expand high-resolution, low-dose CT imaging.
Market Concentration & Characteristics:
The Silent Scan Technology Market exhibits moderate concentration, with a few key players holding significant market shares. Major manufacturers such as Siemens Healthineers, GE Healthcare, and Philips Healthcare dominate the market, leveraging their advanced technological capabilities and established brand reputations. These companies invest heavily in research and development to integrate silent scan features into their MRI systems. It leads to continuous innovation, maintaining a competitive edge. The market also includes smaller players and regional manufacturers offering cost-effective solutions and catering to specific needs in emerging economies. Competitive dynamics are driven by product differentiation, technological advancements, and customer service excellence. Strategic alliances and partnerships between OEMs and healthcare providers further enhance market penetration. The market is characterized by high product complexity, long product life cycles, and substantial capital investment required for system installation and maintenance.
Report Coverage:
The research report offers an in-depth analysis based on Strength, Application, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Technological advancements in gradient coil design and noise-dampening materials are expected to further reduce acoustic noise in MRI systems, enhancing patient comfort.
- The incorporation of artificial intelligence in MRI systems is anticipated to improve image processing, reduce scan times, and enhance diagnostic accuracy.
- There is a growing emphasis on patient comfort and experience, driving the adoption of silent scan technologies in medical imaging.
- The need for quieter MRI systems is particularly critical in pediatric imaging, where patient cooperation is essential.
- Countries like India and China are expected to witness significant growth in the adoption of silent scan technologies due to expanding healthcare infrastructure.
- Increasing regulatory focus on patient-friendly imaging solutions is likely to drive the adoption of silent scan technologies.
- While initial costs remain a challenge, the long-term benefits of silent scan technologies may justify the investment for healthcare providers.
- The global silent scan technology market is projected to reflect steady growth, indicating increasing demand in the coming years.
- Key players like GE Healthcare, Siemens Healthineers, and Philips Healthcare are expected to continue leading the market through innovation and strategic partnerships.
- Advancements in low-field MRI and portable MRI systems may further enhance the accessibility and application of silent scan technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Silent Scan Technology Market?
What factors are driving the growth of the Silent Scan Technology Market?
What are the key segments within the Silent Scan Technology Market?
What are some challenges faced by the Silent Scan Technology Market?
Who are the major players in the Silent Scan Technology Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Silent Scan Technology Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Silent Scan Technology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 719 million → 2032: USD 869.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Silent Scan Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Silent Scan Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Silent Scan Technology Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Silent Scan Technology Market Drivers
- 3.3 Silent Scan Technology Market Restraints & Challenges
- 3.4 Silent Scan Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Silent Scan Technology Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Silent Scan Technology Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Silent Scan Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Silent Scan Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Silent Scan Technology Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Silent Scan Technology market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Silent Scan Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Silent Scan Technology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Silent Scan Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Silent Scan Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Silent Scan Technology Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Silent Scan Technology Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Silent Scan Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Silent Scan Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Silent Scan Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Silent Scan Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Silent Scan Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Silent Scan Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Silent Scan Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
