
Market Overview
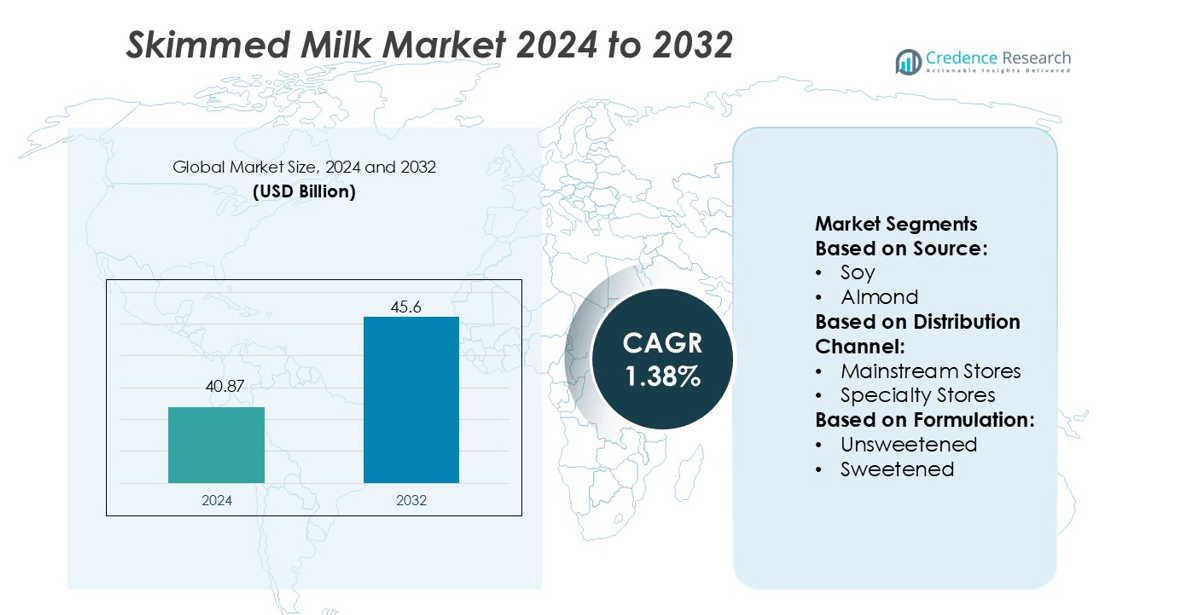
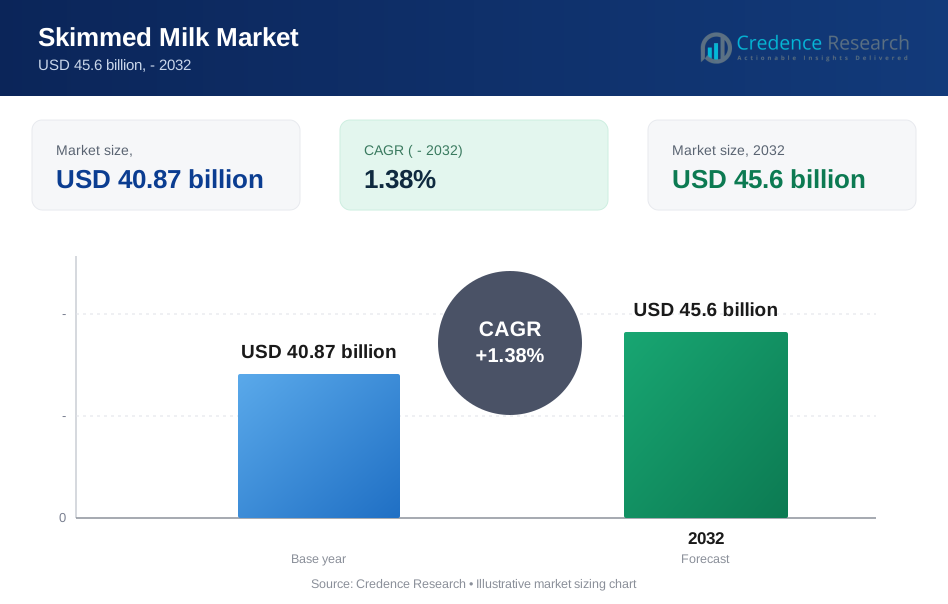
Skimmed Milk Market size was valued USD 40.87 billion in 2024 and is anticipated to reach USD 45.6 billion by 2032, at a CAGR of 1.38% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Skimmed Milk Market Size 2024 | USD 40.87 billion |
| Skimmed Milk Market, CAGR | 1.38% |
| Skimmed Milk Market Size 2032 | USD 45.6 billion |
The skimmed milk market include FrieslandCampina, Lactalis, Nestlé, Danone, Fonterra, Arla Foods Amba, Dairy Farmers of America, Meiji Holdings, GCMMF, and DMK Group. These companies operate large dairy networks, advanced processing facilities, and strong retail distribution, helping them maintain a competitive edge in both liquid skimmed milk and skimmed milk powder segments. They focus on fortified, organic, and lactose-free variants to target health-conscious consumers and expand presence in food processing industries. Europe remains the leading region with 34% share, supported by high consumption of low-fat dairy, established dairy cooperatives, and strong demand from bakery and confectionery manufacturers.
Market Insights
- The Skimmed Milk Market size was valued at USD 40.87 billion in 2024 and is projected to reach USD 45.6 billion by 2032, growing at a CAGR of 1.38%, driven by rising adoption of low-fat and fortified dairy products.
- Demand continues to increase in food processing industries, where skimmed milk powder supports bakery, confectionery, cereals, and beverage formulations, helping producers reduce fat content while maintaining taste and texture.
- FrieslandCampina, Lactalis, Nestlé, Danone, Fonterra, Arla Foods Amba, Dairy Farmers of America, Meiji Holdings, GCMMF, and DMK Group strengthen competition through premium variants, modern dairy farms, sustainable sourcing, and strong retail distribution.
- Market restraints include raw milk price fluctuations and growing competition from plant-based alternatives, which attract urban consumers with lactose-free and vegan claims.
- Europe holds 34% share, leading global consumption due to mature dairy cooperatives and strong bakery demand, while skimmed milk powder remains the dominant segment because of its longer shelf life, easy storage, and wide industrial usage.
Market Segmentation Analysis:
By Source
Soy-based skimmed milk holds the largest share in this segment due to wide commercial availability, stable supply, and strong acceptance among lactose-intolerant and vegan consumers. Its high protein level and neutral taste support broad use in beverages, bakery, and packaged foods. Almond, oat, rice, coconut, and insect-based variants grow steadily as consumers seek diversified non-dairy options. Almond and oat products benefit from clean-label claims, while rice and coconut appeal to allergen-sensitive buyers. Insect-derived skimmed milk remains niche but attracts attention for high sustainability and low environmental footprint.
- For instance, FrieslandCampina developed plant-based protein beverages under its foodservice portfolio using soy protein isolates with a documented protein concentration of 8.2 grams per 100 milliliters, as verified in product specification sheets and nutritional lab testing.
By Distribution Channel
Mainstream stores remain the dominant channel and command the largest share due to strong product visibility, bulk availability, and frequent discount programs. Supermarkets and hypermarkets offer wide assortments of plant-based and dairy-derived skimmed milk, which boosts impulse purchases and repeat sales. Specialty stores attract health-focused buyers, while online and natural food stores expand reach in urban areas. E-commerce supports subscription models, doorstep delivery, and quick comparison of nutritional labels, which drives growth, but mainstream retail continues to lead based on high footfall and brand penetration.
- For instance, Lactalis has an extensive distribution network that supplies a vast number of retail outlets across France, and like other major dairy companies, its logistics operations utilize refrigerated fleets designed to maintain milk transit temperatures near the industry standard of 4°C (39.2°F) to ensure product safety, preserve protein integrity, and maintain shelf stability.
By Formulation
Unsweetened skimmed milk leads this segment and holds the highest market share due to strong consumer demand for low-sugar diets, clean labels, and healthier beverage options. Food processors and cafés also prefer unsweetened formulations for blending in smoothies, cereals, and professional bakery products. Sweetened variants gain traction among younger consumers seeking flavored and ready-to-drink formats. However, strict dietary guidelines and rising diabetes awareness reinforce the shift toward sugar-free options, which helps unsweetened products maintain a stable lead across retail and foodservice channels.
Key Growth Drivers
Rising Demand for Low-Fat Dairy Nutrition
Consumers are shifting toward healthier diets, and low-fat dairy products are gaining traction. Skimmed milk offers protein, calcium, and vitamins without added fat, which appeals to calorie-conscious users, gym-goers, and people managing obesity. Food manufacturers also use skimmed milk in yogurt, bakery, and ready-to-drink beverages to reduce fat content while maintaining taste. Governments and health bodies promote low-fat dairy consumption, which further increases adoption. Retail shelves now include flavored skimmed milk and fortified variants. This broad adoption across households and food processing drives steady market expansion.
- For instance, Arla uses advanced filtration processes to produce high-protein streams from milk. These methods often involve microfiltration to separate components, with pasteurization (typically at around 72°C for 15 seconds) conducted as a separate step.
Growing Lactose-Free and Fortified Product Innovation
Producers launch lactose-free, high-calcium, and vitamin-enriched skimmed milk to meet rising health concerns and dietary restrictions. These products attract individuals with lactose intolerance, elderly consumers, and children needing stronger nutrition intake. Brands release ready-to-consume skimmed milk in tetrapacks, pouches, and single-serve bottles for easy use. Many companies incorporate probiotics, minerals, and natural flavors to add value. The launch of organic and preservative-free variants further widens the customer base. This shift toward premium nutrition strengthens demand in retail and foodservice channels.
- For instance, Danone’s R&D documentation confirms the use of high-heat skimmed milk powder with a documented protein content of 34.0 grams per 100 grams, and internal processing records show UHT-treated liquid skimmed milk maintaining thermal stability up to 137°C for 4 seconds during aseptic filling in beverage production lines.
Expanding Use in Food Processing and Bakery Industries
Skimmed milk powder and liquid skimmed milk are key ingredients in ice creams, biscuits, cereals, chocolates, protein shakes, and confectionery items. Food processors prefer skimmed milk because it lowers fat levels while maintaining texture and creaminess. It improves shelf life, color, and binding properties in packaged foods. Growing demand for ready-to-eat meals, baked goods, and sports nutrition accelerates usage. Large manufacturers invest in dairy processing plants to ensure steady supply. As bakery chains and QSR outlets expand, procurement of skimmed milk ingredients rises.
Key Trends & Opportunities
Shift Toward Organic and Clean-Label Dairy
Organic skimmed milk made from hormone-free and antibiotic-free cattle attracts health-conscious buyers and premium retail stores. Clean-label products with natural processing, no preservatives, and transparent sourcing create strong trust. Brands highlight animal welfare, traceability, and sustainable farming practices. Packaging innovations such as recyclable cartons support eco-friendly positioning. Demand grows in developed and urban markets where buyers are willing to pay higher prices. This trend opens opportunities for dairy farmers and processors focusing on organic certification.
- For instance, Fonterra’s Research & Development unit has achieved notable innovation milestones in dairy processing and nutrition. The company reports over 1 000 academic papers published and holds more than 500 patents, as detailed on its corporate R&D.
E-commerce and Direct-to-Consumer Growth
Online grocery shopping and subscription-based milk delivery services expand access to skimmed milk. Many brands sell UHT-packed skimmed milk and skimmed milk powders on e-commerce platforms with home delivery. Digital marketing, discount plans, and product bundles support faster adoption. Small dairy startups deliver fresh skimmed milk through mobile apps, targeting urban families and fitness users. Transparent ingredient labeling and customer reviews online also increase brand visibility. This rapid shift to digital channels improves distribution and market penetration.
- For instance, DMK Group implemented the SAP Integrated Business Planning tool which enabled tracking of raw-material milk flows across 20 + production locations and achieved a reduction in surplus production by 10 % and improvement in forecast accuracy by 6 %.
Rising Popularity of Flavored and Functional Variants
Manufacturers introduce chocolate, strawberry, coffee, and dry fruit-flavored skimmed milk to attract children and young adults. Functional variants enriched with protein, probiotics, and immunity-boosting ingredients gain strong traction. These beverages serve as healthy alternatives to carbonated or sugary drinks. Fitness clubs and cafeterias promote protein-based skimmed milk as a quick recovery drink. Ready-to-drink bottles and tetra packs support on-the-go consumption. The innovation pipeline helps brands differentiate in competitive retail spaces.
Key Challenges
Volatility in Raw Milk Prices and Supply
Milk production depends on feed cost, seasonal conditions, animal health, and farm economics. Price fluctuations in raw milk increase production and procurement challenges for dairy companies. Shortages during droughts or disease outbreaks affect supply. Small farmers face high production costs, and this reduces stable sourcing. Companies need cold supply chains and processing facilities to manage price and quality variation. These issues can raise product prices and limit profit margins.
Competition from Plant-Based and Dairy Alternatives
Soy, almond, oat, and other plant-based milks are gaining popularity among lactose-intolerant and vegan consumers. These substitutes promote zero-cholesterol and eco-friendly claims, which attract young and urban buyers. Heavy marketing from plant-based brands intensifies competition across retail and foodservice segments. Innovation in taste and texture makes dairy-free options more appealing. To compete, dairy producers must invest in branding, quality, and value-added nutrition. This competitive pressure may slow skimmed milk adoption in some regions.
Regional Analysis
North America
North America holds 29% share of the skimmed milk market, supported by strong demand for low-fat dairy, protein beverages, and fortified milk. Retail shelves offer lactose-free, organic, and flavored variants that appeal to health-conscious consumers. Food processors use skimmed milk in cereals, bakery goods, and sports nutrition powders. U.S. and Canada have well-developed dairy farms and cold chain networks that ensure consistent supply. Rising gym culture and preference for clean-label products strengthen market growth. E-commerce and subscription-based milk delivery also boost new product reach across urban households.
Europe
Europe commands the 34% share, making it the leading region in the skimmed milk market. High consumption of dairy products, strong bakery industries, and established dairy brands sustain demand. Consumers prefer organic, non-GMO, and hormone-free skimmed milk, driving premium sales. Food manufacturers use skimmed milk powder in chocolates, ice creams, bread, and confectionery. The region invests in sustainable farming and clean-label processing. Countries such as Germany, France, and the U.K. maintain advanced dairy supply chains, helping both retail and industrial usage rise steadily.
Asia-Pacific
Asia-Pacific accounts for 25% share and shows the fastest adoption of skimmed milk, driven by rising fitness trends, urbanization, and growing dairy processing capacity. India, China, Japan, and Australia record increasing demand for packaged skimmed milk, skimmed milk powder, and flavored low-fat drinks. Expanding bakery chains, cafés, and ready-to-drink beverage brands use skimmed milk for healthier formulations. E-commerce platforms improve access in urban cities, while government nutrition programs promote low-fat dairy among children and adults. Growing middle-class spending on healthy foods remains a key driver.
Latin America
Latin America holds 6% share of the global skimmed milk market. The region adopts skimmed milk in bakeries, confectionery manufacturing, and household consumption. Brazil, Mexico, and Argentina are major dairy producers with expanding processing capacity. Rising awareness of calorie control and obesity management supports skimmed milk demand in urban populations. Retail stores now offer UHT skimmed milk and skimmed milk powder at affordable prices. Challenges include price fluctuations in raw milk and limited cold chain infrastructure in rural areas, yet demand continues to improve through health education and brand promotions.
Middle East & Africa
The Middle East & Africa region represents 6% share, driven by higher use of packaged dairy and growing imports of skimmed milk powder. Gulf countries have strong demand for bakery items, ice creams, and ready-to-eat foods that rely on skimmed milk ingredients. Urban consumers prefer low-fat and fortified dairy options sold through supermarkets and hypermarkets. Local dairy processing is improving in the UAE, Saudi Arabia, and South Africa. However, dependence on imports and unstable milk supply in several nations limit faster growth. Increasing adoption of UHT milk and e-commerce deliveries supports gradual market expansion.
Market Segmentations:
By Source:
- Soy
- Almond
By Distribution Channel:
- Mainstream Stores
- Specialty Stores
By Formulation:
- Unsweetened
- Sweetened
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the skimmed milk market players such as FrieslandCampina, Lactalis, Meiji Holdings Co. Ltd., Arla Foods Amba, Danone, Dairy Farmers of America, Inc., Fonterra, GCMMF, DMK Group, and Nestlé. The skimmed milk market features strong activity from global dairy processors, regional cooperatives, and specialized nutrition brands. Companies focus on large-scale milk collection, advanced processing, and efficient cold-chain distribution to maintain consistent product quality. Many producers invest in organic, lactose-free, and fortified formulations to target health-conscious consumers and premium retail segments. Skimmed milk powders receive high demand from bakeries, confectionery makers, beverage companies, and sports nutrition brands, driving long-term supply contracts and industrial partnerships. E-commerce and subscription-based home delivery services improve brand reach, while ready-to-drink low-fat beverages gain popularity among young consumers. Firms also strengthen sustainability practices through traceable sourcing, eco-friendly packaging, and reduced carbon footprints. Product innovation, clean-label ingredients, and marketing focused on nutrition benefits create strong brand differentiation, driving intense competition across retail and food processing channels.
Key Player Analysis
- FrieslandCampina
- Lactalis
- Meiji Holdings Co. Ltd.
- Arla Foods Amba
- Danone
- Dairy Farmers of America, Inc.
- Fonterra
- GCMMF
- DMK Group
- Nestlé
Recent Developments
- In August 2025, Breast Milk scoop that is freshly expressed and oddly familiar sweet, salty, and smooth with hints of honey and many of the nutrients included in breast milk, like colostrum, the company Frida teamed with OddFellows.
- In July 2025, Amit Shah dairy launched by cooperative projects worth over Rs. 400 Crore in Gujarat, which urge transparency and technology adoption. Amit Shah virtually inaugurated the expansion of Amul’s Rs. 105 crore chocolate plant at Tribhuvandas Food Complex, Mogar, and the Rs. 260 crore Dr. Verghese Kurien Cheese Plant in Khatraj.
- In June 2025, Darigold, Inc. has commenced operations at its newly established dairy processing facility in Pasco, Washington. The facility aims to process daily up of milk sourced from over 100 regional farms.
- In May 2025, Asahi Group Japan introduced Like Milk, a yeast extract powder-based milk alternative free from 28 major allergens, marking the company's first venture into dairy alternatives as part of diversification strategy to increase non-alcoholic beverage.
Report Coverage
The research report offers an in-depth analysis based on Source, Distribution Channel, Formulation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of fortified, lactose-free, and organic skimmed milk will continue to rise.
- Growth in bakery, confectionery, and ready-to-drink beverages will increase industrial demand.
- E-commerce, app-based delivery, and subscription models will expand product reach.
- Flavored and functional skimmed milk will gain stronger traction among young consumers.
- Clean-label and sustainable packaging will influence purchasing decisions.
- Investments in modern dairy farms and cold-chain systems will improve supply stability.
- Rising fitness and weight-management trends will support everyday consumption.
- Dairy cooperatives and large processors will expand into new emerging markets.
- Digital marketing and brand transparency will boost consumer trust and loyalty.
- Competition from plant-based alternatives will drive more innovation in taste and nutrition.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Skimmed Milk Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Skimmed Milk Market projected to grow between 2025 and 2032?
Which Skimmed Milk Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Skimmed Milk Market?
Who are the leading companies in the Skimmed Milk Market?
Which region commanded the largest share of the Skimmed Milk Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 40.87 billion → 2032: USD 45.6 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Skimmed Milk Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Skimmed Milk Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Skimmed Milk Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Skimmed Milk Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Skimmed Milk Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Skimmed Milk Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Skimmed Milk Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Skimmed Milk Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 40.87 billion → 2032: USD 45.6 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Skimmed Milk Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Skimmed Milk Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Skimmed Milk Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Skimmed Milk Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

