
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Software Defined Data Center Market Size 2024 | USD 44,775 Million |
| Software Defined Data Center Market, CAGR | 22.8% |
| Software Defined Data Center Market Size 2032 | USD 231,538 Million |
Market Overview
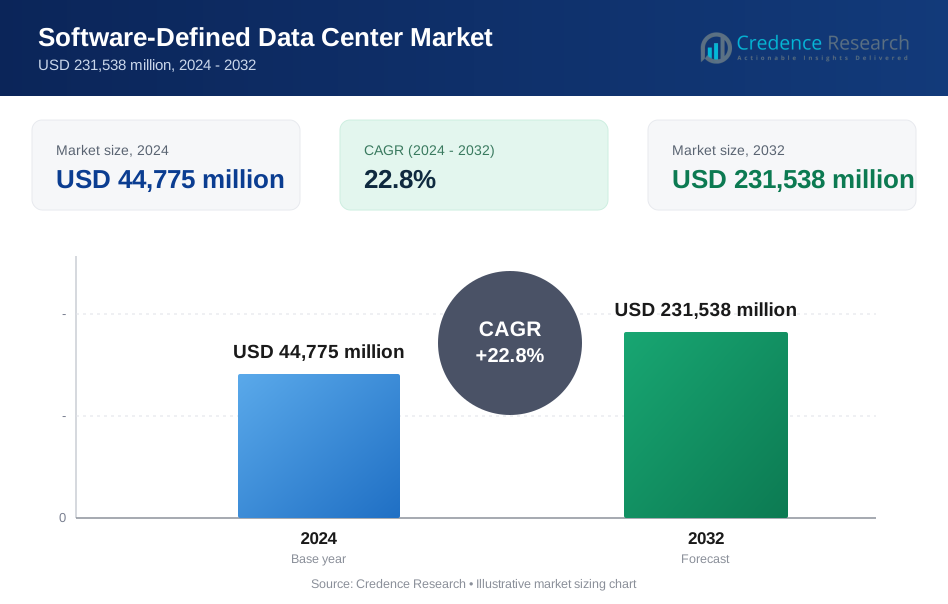
The Software Defined Data Center Market is projected to grow from USD 44,775 million in 2024 to USD 231,538 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 22.8%.
The Software Defined Data Center (SDDC) market is driven by the growing demand for flexible, scalable, and cost-efficient data center solutions. Increased adoption of cloud computing, virtualization, and automation technologies fuels market growth, enabling businesses to improve operational efficiency. Additionally, the rise in big data analytics, IoT, and AI applications demands advanced infrastructure, further boosting the SDDC market. Key trends include the integration of edge computing, hybrid cloud solutions, and increased investment in network security to support high-performance computing needs. These innovations are expected to accelerate the transition to fully automated and agile data center environments.
The Software Defined Data Center (SDDC) market is witnessing significant growth across various regions, driven by the demand for flexible, scalable, and cost-efficient IT infrastructure. North America, particularly the U.S., leads the market due to the presence of key players such as VMware, IBM, and Cisco. In the Asia-Pacific region, Japan and China are prominent markets, with companies like Fujitsu and Hitachi Vantara expanding their SDDC offerings. Key players such as Dell Technologies, Nutanix, and Hewlett Packard Enterprise are also contributing to the growth, leveraging advanced technologies to drive market innovation across global markets.
Market Drivers
Increased Agility and Scalability
Software Defined Data Centers (SDDCs) provide enhanced agility by enabling rapid deployment of IT services, allowing businesses to quickly adapt to evolving needs. For instance, IBM reports that SDDCs can significantly improve IT agility by pooling infrastructure resources and enabling policy-driven provisioning. Through dynamic resource allocation, SDDCs can allocate and reallocate resources in real-time, optimizing utilization based on demand. Furthermore, their scalability ensures that SDDCs can easily scale up or down in response to fluctuating workloads, maintaining optimal performance and cost efficiency.
Enhanced Security and Cloud Integration
SDDCs enhance security by creating isolated virtual networks, reducing the risk of unauthorized access. For instance, the Ministry of Electronics and Information Technology (MeitY) in India has emphasized the importance of policy-based security in ensuring compliance and protecting sensitive data. Additionally, SDDCs support hybrid cloud environments, allowing seamless integration with both public and private clouds. This provides flexibility, scalability, and a unified management platform for both on-premises and cloud-based resources, simplifying operations.
Improved Operational Efficiency
SDDCs significantly enhance operational efficiency through automation, reducing the need for manual intervention and minimizing human error. A centralized management platform simplifies the administration of complex data center environments, reducing overhead and increasing productivity. Additionally, SDDCs offer enhanced visibility into resource utilization and performance metrics, enabling proactive management and quicker troubleshooting, further improving overall efficiency.
Cost Reduction
SDDCs help reduce hardware costs by consolidating resources, minimizing the need for extensive physical infrastructure. This leads to lower initial investment and ongoing maintenance expenses. By optimizing resource utilization, SDDCs also minimize energy consumption and cooling costs, contributing to long-term savings. The accelerated deployment of services reduces time-to-market, allowing businesses to launch new applications and services more efficiently, boosting overall cost-effectiveness.
Market Trends
Adoption of Hybrid and Multi-Cloud Environments
Software Defined Data Centers (SDDCs) are increasingly integrated into hybrid and multi-cloud environments, offering flexible infrastructure that seamlessly combines public and private clouds. For instance, the Ministry of Electronics and Information Technology (MeitY) in India has emphasized the importance of hybrid cloud models in optimizing IT environments. This flexibility provides businesses with scalable, on-demand resources, enabling them to optimize their IT environments based on specific needs. Centralized management platforms have emerged as critical tools for simplifying the operation of these diverse IT environments, reducing complexity, and minimizing operational costs. These platforms streamline resource allocation and provide a unified approach to managing cloud environments, which is essential for organizations looking to ensure consistent performance and improve overall efficiency across both on-premises and cloud-based systems.
AI, Machine Learning, and Emerging Technologies Integration
The integration of AI and machine learning into SDDCs is transforming operations by leveraging predictive analytics to analyze vast data sets, forecast potential issues, and optimize resource allocation. This predictive capability enhances operational efficiency by preventing downtime and improving system performance. Additionally, AI and machine learning support the automation of routine tasks such as provisioning, configuration, and troubleshooting, further streamlining data center management. SDDCs are also adapting to the growing demand for edge computing and the Internet of Things (IoT), providing the scalable infrastructure required to handle distributed data processing and the vast volumes of data generated by IoT devices. This integration ensures that real-time data analysis can occur closer to the data source, enabling faster decision-making. Moreover, with a focus on sustainability and energy efficiency, SDDCs enable optimized resource utilization, contributing to greener, more sustainable data centers. With zero-trust security models and network segmentation, businesses can improve security and compliance, ensuring data protection and minimizing the risk of unauthorized access. Lastly, the rise of open-source solutions in the SDDC market provides cost-effective alternatives to proprietary options while encouraging community-driven innovation and the rapid development of new features, further advancing the capabilities of these data center solutions.
Market Challenges Analysis
Complexity and Skill Gap
One of the primary challenges with Software Defined Data Centers (SDDCs) is the complexity associated with their implementation and management. The steep learning curve requires organizations to invest significantly in specialized skills and expertise to effectively deploy and operate these advanced systems. Integrating SDDCs with existing legacy infrastructure can also present significant hurdles, often requiring time-consuming processes to ensure compatibility. Moreover, the shortage of skilled professionals capable of designing, implementing, and managing SDDCs adds to the difficulty. Organizations face the challenge of building internal capabilities through training and development programs, which can be costly and time-intensive. Overcoming this skill gap is crucial for businesses to unlock the full potential of SDDCs and avoid operational inefficiencies.
Security, Vendor Lock-In, and Cost Considerations
Security concerns are another prominent challenge for SDDC adoption. The virtualization and network abstraction inherent in SDDCs increase the attack surface, potentially introducing new vulnerabilities into the system. Ensuring robust data protection and privacy across distributed environments is vital to mitigating these risks. Additionally, the reliance on proprietary SDDC solutions can lead to vendor lock-in, restricting flexibility and driving up costs. Organizations may become dependent on specific vendors for support and maintenance, limiting their ability to adapt or switch providers without incurring significant costs. For instance, a study published in the Journal of Cloud Computing highlighted that vendor lock-in is a significant barrier due to the lack of standardization, which can limit an organization's ability to adapt or switch providers without incurring significant costs. Cost considerations are a further challenge, as the initial investment in SDDC infrastructure can be high, with ongoing maintenance and support costs continuing to rise over time. Furthermore, performance issues such as network latency and optimization concerns can impact the overall efficiency of the system. Ensuring that network design and optimization efforts are prioritized is essential to maintaining the desired performance levels. To mitigate these challenges, organizations can adopt a phased approach to implementation, select vendors with a strong commitment to open standards, and invest in robust security measures, automation, and continuous performance optimization.
Market Segmentation Analysis:
By Component:
The Software Defined Data Center (SDDC) market is primarily segmented into solutions and services. The solutions segment includes the software platforms and infrastructure that enable the virtualization and automation of data center operations. These solutions are essential for providing the flexibility and scalability that modern businesses demand. On the other hand, the services segment encompasses the professional and managed services offered by vendors to assist in the deployment, integration, and management of SDDC solutions. The growing need for operational efficiency and resource optimization has significantly boosted demand for both these components, as organizations look to automate and streamline their IT operations.
By Type:
The SDDC market can also be categorized by type, which includes Software Defined Compute, Software Defined Networking, Software Defined Storage, and other solutions like Software Defined Management and Security. Software Defined Compute (SDC) enables dynamic allocation of compute resources, while Software Defined Networking (SDN) allows more flexible and scalable network management. Software Defined Storage (SDS) offers storage virtualization that can reduce costs and improve data management. Other solutions like Software Defined Management and Security focus on optimizing data center management and ensuring a secure environment. The diversity in types addresses different operational needs, driving the market growth.
Segments:
Based on Component
- Solution
- Services
Based on Type
- Software Defined Compute
- Software Defined Networking
- Software Defined Storage
- Others (Software Defined Management, Security, etc.)
Based on Deployment
- Public
- Private
- Hybrid
Based on Industry
- IT & Telecom
- Government
- Healthcare
- Manufacturing
- BFSI
- Retail
- Others (Education, Automotive, etc.)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Software Defined Data Center (SDDC) market, accounting for approximately 35% of the global market. This dominance can be attributed to the region's robust IT infrastructure, high adoption of advanced technologies, and the presence of major tech giants, such as IBM, VMware, and Cisco, that drive innovation in SDDC solutions. The rapid adoption of cloud technologies, along with the increasing need for efficient resource management and scalability, further fuels the demand for SDDC in the region. Additionally, the ongoing digital transformation across industries like IT, healthcare, and manufacturing is propelling the market. North America's demand for SDDC is also supported by strong investments in data centers, edge computing, and AI-based solutions, positioning the region as a leader in SDDC deployment. The shift toward hybrid cloud environments, where enterprises require flexible and scalable solutions, has been another critical factor for the region’s dominance in the market.
Asia-Pacific
In contrast, the Asia Pacific (APAC) region is experiencing rapid growth in the SDDC market, with a market share of approximately 25%. This growth is largely driven by the increasing adoption of cloud-based solutions, advancements in network infrastructure, and the rise in data generation, particularly in emerging markets like China, India, and Japan. The APAC region is rapidly digitalizing its industries, especially IT, telecom, and healthcare, which leads to a growing demand for SDDC solutions that offer scalability, operational efficiency, and cost optimization. Moreover, the region's expanding network of data centers and the shift towards hybrid and multi-cloud environments are contributing factors to the market's expansion. The increased focus on data security and compliance, particularly in countries like Japan and India, further propels the need for software-defined solutions. As a result, the APAC region is expected to see continued strong growth in the SDDC market.
Key Player Analysis
- Dell Technologies (Texas, U.S.)
- Cisco Systems, Inc. (California, U.S.)
- NetApp (California, U.S.)
- IBM Corporation (New York, U.S.)
- VMware, Inc. (California, U.S.)
- Hitachi Vantara LLC (Tokyo, Japan)
- Nutanix (California, U.S.)
- Hewlett Packard Enterprise Development LP (Texas, U.S.)
- GreenPages, Inc. (Maine, U.S.)
- Fujitsu (Tokyo, Japan)
Competitive Analysis
The Software Defined Data Center (SDDC) market is highly competitive, with several leading players driving innovation and shaping industry trends. VMware, Inc., IBM Corporation, Cisco Systems, Inc., Nutanix, GreenPages, Inc., Dell Technologies, Fujitsu, Hewlett Packard Enterprise Development LP, Hitachi Vantara LLC, and NetApp are key players leveraging cutting-edge technologies to deliver scalable, flexible, and cost-effective solutions. Key players are focusing on advanced technologies such as virtualization, automation, and orchestration to optimize resource utilization, enhance operational efficiency, and reduce costs. Companies are also emphasizing the integration of AI, machine learning, and edge computing to further improve the agility of SDDC solutions. The competition in this market is driven by a focus on providing integrated solutions that simplify deployment and management, enabling businesses to adapt quickly to evolving market needs. As demand for cloud-based infrastructure continues to rise, players are intensifying their efforts to offer comprehensive, secure, and highly flexible solutions that can support diverse business requirements. This competition is expected to foster continued innovation and rapid adoption of SDDC technologies across various industries.
Recent Developments
- In January 2024, Cisco Systems partnered with Nutanix to deliver hybrid cloud services to customers present across the globe. Integration of Cisco’s Hyperconverged Compute with Nutanix to manage the infrastructure, application management operations, and cloud operations.
- In December 2023, Rackspace Technology Inc., an end-to-end hybrid, multi-cloud technology solution provider, launched SDDC enterprise and business solutions for SAP with VMware virtualized storage, compute, cloud, and networking management. This enterprise-grade solution offers various services, including VMware vRealize Suite, physical and virtual ops management, Rackspace data protection for disaster recovery, and VMware hybrid cloud extension.
- In July 2023, NTT Ltd. introduced its new software-defined data center campus in Chennai (India), spanning six acres and boasting a total capacity of 34.8 MW across two buildings. The first facility, operational with a 17.4 MW IT load, accompanies the arrival of the MIST subsea cable system in Chennai, solidifying NTT's position in the India data center industry.
Market Concentration & Characteristics
The Software Defined Data Center (SDDC) market is characterized by moderate concentration, with a few major players holding significant market share while a growing number of smaller companies contribute to the innovation and expansion of the sector. The market features a combination of large, established technology firms and emerging startups offering specialized solutions. Large players tend to dominate due to their resources, brand recognition, and comprehensive product portfolios that provide end-to-end solutions for IT infrastructure management. However, small and medium enterprises are gaining traction by offering highly customizable and cost-effective solutions that cater to specific market segments. The SDDC market is also marked by rapid technological advancements, with players continuously introducing cutting-edge features such as AI integration, automation, and enhanced security protocols to stay competitive. As a result, the market exhibits high innovation, with organizations increasingly prioritizing scalability, agility, and efficiency in their data center management strategies.
Report Coverage
The research report offers an in-depth analysis based on Component, Type, Deployment, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for SDDCs is expected to increase as businesses continue to prioritize flexibility and scalability in their IT infrastructure.
- Automation and AI integration will play a central role in enhancing operational efficiency and reducing manual intervention.
- Hybrid and multi-cloud environments will see greater adoption, with SDDCs enabling seamless integration between public and private clouds.
- As data security concerns grow, SDDCs will focus on improving security protocols, including zero-trust models and enhanced network segmentation.
- The shift towards edge computing will drive the need for SDDCs to support decentralized data processing and real-time analytics.
- Growing interest in network function virtualization (NFV) will fuel demand for software-defined networking and other related technologies.
- The market will witness an increasing number of organizations adopting SDDCs to improve their disaster recovery and business continuity strategies.
- Open-source SDDC solutions will continue to grow, offering more affordable options while fostering innovation through community-driven contributions.
- Energy efficiency and sustainability will become key drivers, as organizations focus on reducing the carbon footprint of their data center operations.
- The need for skilled professionals to manage and optimize SDDCs will lead to increased investments in training and development within the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increased Agility and Scalability
SDDCs enable rapid deployment and dynamic allocation of IT resources, allowing organizations to quickly adapt to changing business needs and scale operations efficiently, which is crucial for supporting digital transformation initiatives.
Enhanced Security and Cloud Integration
By supporting hybrid cloud environments and enabling policy-based security, SDDCs provide robust data protection and seamless integration between on-premises and cloud resources, addressing growing concerns around data privacy and compliance.
Improved Operational Efficiency through Automation
Automation capabilities in SDDCs reduce manual intervention, minimize human error, and streamline management, leading to lower operational costs and improved productivity for IT teams.
Cost Reduction and Resource Optimization
SDDCs consolidate hardware and optimize resource utilization, resulting in lower capital and operational expenditures, reduced energy consumption, and faster time-to-market for new services.
Adoption of Hybrid and Multi-Cloud Environments
The need for flexible, on-demand infrastructure is driving organizations to adopt SDDCs as a foundation for hybrid and multi-cloud strategies, enabling centralized management and consistent performance across diverse IT environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Software Defined Data Center?
What factors are driving the growth of the Software Defined Data Center?
What are the key segments within the Software Defined Data Center?
What are some challenges faced by the Software Defined Data Center?
Who are the major players in the Software Defined Data Center?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Software Defined Compute
- 1.2.2 Software Defined Networking
- 1.2.3 Software Defined Storage
- 1.2.4 Others (Software Defined Management, Security, etc.)
- 1.3 By Industry
- 1.3.1 IT & Telecom
- 1.3.2 Government
- 1.3.3 Healthcare
- 1.3.4 Manufacturing
- 1.3.5 BFSI
- 1.3.6 Retail
- 1.3.7 Others (Education, Automotive, etc.)
- 1.4 By Component
- 1.4.1 Solution
- 1.4.2 Services
- 1.5 By Deployment
- 1.5.1 Public
- 1.5.2 Private
- 1.5.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 44,775 million → 2032: USD 231,538 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Software-Defined Data Center Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Software-Defined Data Center Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Software-Defined Data Center Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Software-Defined Data Center Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Software-Defined Data Center Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Software-Defined Data Center Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Software-Defined Data Center Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Software-Defined Data Center Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 44,775 million → 2032: USD 231,538 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Software-Defined Data Center Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Software Defined Compute
- 12.3.6.2 Software Defined Networking
- 12.3.6.3 Software Defined Storage
- 12.3.6.4 Others (Software Defined Management, Security, etc.)
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 IT & Telecom
- 12.4.6.2 Government
- 12.4.6.3 Healthcare
- 12.4.6.4 Manufacturing
- 12.4.6.5 BFSI
- 12.4.6.6 Retail
- 12.4.6.7 Others (Education, Automotive, etc.)
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Solution
- 12.5.6.2 Services
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Deployment - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Public
- 12.6.6.2 Private
- 12.6.6.3 Hybrid
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Software-Defined Data Center End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Software-Defined Data Center Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Software-Defined Data Center Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Software-Defined Data Center Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 VMware, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 IBM Corporation
- 18.4 Cisco Systems, Inc.
- 18.5 Dell Technologies
- 18.6 Nutanix
- 18.7 Hewlett Packard Enterprise Development LP
- 18.8 NetApp
- 18.9 Hitachi Vantara LLC
- 18.10 Fujitsu
- 18.11 GreenPages, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

