
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
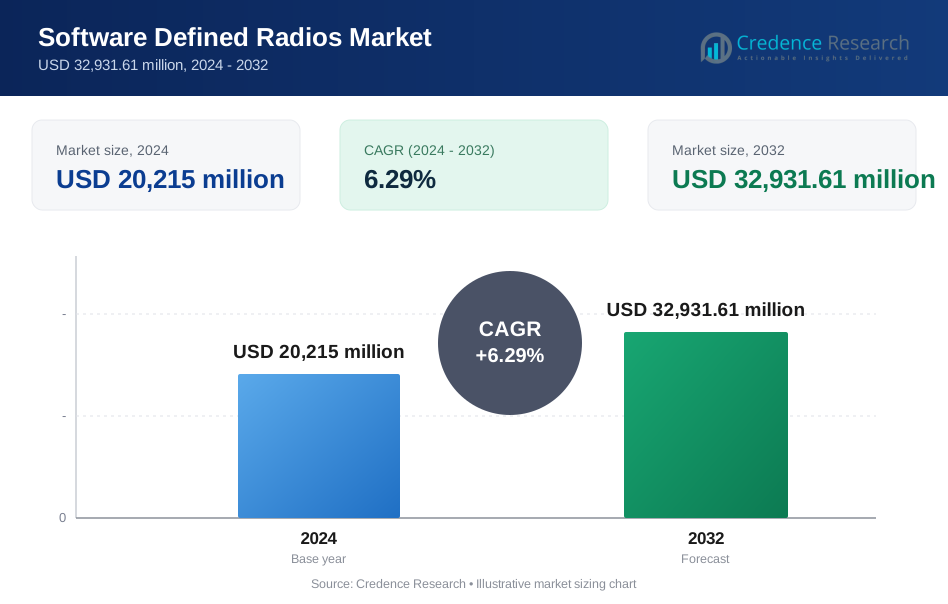
| Software Defined Radios Market Size 2024 | USD 20215 million |
| Software Defined Radios Market, CAGR | 6.29% |
| Software Defined Radios Market Size 2032 | USD 32931.61 million |
Market Overview:
The Software Defined Radios Market is projected to grow from USD 20215 million in 2024 to an estimated USD 32931.61 million by 2032, with a compound annual growth rate (CAGR) of 6.29% from 2024 to 2032.
Key drivers propelling the SDR market include the increasing need for efficient communication systems within the defense and public safety sectors and advancements in wireless communication standards. In defense, SDR technology plays a crucial role in providing secure, interoperable, and adaptable communication systems that can be upgraded with software updates rather than hardware replacements. In the telecommunications sector, SDR allows flexibility and scalability to accommodate the rapid adoption of 4G and 5G networks, which require infrastructure capable of evolving with changing standards. Additionally, the market is driven by the rise of IoT and connected devices, which demand robust, flexible communication solutions capable of handling diverse frequencies and protocols. SDR technology’s adaptability to multi-standard, multi-band, and multi-functional requirements makes it a preferred choice across industries seeking to optimize their communication infrastructure.
North America dominates the Software Defined Radios market, attributed to substantial defense spending and advanced telecommunications infrastructure across the United States and Canada. The region's focus on enhancing military capabilities with advanced communication technologies and increasing investment in R&D contributes to its strong market presence. Europe follows closely, driven by significant investments in defense and public safety communication technologies. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, propelled by expanding telecom networks and rising government initiatives to modernize military communication systems in countries like China and India. Latin America and the Middle East & Africa also show promising growth potential, fueled by increased defense budgets and the need for secure communication networks in various sectors.
Market Drivers:
Growing Demand for Advanced Communication in Defense Sector:
The defense sector is a primary driver of the Software Defined Radios (SDR) market due to the increasing need for secure, flexible, and interoperable communication systems. Modern military operations require sophisticated communication networks that can adapt quickly to various conditions and threats. SDR technology enables military forces to streamline communication across different branches and countries, ensuring effective coordination and collaboration in joint missions. The ability of SDRs to upgrade through software, rather than costly hardware changes, offers defense organizations a sustainable and scalable solution. For example, in February 2021, the Indian Ministry of Defense selected Bharat Electronics Limited (BEL) for the acquisition of Software Defined Radio Tactical (SDR-Tac) over three years, with a contract worth USD 136.9 million. This investment demonstrates the growing importance of SDR technology in modernizing military communication infrastructure.
Emergence of 5G Networks and IoT:
The rollout of 5G technology and the growth of the Internet of Things (IoT) are transforming telecommunications, driving the adoption of SDRs as versatile communication solutions. 5G networks require infrastructure that can handle higher data volumes, diverse frequencies, and multiple protocols, making SDRs highly valuable in this space. By supporting multi-band and multi-functional capabilities, SDRs allow telecom providers to offer faster, more reliable connections across varied devices and use cases. Similarly, the proliferation of IoT applications in industries like healthcare, automotive, and smart cities demands scalable and adaptable communication frameworks. SDR technology meets these demands by providing flexible platforms that adapt to emerging standards, thereby helping telecom operators and IoT stakeholders maintain performance and connectivity in complex network environments.
Public Safety and Emergency Response Requirements:
The need for reliable communication is crucial in public safety and emergency response, where interoperability across multiple agencies is often a challenge. SDRs address this issue by allowing first responders, police, firefighters, and emergency medical services to operate on a unified communication system that supports different frequencies and protocols. In critical scenarios, SDRs facilitate seamless communication between agencies, enhancing response times and coordination efforts. For example, the Hsinchu City Fire Department in Taiwan is using an emergency response vehicle equipped with a satellite-backhauled private 5G network based on Open RAN standards, which can be rapidly deployed to disaster zones to establish high-bandwidth, low-latency emergency communications. This demonstrates how SDR technology is being leveraged to improve crisis management and disaster response capabilities.
Technological Advancements and Cost-Efficiency:
Advancements in SDR technology and the increasing affordability of these systems are also driving market growth. As SDRs evolve, they are becoming more efficient, compact, and cost-effective, making them accessible for a broader range of applications. Modern SDR platforms can integrate a wider variety of features in a single unit, reducing the need for multiple devices and lowering operational costs. This versatility makes SDRs attractive for industries seeking robust communication solutions without incurring high costs. The ability to perform software-based upgrades also adds to SDRs' cost-efficiency, as users can implement new functionalities and protocols without investing in new hardware. As the technology advances, SDRs are expected to play an essential role in diverse fields where flexible and budget-friendly communication solutions are vital.
Market Trends:
Integration of Artificial Intelligence and Machine Learning:
One of the emerging trends in the Software Defined Radios (SDR) market is the integration of artificial intelligence (AI) and machine learning (ML) to enhance communication efficiency and adaptability. By incorporating AI and ML algorithms, SDRs can analyze vast amounts of data in real-time, enabling them to adapt frequencies, channels, and waveforms based on environmental factors and user needs. This intelligence enables SDRs to optimize spectrum utilization and avoid interference automatically, which is crucial in densely populated urban areas or high-traffic zones. With AI-driven capabilities, SDRs can make real-time adjustments to improve communication quality, especially in dynamic situations like defense operations, public safety, and disaster response. For instance, "Qualcomm has announced its newest Wi-Fi 7 chip with integrated AI/ML functions for application/traffic classification.
Growing Demand for Multi-Band and Multi-Mode Radios:
As industries increasingly seek flexible communication solutions, there is a rising demand for multi-band and multi-mode SDRs that can operate seamlessly across diverse frequencies and protocols. This trend is particularly prominent in sectors like defense and telecommunications, where the ability to connect over different networks without requiring multiple devices is essential. Multi-band SDRs can support various standards, including legacy systems and the latest communication protocols, making them highly adaptable and future-proof. The telecommunications sector, driven by the rollout of 5G and the anticipated evolution to 6G, has shown substantial interest in SDRs that can support these new standards. As a result, multi-band, multi-mode SDRs are becoming a preferred choice in the market, positioning themselves as versatile tools capable of handling evolving requirements. For example, "Per Vices' Crimson Software Defined Radio Transceiver allows users to send and receive wireless information anywhere from DC to 6 GHz, providing a versatile solution for various applications.
Miniaturization and Portability of SDR Devices:
Another significant trend in the SDR market is the miniaturization of SDR devices, which enhances portability and usability across different industries. Advancements in hardware design and the adoption of software-centric functionalities allow manufacturers to produce compact, lightweight SDRs without compromising on performance. This trend is especially relevant in defense and emergency response sectors, where personnel require portable communication tools that are easy to carry and deploy in diverse environments. The miniaturization of SDRs has also enabled their application in the commercial sector, particularly in wearable devices and portable communication tools for field operations. As miniaturized SDRs become more accessible, their adoption is likely to increase across various domains that require mobile, high-performance communication capabilities.
Increased Focus on Open Architecture and Interoperability:
With the growing need for interoperable communication systems, there is an increased emphasis on open architecture in SDR development. Open architecture enables different SDR systems to work together seamlessly, fostering interoperability across devices from multiple manufacturers and supporting diverse communication standards. This trend is especially important for military and public safety applications, where agencies and departments may use different equipment that must operate cohesively in critical situations. Open-architecture SDRs allow for easy integration of new technologies, simplifying upgrades and reducing dependency on specific vendors. This shift towards open systems not only improves cost-efficiency but also enhances operational flexibility, making SDR technology more versatile and future-ready across industries.
Market Restraints and Challenges:
High Initial Costs and Complexity of Implementation:
One of the primary restraints in the Software Defined Radios (SDR) market is the high initial costs associated with SDR technology and its complex implementation process. Although SDRs offer long-term cost savings through software updates rather than hardware replacements, the upfront investment remains substantial for many organizations, especially smaller entities or those with limited budgets. Additionally, the technology requires skilled personnel for installation, configuration, and ongoing maintenance, making it challenging for organizations that lack the necessary technical expertise. This complexity can deter potential users, particularly those in sectors with limited financial or human resources.
Concerns Over Security and Interoperability:
While SDRs provide flexibility and adaptability across different frequencies and protocols, security and interoperability challenges remain significant. Due to the software-based nature of SDRs, these systems can be more vulnerable to cyber threats if not properly secured. Ensuring data protection, especially in defense and public safety applications, requires robust security protocols, which can add complexity and cost. Additionally, achieving seamless interoperability among various SDR platforms and devices from different vendors can be challenging. Without standardized protocols and certifications, compatibility issues can arise, potentially impacting communication efficiency in mission-critical scenarios.
Regulatory and Spectrum Management Issues:
The SDR market also faces challenges from regulatory bodies and spectrum management concerns. As SDR technology spans multiple frequencies and protocols, it must comply with diverse regulatory requirements across different regions. The process of obtaining necessary certifications and meeting compliance standards can be time-consuming and costly, potentially delaying deployment. Furthermore, as the number of connected devices grows, efficient spectrum management becomes crucial, with SDR systems often facing difficulties in accessing necessary bandwidth in crowded or regulated spectrums. These regulatory and spectrum-related challenges limit SDR adoption, particularly in regions with stringent regulatory frameworks.
Market Segmentation Analysis:
By type, the market includes General Purpose Radio, Joint Tactical Radio System (JTRS), Cognitive/Intelligent Radio, and Terrestrial Trunked Radio (Tetra). Among these, JTRS holds a substantial share due to its strong adoption in military communications, while Cognitive Radio is gaining traction with its advanced adaptability to frequency changes, making it ideal for dynamic operational environments.
By components, SDRs are divided into hardware and software segments. The software segment is growing rapidly due to increasing demand for flexible, easily upgradable systems that support new communication standards without needing hardware changes. The hardware segment, encompassing critical components like amplifiers and converters, remains essential to SDR performance.
By frequency band, SDRs are classified into MF/HF, VHF, UHF, and other bands, with VHF and UHF bands prominently used across military and commercial applications due to their reliable signal range and clarity.
By platform segment includes airborne, naval, land, and space applications. Land-based SDRs hold a significant share, especially in defense and public safety, while airborne and naval platforms also witness strong demand in military operations.
By application, SDRs cater to both military & defense and commercial sectors. Military & defense remains the dominant segment, driven by SDRs' critical role in secure and interoperable communication, while commercial applications see growth from telecommunications and public safety enhancements.
Segmentation:
By Type
- General Purpose Radio
- Joint Tactical Radio System (JTRS)
- Cognitive/Intelligent Radio
- Terrestrial Trunked Radio (Tetra)
By Component
- Hardware
- Software
By Frequency Band
- MF/HF
- VHF
- UHF
- Other Bands
By Platform
- Airborne
- Naval
- Land
- Space
By Application
- Military & Defense
- Commercial
By Geographic
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America leads the Software Defined Radios (SDR) market, holding a significant market share due to substantial investments in defense and public safety infrastructure, particularly in the United States. The U.S. government’s focus on modernizing its defense communication systems and enhancing interoperability across military branches drives SDR adoption in the region. Additionally, North America’s advanced telecommunications infrastructure and early adoption of 5G technology increase the demand for SDRs in the commercial sector. With around 35% of the global market share, North America remains a pivotal region in the SDR market, and continuous government funding in defense projects, alongside rising private sector investment, will likely maintain its leadership position.
Europe
Europe holds the second-largest share in the SDR market, accounting for approximately 25% of the global market. Countries such as the United Kingdom, France, and Germany are at the forefront of SDR adoption, especially in defense and public safety applications. European defense initiatives, including collaborative projects among NATO members, bolster SDR demand as these systems enhance cross-country communication and secure operations. The region’s focus on technological advancement in public safety communication systems and critical infrastructure protection also contributes to SDR growth. Additionally, the expansion of telecommunication networks to support IoT and smart city projects further fuels SDR adoption in the European commercial sector.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the SDR market, holding around 20% of the global market share. This growth is largely driven by rising defense budgets in countries like China, India, Japan, and South Korea, which aim to modernize their military communication capabilities. Governments in these countries are investing heavily in advanced SDR technology to improve defense interoperability, situational awareness, and disaster response. Additionally, the rapid development of telecommunications networks, driven by the increasing penetration of 5G and IoT applications, has spurred demand for SDRs in the commercial sector. As these countries continue to invest in both defense and telecommunications infrastructure, Asia-Pacific is expected to expand its market share in the coming years.
Latin America
Latin America represents a smaller but steadily growing share of the SDR market, accounting for about 10% of the global market. Brazil and Mexico are key markets in the region, driven by government initiatives to enhance public safety and disaster response systems. The region’s growing telecommunications sector and need for reliable, flexible communication systems in remote and underserved areas contribute to SDR adoption. Despite budget constraints, several Latin American countries are investing in SDR technology for both military and public safety applications, gradually increasing their market presence.
Middle East and Africa
The Middle East and Africa hold approximately 10% of the global SDR market share, with growing demand driven by defense modernization programs and public safety initiatives. Countries such as the UAE and Saudi Arabia are investing in SDR technology to strengthen their military communication systems and enhance national security. Moreover, increasing concerns over regional conflicts and security challenges are prompting governments to invest in secure, interoperable SDR solutions. In Africa, SDR demand is also emerging in the telecommunications sector, where the technology supports efforts to expand mobile network coverage across remote and rural areas. As investment in infrastructure grows, the Middle East and Africa are likely to see steady SDR market growth.
Key Player Analysis:
- Analog Devices Inc.
- Anaren Inc.
- BAE Systems plc.
- Collins Aerospace Systems
- Data Device Corporation
- DataSoft
- Elbit Systems Ltd.
- Huawei Technologies Co. Ltd.
- Indra Sistemas S.A.
- L3Harris Technologies Inc.
- Microchip Technology Inc.
- Northrop Grumman Corporation
- Renesas Electronics Corporation
- RTX Corporation
- STMicroelectronics N.V.
- Texas Instruments Incorporated
Competitive Analysis:
The Software Defined Radios (SDR) market is highly competitive, with key players focusing on innovation, product development, and strategic partnerships to strengthen their market positions. Leading companies, including BAE Systems, Northrop Grumman, Harris Corporation, and Thales Group, dominate due to their extensive experience and established client relationships, particularly within the defense sector. These firms leverage their R&D capabilities to develop advanced SDR solutions, such as multi-band and cognitive radios, which cater to the specific needs of defense and public safety agencies. New entrants and smaller players compete by offering cost-effective, adaptable SDR solutions tailored for commercial applications, including telecommunications and IoT. Strategic alliances and collaborations also play a significant role, as companies work with government agencies and private firms to drive adoption. Continuous advancements in AI and ML integration within SDR technology are likely to further intensify competition as firms vie to lead in next-generation communication solutions.
Recent Developments:
- March 2024 – Elta Systems, a subsidiary of Israel Aerospace Industries (IAI), introduced its latest software-defined radio (SDR) with an operational range covering very high frequency, ultra-high frequency, and L-band frequencies, designed with modern architecture to enhance communication capabilities.
- March 2024 – Savronik, a prominent Turkish defense electronics supplier, launched an advanced version of its high-speed software-defined radio (SDR). The upgraded model offers double the data rate of previous versions, with custom waveforms and encrypted solutions to meet advanced security needs.
- December 2023 – Microchip Technology Inc. opened a new facility at Cambridge Research Park in the UK, expanding research and development capacity. This facility will support key markets, including automotive, IoT, and industrial sectors, by enhancing Microchip’s product offerings.
- November 2023 – Anaren Inc. inaugurated a new manufacturing facility in New York State, aimed at strengthening the U.S. microelectronics ecosystem. This facility will play a significant role in the defense and aerospace industry, complementing their RF microwave and microelectronics facility in Syracuse.
- August 2023 – Viasat Inc., a leader in communication technology, unveiled its new Black ICE SDR platform, which includes multiple models. This system incorporates custom waveforms to enable secure data transmission for critical mission operations.
- February 2023 – Analog Devices Inc. partnered with Marvell Technology, Inc. to introduce MIMO, a next-generation platform supporting Open Radio Access Network (RAN). By combining Analog’s RadioVerse transceiver SoC with Marvell’s OCTEON 10 Fusion 5G baseband processor, this platform accelerates advanced MIMO radio unit deployment with up to 40% reduced energy consumption.
Market Concentration & Characteristics:
The Software Defined Radios (SDR) market is moderately concentrated, with several dominant players holding a substantial share due to their technological expertise, established client relationships, and focus on R&D. Key companies such as BAE Systems, Harris Corporation, Thales Group, and Northrop Grumman lead the market, leveraging extensive resources to innovate and maintain competitiveness, especially within defense and public safety sectors. Market characteristics include a strong emphasis on interoperability, flexibility, and scalability, which are critical to meeting the demands of dynamic communication environments. The adoption of SDRs across multiple sectors—military, telecommunications, and public safety—highlights the technology’s versatility and adaptability. As SDRs can be upgraded via software rather than costly hardware changes, they represent a future-proof communication solution, appealing to a range of industries. This adaptability, combined with continuous advancements like AI integration and open architecture designs, fosters sustained interest and growth within the SDR market.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Component, By Frequency Band, By Platform and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for SDRs in military and defense will continue to drive market expansion as countries modernize communication systems.
- Increased integration of AI and machine learning in SDRs will enhance real-time adaptability and operational efficiency.
- Adoption of SDRs in 5G and IoT applications will accelerate as telecommunications seek scalable, multi-band solutions.
- Open architecture and interoperability advancements will enable seamless integration across various platforms and devices.
- Miniaturization and improved portability of SDR devices will boost usage in sectors needing mobile, high-performance communication tools.
- Expansion in public safety and emergency response systems will increase SDR deployment for reliable, cross-agency communication.
- Growing investments in R&D will foster innovations in SDR technology, driving down costs and improving functionality.
- Government initiatives in cybersecurity will enhance secure SDR technologies, addressing rising cyber threat concerns.
- Asia-Pacific will experience the fastest growth due to rising defense budgets and rapid telecom infrastructure development.
- Environmental sustainability efforts will focus on energy-efficient SDR designs, aligning with green technology trends in communications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Software Defined Radios market?
What are the key drivers of growth in the SDR market?
What challenges does the SDR market face?
What region is expected to experience the fastest growth?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Software Defined Radios Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Software Defined Radios Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 20,215 million → 2032: USD 32,931.61 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Software Defined Radios Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Software Defined Radios Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Software Defined Radios Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Software Defined Radios Market Drivers
- 3.3 Software Defined Radios Market Restraints & Challenges
- 3.4 Software Defined Radios Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Software Defined Radios Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Software Defined Radios Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Software Defined Radios category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Software Defined Radios Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Software Defined Radios Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Software Defined Radios market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Software Defined Radios Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Software Defined Radios Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Software Defined Radios Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Software Defined Radios (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Software Defined Radios Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Software Defined Radios Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Software Defined Radios Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Software Defined Radios Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Software Defined Radios Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Software Defined Radios Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Software Defined Radios Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Software Defined Radios Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Software Defined Radios Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
