
Market Overview:
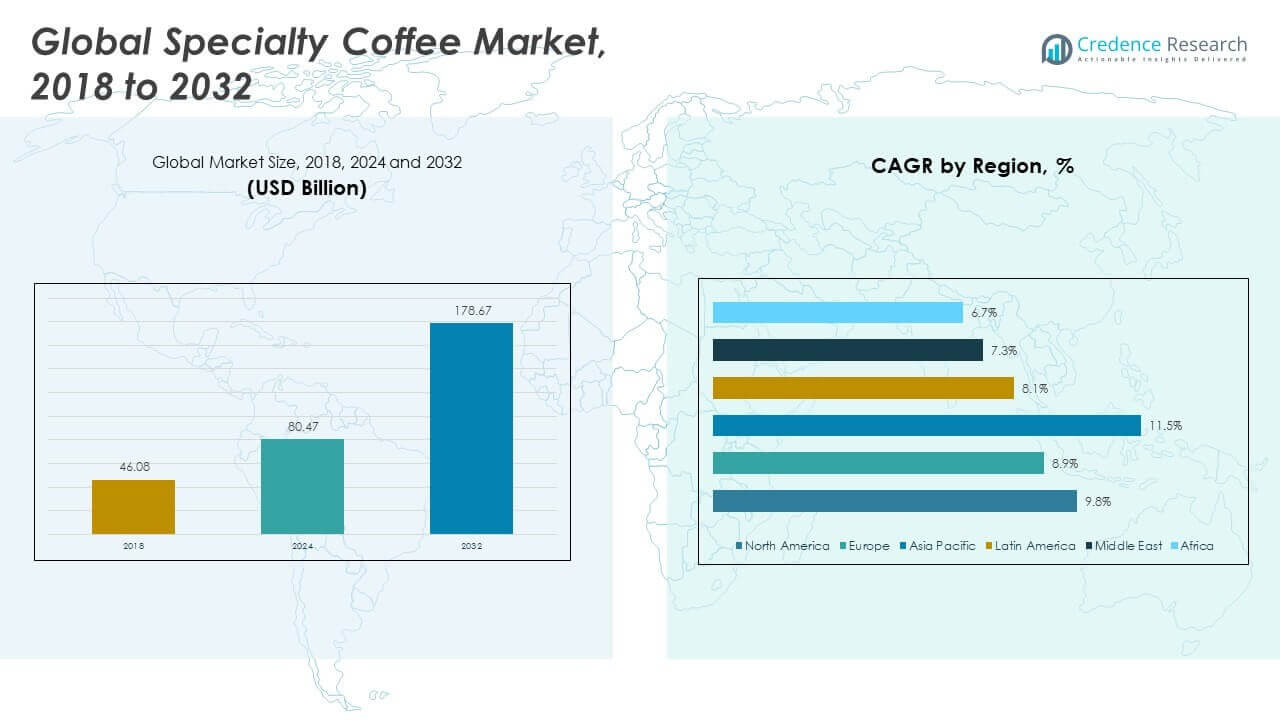
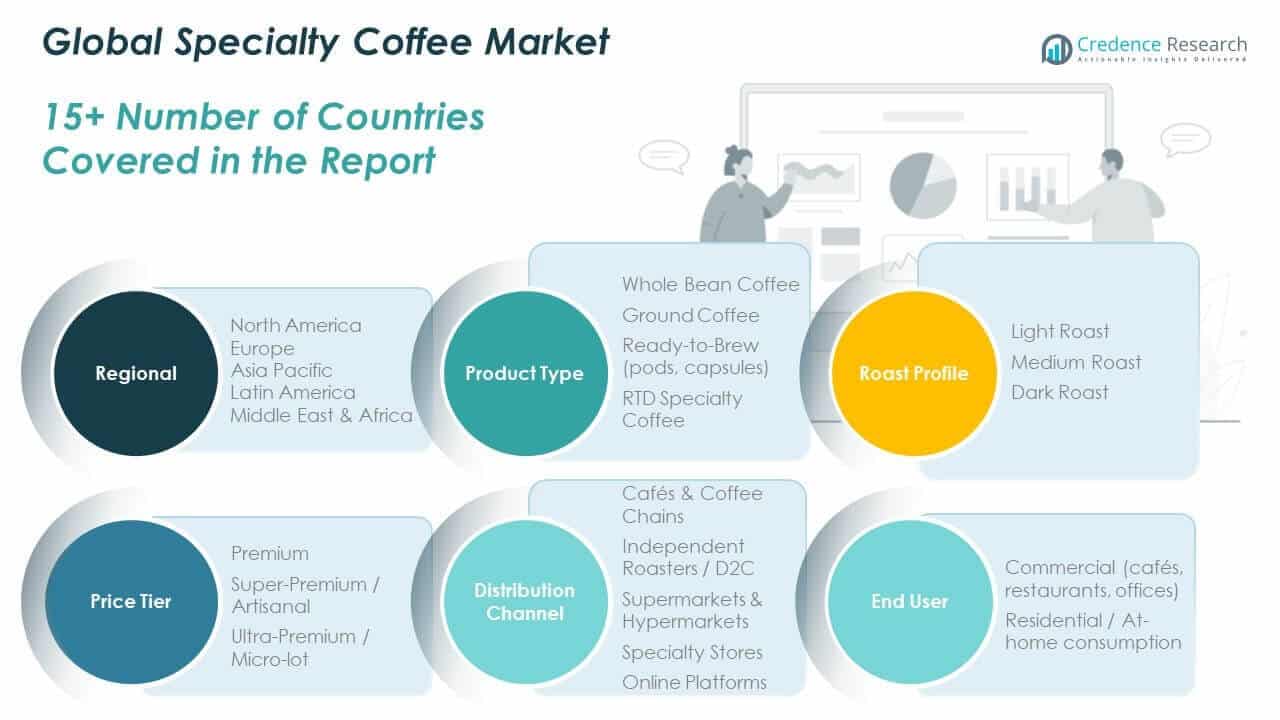
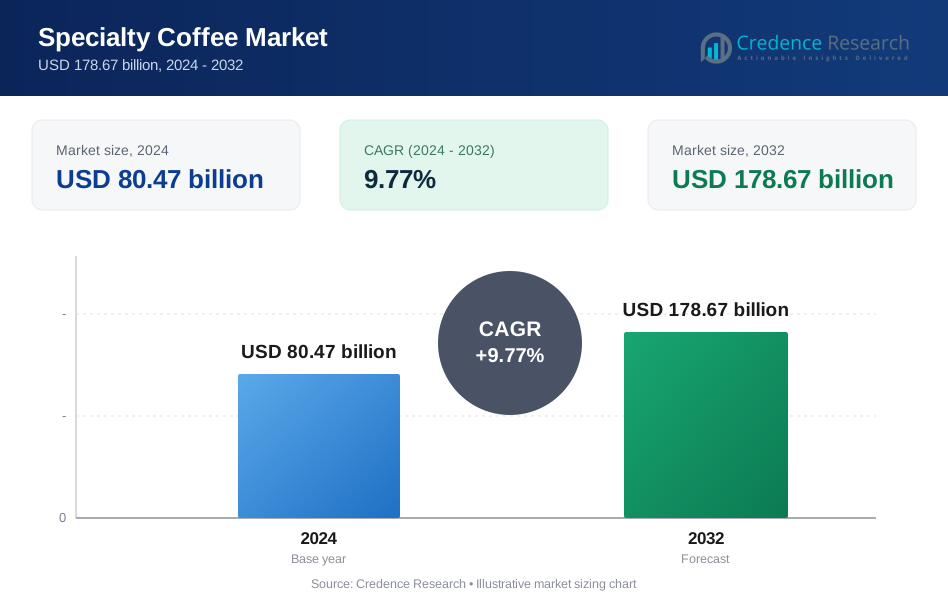
The Global Specialty Coffee Market size was valued at USD 46.08 billion in 2018, increased to USD 80.47 billion in 2024, and is anticipated to reach USD 178.67 billion by 2032, at a CAGR of 9.77% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Specialty Coffee Market Size 2024 | USD 80.47 billion |
| Specialty Coffee Market, CAGR | 9.77% |
| Specialty Coffee Market Size 2032 | USD 178.67 billion |
Demand rises as consumers prefer premium taste, traceable origins, and ethical sourcing. Cafés expand curated menus with single-origin beans and craft brewing. Home brewing grows with better grinders and espresso machines. Younger buyers seek unique flavors and freshness. Roasters invest in quality control and direct trade. Sustainability claims influence purchase decisions. Ready-to-drink options widen access beyond cafés. Digital channels help small roasters reach loyal audiences.
North America and Western Europe lead due to mature café cultures and high spending power. The United States, Germany, and the United Kingdom drive steady demand. Asia-Pacific emerges quickly, led by China, Japan, and South Korea. Urbanization boosts café visits and at-home brewing interest. Latin America grows as local consumption rises in producing countries. The Middle East shows momentum through premium café chains. Africa remains niche but gains specialty recognition.
Market Insights:
- The Global Specialty Coffee Market was valued at USD 46.08 billion in 2018, reached USD 80.47 billion in 2024, and is projected to reach USD 178.67 billion by 2032, expanding at a CAGR of 9.77%.
- North America led with about 44% share in 2024, followed by Europe at around 27% and Asia Pacific at nearly 20%, supported by strong café culture, premium spending, and mature retail networks.
- Asia Pacific is the fastest-growing region with about 20% share, driven by urbanization, youth adoption, expanding café chains, and rapid digital retail growth.
- By product type, whole bean coffee held the largest share at roughly 45%, reflecting demand for freshness, home brewing, and premium quality perception.
- Ground coffee and pods together accounted for nearly 45%, while RTD specialty coffee held close to 10%, supported by convenience and on-the-go consumption trends.
Market Drivers:
Premium Taste Preference And Quality Differentiation Across Consumer Segments
Consumers show strong preference for complex flavors and consistent quality. Specialty beans offer distinct taste profiles and aroma depth. Roasters highlight origin stories to justify premium pricing. Cafés train staff to explain flavor notes clearly. The Global Specialty Coffee Market benefits from this value shift. Buyers accept higher prices for verified quality. Brand loyalty improves with sensory consistency. Quality grading builds trust across channels.
- For instance, Blue Bottle Coffee uses 84+ SCA-scored beans and roasts within 48 hours. Cafés train staff to explain flavor notes clearly.
Ethical Sourcing And Transparency Expectations From Informed Coffee Buyers
Consumers expect clear sourcing and fair trade practices. Roasters publish farm-level details and sourcing methods. Certifications support trust and brand credibility. Farmers receive stable demand through direct relationships. The Global Specialty Coffee Market gains from ethical alignment. Transparency reduces buyer skepticism. Story-led packaging improves shelf appeal. Ethical focus supports long-term supply stability.
- For instance, Intelligentsia Coffee maintains its Direct Trade network across 14 countries in North America, South America, and Africa. The company sources from dozens of suppliers, which include smallholder family farms, large estates, and community farmer organizations.
Growth Of Specialty Cafés And Experiential Consumption Culture
Urban café formats emphasize craft and experience. Baristas showcase manual brewing skills daily. Store design supports premium positioning. Social settings drive repeat visits. The Global Specialty Coffee Market gains visibility through cafés. Experiential value lifts average spend. Menu innovation keeps customer interest high. Community events strengthen brand presence.
Rising Home Brewing Adoption And Equipment Accessibility
Home consumers invest in grinders and brewers. Online guides simplify advanced brewing methods. Subscription models ensure fresh bean supply. Retailers bundle beans with equipment. The Global Specialty Coffee Market expands beyond cafés. Home rituals deepen product engagement. Consistent access supports repeat purchases. Equipment access lowers skill barriers.
Market Trends:
Expansion Of Ready-To-Drink Specialty Coffee Offerings
Brands launch bottled and canned specialty options. Cold brew gains strong urban traction. Flavor innovation targets younger buyers. Convenience supports on-the-go consumption. The Global Specialty Coffee Market adapts to lifestyle shifts. Packaging design signals premium quality. Shelf presence expands retail reach. Distribution widens brand exposure.
- For instance, La Colombe sells Draft Lattes using nitrous oxide (\(N_{2}O\)) infusion to create a textured, stable microfoam that replicates a true latte.
Rise Of Micro-Roasters And Hyperlocal Brand Positioning
Small roasters focus on local demand. Limited batches create exclusivity value. Community branding builds strong loyalty. Short supply chains improve freshness. The Global Specialty Coffee Market supports niche growth. Local stories resonate with buyers. Direct sales improve margins. Social media boosts visibility.
- For instance, Stumptown Coffee Roasters prints roast dates on every bag and operates regional roasting hubs.
Data-Driven Roasting And Flavor Profiling Techniques
Roasters adopt software for profile control. Sensors track temperature and time precisely. Repeatability improves batch consistency. Quality control becomes more scientific. The Global Specialty Coffee Market benefits from precision. Waste levels decline through better control. Training costs reduce over time. Process data supports scaling.
Subscription Commerce And Direct-To-Consumer Channels
Subscriptions offer curated bean selections monthly. Predictable demand aids inventory planning. Online storefronts reduce reliance on cafés. Customer data guides product refinement. The Global Specialty Coffee Market gains channel diversity. Loyalty increases through personalization. Logistics partners ensure timely delivery. Digital reach expands globally.
Market Challenges Analysis:
Supply Volatility And Climate Sensitivity In Coffee-Producing Regions
Weather shifts affect yield and bean quality. Farmers face unpredictable harvest cycles. Input costs rise under climate stress. Roasters struggle with consistent sourcing. The Global Specialty Coffee Market faces supply risk. Long-term contracts limit flexibility. Quality variation impacts brand trust. Risk management becomes essential.
High Cost Structure And Price Sensitivity Among End Consumers
Premium beans carry higher procurement costs. Skilled labor raises operating expenses. Equipment investment strains small players. Price gaps limit mass adoption. The Global Specialty Coffee Market faces margin pressure. Consumers trade down during inflation periods. Promotions reduce perceived exclusivity. Cost control demands discipline.
Market Opportunities:
Emerging Demand From Asia-Pacific And Urban Youth Segments
Urban youth explore café culture rapidly. Social media shapes coffee preferences. New cities attract specialty formats. Education improves taste awareness. The Global Specialty Coffee Market sees fresh demand. Franchise models ease market entry. Local menus support adoption. Brand discovery accelerates.
Product Innovation Through Functional And Sustainable Coffee Lines
Functional blends add wellness appeal. Low-acid and infused variants attract new buyers. Sustainable packaging improves brand image. Innovation supports premium positioning. The Global Specialty Coffee Market gains differentiation. Retailers welcome novel formats. R&D strengthens competitive edge. Innovation cycles shorten.
Market Segmentation Analysis:
By Product Type
Product type segmentation highlights strong demand for whole beans, ground coffee, and specialty formats. Whole beans lead due to freshness control and home brewing growth. Ground variants serve convenience-led buyers across retail channels. Specialty formats support cafés and premium gifting. Regional analysis shows mature demand in the United States and Europe. Asia Pacific records faster adoption through urban retail expansion. Latin America benefits from local consumption growth. The Global Specialty Coffee Market reflects clear product differentiation across regions.
- For instance, Starbucks sells whole-bean coffee across its stores and online channels worldwide.
By Roast Profile
Roast profile analysis shows balanced demand across light, medium, and dark roasts. Light roasts attract flavor-focused consumers and specialty cafés. Medium roasts dominate mainstream premium consumption. Dark roasts retain loyal demand in traditional markets. It sees strong preference diversity across regions. The United States and Europe maintain stable roast segmentation. Asia Pacific shows experimentation with lighter profiles. Emerging regions favor familiar roast styles.
- For instance, Nestlé expanded Nespresso origin-specific capsules with lighter roast profiles.
By Price Tier
Price tier segmentation separates premium, super-premium, and accessible specialty offerings. Premium tiers dominate volume across mature markets. Super-premium products gain traction among enthusiasts. It supports brand positioning through tier clarity. The United States and Europe show structured tier adoption. Asia Pacific displays rising premium penetration. Latin America balances affordability with quality. Price sensitivity shapes regional strategies.
By Distribution Channel
Distribution channels span cafés, specialty stores, online platforms, and retail chains. Cafés remain key for brand discovery. Online channels support direct consumer engagement. It benefits from omni-channel strategies. Developed regions lead digital adoption. Asia Pacific shows rapid e-commerce growth. Physical retail sustains visibility in emerging markets.
By End User
End users include households, cafés, restaurants, and offices. Household consumption grows through home brewing. Commercial users drive consistent demand cycles. It balances retail and foodservice exposure. Regional patterns vary by lifestyle and café density.
Segmentation:
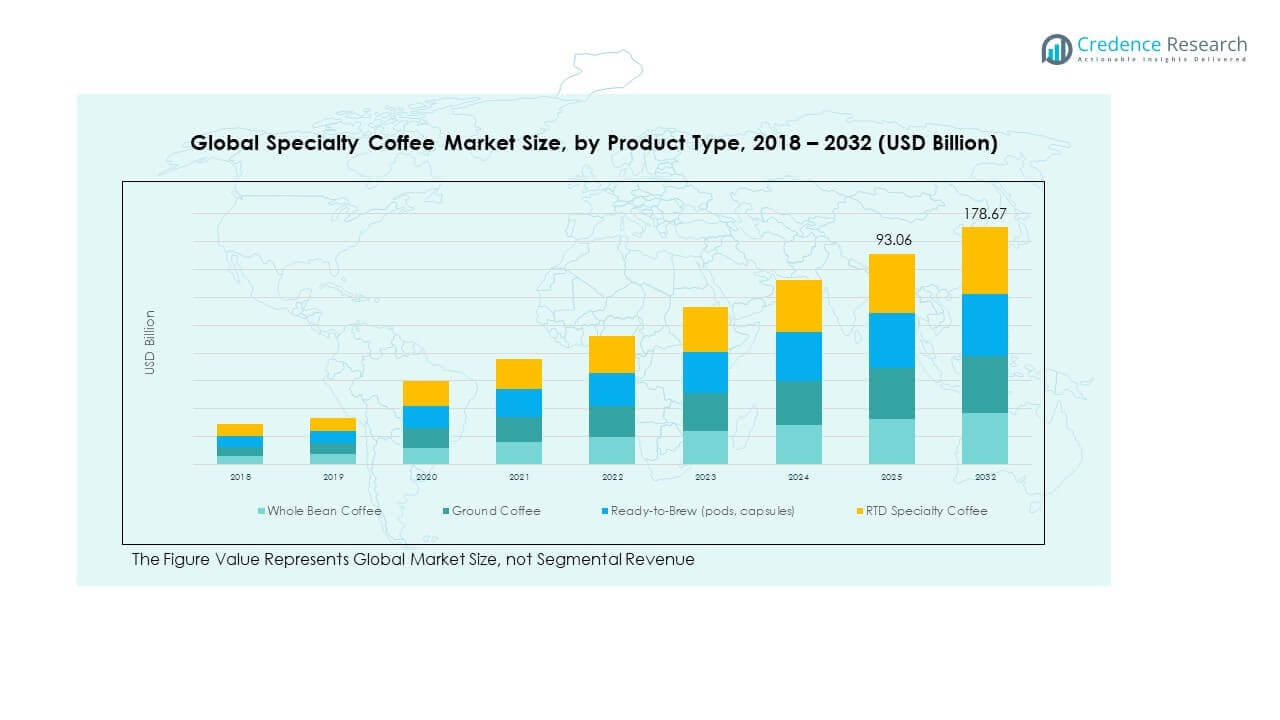
By Product Type- Whole Bean Coffee
- Ground Coffee
- Pods & Capsules
- RTD Specialty Coffee
- Light Roast
- Medium Roast
- Dark Roast
- Premium
- Super-Premium
- Accessible Specialty
- Cafés & Coffee Shops
- Specialty Stores
- Supermarkets & Hypermarkets
- Online Retail
- Households
- Cafés & Restaurants
- Offices & Corporate Spaces
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Specialty Coffee Market size was valued at USD 20.63 billion in 2018 to USD 35.66 billion in 2024 and is anticipated to reach USD 79.38 billion by 2032, at a CAGR of 9.8 during the forecast period. The region accounts for the largest market share, driven by strong café culture and high disposable income. The United States leads consumption through specialty cafés and home brewing trends. Canada supports steady demand through premium retail formats. Consumers show strong awareness of origin and roast quality. Innovation in ready-to-drink formats sustains momentum. Brand loyalty remains high across urban centers. The Global Specialty Coffee Market maintains maturity and stability in North America.
Europe
The Europe Global Specialty Coffee Market size was valued at USD 12.73 billion in 2018 to USD 21.41 billion in 2024 and is anticipated to reach USD 44.67 billion by 2032, at a CAGR of 8.9 during the forecast period. Europe holds a significant market share supported by long-standing coffee traditions. Germany, Italy, and the United Kingdom lead specialty consumption. Consumers value roast craftsmanship and ethical sourcing. Independent cafés strengthen regional diversity. Retail penetration remains strong across supermarkets and specialty stores. Premium pricing finds acceptance among urban consumers. The Global Specialty Coffee Market shows stable expansion across Europe.
Asia Pacific
The Asia Pacific Global Specialty Coffee Market size was valued at USD 8.60 billion in 2018 to USD 16.31 billion in 2024 and is anticipated to reach USD 41.15 billion by 2032, at a CAGR of 11.5 during the forecast period. The region shows the fastest growth and rising market share. China, Japan, and South Korea drive demand through urban café expansion. Younger consumers adopt specialty coffee lifestyles rapidly. Digital platforms boost brand discovery. Home brewing gains traction in metros. International brands expand footprints aggressively. The Global Specialty Coffee Market benefits from strong momentum in Asia Pacific.
Latin America
The Latin America Global Specialty Coffee Market size was valued at USD 2.18 billion in 2018 to USD 3.76 billion in 2024 and is anticipated to reach USD 7.40 billion by 2032, at a CAGR of 8.1 during the forecast period. The region holds a modest market share but shows steady progress. Brazil and Colombia lead specialty consumption locally. Domestic appreciation for premium coffee improves. Café culture expands in major cities. Export-oriented producers promote local specialty brands. Pricing sensitivity shapes product offerings. The Global Specialty Coffee Market gains balanced growth in Latin America.
Middle East
The Middle East Global Specialty Coffee Market size was valued at USD 1.21 billion in 2018 to USD 1.93 billion in 2024 and is anticipated to reach USD 3.56 billion by 2032, at a CAGR of 7.3 during the forecast period. The region captures a small but growing market share. Gulf countries lead demand through premium cafés. Social coffee rituals support consumption frequency. Imported specialty brands dominate shelves. High-end retail supports premium positioning. Younger consumers drive café visits. The Global Specialty Coffee Market expands steadily in the Middle East.
Africa
The Africa Global Specialty Coffee Market size was valued at USD 0.73 billion in 2018 to USD 1.41 billion in 2024 and is anticipated to reach USD 2.51 billion by 2032, at a CAGR of 6.7 during the forecast period. Africa holds the smallest market share despite production strength. Ethiopia and Kenya show rising domestic specialty demand. Urbanization supports café growth. Awareness of premium coffee improves slowly. Infrastructure gaps limit rapid expansion. Local brands focus on origin-led storytelling. The Global Specialty Coffee Market shows early-stage development in Africa.
Key Player Analysis:
- Nestlé
- Starbucks Corporation
- JAB Holding
- Lavazza Group
- Illycaffè
Competitive Analysis:
The Global Specialty Coffee Market features strong competition among multinational brands and premium-focused players. Large companies leverage scale, sourcing networks, and brand equity. Mid-sized roasters compete through quality control and origin transparency. Independent brands focus on niche positioning and local loyalty. Product differentiation supports competitive strength across regions. Innovation in roast profiles and formats shapes rivalry. Distribution reach defines market visibility. It reflects a mix of consolidation and fragmented premium offerings.
Recent Developments:
- In a transformative strategic move announced on November 3, 2025, Starbucks agreed to sell a controlling 60% stake in its China business to private equity firm Boyu Capital in a joint venture valued at $4 billion. Under this structure, Starbucks retained a 40% ownership stake while Boyu Capital assumed operational control, marking the first time Starbucks has partnered with an outside firm to manage its China operations. CEO Brian Niccol stated that "Boyu's deep local knowledge and expertise will help accelerate our growth in China, especially as we expand into smaller cities and new regions". The transaction is expected to close in the second quarter of fiscal 2026 following regulatory approvals, with Starbucks projecting the total value of its China retail business to exceed $13 billion when factoring in the sale proceeds, the value of its remaining stake, and licensing fees over the next decade.
- In September 2025, Nestlé Professional made a strategic move to strengthen its presence in the specialty foodservice segment by launching NESCAFÉ BARISTA, a whole bean coffee range designed specifically for the food service and B2B sector. The launch, which became available through Booker from September 10 and other wholesalers from September 15, introduced two initial blends Signature and Espresso targeting independent cafés and quick-service restaurants. This initiative reflects a broader consumer shift away from instant coffee toward premium whole bean offerings, with George Burrell, the OOH brand manager for Nestlé Professional UK & Ireland, emphasizing that the new range delivers "barista-style coffee worth waiting for".
- Illycaffè, the Italian premium coffee brand, executed a strategic upstream integration strategy in September 2025 by acquiring an 80% stake in Capitani, a Como-based manufacturer of single-serve capsule coffee machines. The transaction, expected to close in October 2025 pending regulatory approvals, reflected illycaffè's transition from a traditional coffee roaster to a holistic systems company. CEO Cristina Scocchia emphasized that "the geopolitical context, trade barriers, tariffs, and rising raw material costs are significant challenges, but we have chosen to continue focusing on Made in Italy and innovation, investing in our country and strengthening the Italian production chain". The partnership aims to double Capitani's revenues within five years by leveraging combined synergies, industrial efficiency, and innovation capabilities while reducing reliance on non-European suppliers.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Roast Profile, Price Tier, Distribution Channel, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Premium specialty coffee demand will continue to expand across urban and metropolitan markets.
- Home brewing adoption will rise as consumers invest in quality equipment and beans.
- Direct trade and ethical sourcing models will gain wider acceptance among buyers.
- Ready-to-drink specialty coffee formats will see steady growth in retail channels.
- Asia Pacific will remain a major growth engine due to youth-driven consumption.
- Digital and subscription-based sales channels will strengthen brand reach.
- Sustainability practices will increasingly influence purchasing decisions.
- Micro-roasters will maintain relevance through local and niche positioning.
- Product innovation will support differentiation across roast and format offerings.
- Café-led branding will continue to shape consumer loyalty and engagement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Specialty Coffee Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Specialty Coffee Market projected to grow between 2025 and 2032?
Which Global Specialty Coffee Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Specialty Coffee Market?
Who are the leading companies in the Global Specialty Coffee Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Specialty Coffee Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Specialty Coffee Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 80.47 billion → 2032: USD 178.67 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Specialty Coffee Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Specialty Coffee Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Specialty Coffee Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Specialty Coffee Market Drivers
- 3.3 Specialty Coffee Market Restraints & Challenges
- 3.4 Specialty Coffee Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Specialty Coffee Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Specialty Coffee Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Specialty Coffee category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Specialty Coffee Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Specialty Coffee Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Specialty Coffee market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Specialty Coffee Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Specialty Coffee Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Specialty Coffee Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Specialty Coffee (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Specialty Coffee Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Specialty Coffee Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Specialty Coffee Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Specialty Coffee Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Specialty Coffee Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Specialty Coffee Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Specialty Coffee Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Specialty Coffee Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Specialty Coffee Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
