
Market Overview:
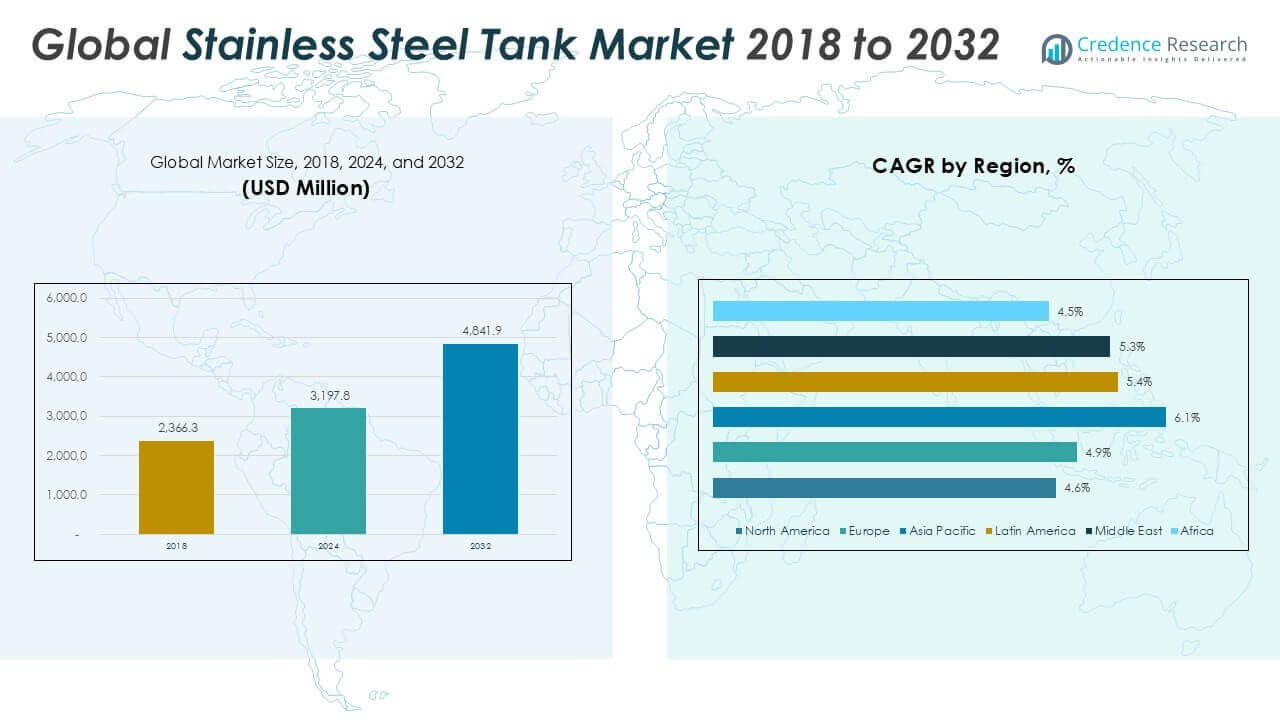
The Stainless-steel Tank market size was valued at USD 2,366.3 million in 2018, increased to USD 3,197.8 million in 2024, and is anticipated to reach USD 4,841.9 million by 2032, at a CAGR of 5.35% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Stainless-Steel Tank Market Size 2024 | USD 3,197.8 million |
| Stainless-Steel Tank Market, CAGR | 5.35% |
| Stainless-Steel Tank Market Size 2032 | USD 4,841.9 million |
The stainless-steel tank market is led by prominent players such as Paul Mueller Company, CST Industries, Pfaudler Inc., Highland Tank & Manufacturing Company, and Tank Connection, known for their extensive product portfolios and global distribution networks. These companies focus on customized solutions, technological advancement, and compliance with industry-specific regulations to maintain a competitive edge. Asia Pacific emerges as the leading region, holding 35.8% of the global market share in 2024, driven by rapid industrialization, expanding manufacturing sectors, and rising demand for hygienic storage solutions in countries like China, India, and Japan. Europe and North America follow, supported by strong presence of food, beverage, and pharmaceutical industries.
Market Insights
- The global stainless-steel tank market was valued at USD 3,197.8 million in 2024 and is expected to reach USD 4,841.9 million by 2032, growing at a CAGR of 5.35% during the forecast period.
- Growth is primarily driven by rising demand across food and beverage, pharmaceutical, and water treatment industries due to stainless steel’s corrosion resistance, hygiene, and durability.
- Increasing adoption of automation and smart monitoring systems in storage solutions, along with a shift toward recyclable materials, is shaping current market trends.
- Key players such as Paul Mueller Company, CST Industries, and Pfaudler Inc. dominate through product customization and global supply capabilities; vertical tanks and the 5,000–50,000 liters capacity segment lead the market with highest shares.
- Asia Pacific holds the largest regional share at 35.8%, followed by Europe (27.7%) and North America (19.9%); however, high initial investment costs and raw material price volatility pose notable restraints.
Market Segmentation Analysis:
By Type
The stainless-steel tank market is segmented into vertical and horizontal tanks. Vertical stainless-steel tanks held the dominant market share in 2024, accounting for over 60% of the total market. Their higher storage efficiency and space-saving design make them preferable in industries with space constraints, such as food processing and pharmaceuticals. Moreover, their ease of cleaning and superior pressure-handling capability drive their adoption in hygiene-critical applications. Horizontal tanks, although growing steadily, are primarily used in transport and temporary storage, where mobility and installation ease are more critical than capacity or space utilization.
- For instance, Paul Mueller Company manufactures vertical milk storage tanks with a holding pressure capacity of up to 30 psi and storage volume reaching 113,560 liters, tailored for dairy processors with limited floor space.
By Capacity
Among capacity-based segments, the 5,000–50,000 liters range emerged as the dominant sub-segment in 2024, holding around 42% of the market share. This capacity range offers a balanced combination of storage volume and operational flexibility, making it suitable for mid- to large-scale processing facilities in the food, beverage, and water treatment industries. Increased industrialization and the expansion of manufacturing facilities globally have fueled demand in this range. Tanks with capacities above 50,000 liters are gaining traction in heavy-duty sectors such as chemicals and wastewater treatment due to their large-scale storage capabilities, but remain niche in comparison.
- For instance, CST Industries has installed over 350,000 epoxy-coated and stainless steel tanks globally, with capacities ranging between 5,000 to 100,000 liters for water and wastewater treatment systems.
By Application
The food and beverage segment led the application category in 2024, capturing nearly 35% of the market share. The dominance is attributed to stringent hygiene standards, the need for corrosion resistance, and demand for long-lasting storage solutions in dairy, brewing, and food processing industries. Stainless-steel's inert properties and compliance with FDA and EU food-grade standards make it the preferred material in this sector. The pharmaceutical and chemical segments also show significant growth due to increasing investments in cleanroom manufacturing and chemical processing, respectively. Water and wastewater applications are expected to grow with rising infrastructure upgrades and environmental regulations.
Market Overview
Rising Demand from Food and Beverage Processing
The increasing need for sanitary and durable storage solutions in the food and beverage industry significantly drives the stainless-steel tank market. These tanks are preferred for their non-reactive properties, corrosion resistance, and compliance with food-grade safety standards. As global demand for processed food and beverages continues to rise, manufacturers are investing in hygienic storage and mixing equipment. The dairy, brewery, and edible oil sectors especially rely on stainless-steel tanks for preserving product quality, contributing to consistent growth in this application segment.
- For instance, Ziemann Holvrieka supplied a brewery tank installation with over 96 stainless steel fermentation and storage tanks, each with 5,000–60,000 liters capacity, to Heineken’s Mexico plant to support hygienic beer processing.
Expansion of Water and Wastewater Infrastructure
Rapid urbanization and growing concerns over water scarcity are prompting significant investments in water and wastewater treatment infrastructure globally. Stainless-steel tanks are crucial components in these systems due to their resistance to rust and microbial contamination. Their long service life and ability to handle varying pH levels make them ideal for municipal and industrial treatment plants. Government initiatives and environmental regulations mandating sustainable water management are further fueling demand, particularly in emerging economies undergoing infrastructure modernization.
- For instance, Permastore Limited has supplied over 300,000 stainless steel and glass-fused-to-steel tanks to wastewater and potable water projects worldwide, with individual installations exceeding 70,000 liters in high-load chemical environments.
Pharmaceutical and Chemical Industry Growth
The stainless-steel tank market benefits from the expansion of pharmaceutical and chemical manufacturing. These industries require tanks that ensure contamination-free storage and can withstand corrosive substances and temperature fluctuations. The increasing production of specialty chemicals and biopharmaceuticals, coupled with stringent regulatory standards, has led to a greater reliance on high-grade stainless-steel tanks. Additionally, the growing demand for large-scale batch processing and cleanroom facilities in drug manufacturing continues to propel market growth in this segment.
Key Trends and Opportunities
Integration of Automation and Smart Monitoring
The adoption of Industry 4.0 technologies is transforming stainless-steel tank operations. Smart tanks equipped with sensors and automation systems are gaining popularity across sectors, allowing real-time monitoring of temperature, pressure, and fill levels. This trend enhances operational efficiency, reduces human error, and supports preventive maintenance. Industries such as pharmaceuticals and food processing increasingly invest in these technologies to meet strict quality and safety standards, offering lucrative opportunities for tank manufacturers who integrate advanced control systems into their product offerings.
- For instance, Pfaudler Inc. integrated its glass-lined stainless-steel reactors with DeltaV™ automation systems from Emerson, enabling real-time data acquisition on pressure and temperature across 256 monitored points, reducing batch process variability by 27% in pharmaceutical manufacturing.
Shift Towards Sustainable and Recyclable Materials
Sustainability trends are driving demand for environmentally responsible manufacturing practices. Stainless steel, being 100% recyclable, aligns well with green initiatives across industries. Companies are actively replacing plastic and other non-durable materials with stainless-steel for its longevity and eco-friendly profile. The circular economy movement and green building codes are creating additional opportunities for stainless-steel tanks, especially in applications where sustainability certifications are required. This trend is expected to strengthen further as corporate ESG commitments and regulatory pressures increase globally.
- For instance, Paul Mueller Company reported that over 8,700 metric tons of stainless steel used in its manufacturing operations in 2023 were sourced from recycled materials, contributing to an annual reduction of 11,500 metric tons of CO₂ emissions across its food and beverage tank lines.
Key Challenges
High Initial Capital Investment
One of the key barriers to widespread adoption of stainless-steel tanks is the high upfront cost. Compared to alternative materials such as plastic or mild steel, stainless-steel tanks involve greater material and fabrication expenses. Small and medium enterprises, particularly in developing markets, often find it challenging to invest in these tanks despite their long-term benefits. This cost sensitivity can limit market penetration in cost-conscious sectors or regions with limited capital expenditure capabilities.
Volatility in Raw Material Prices
Fluctuations in the prices of stainless-steel and related alloys pose a significant challenge to manufacturers and end users. Factors such as global supply disruptions, geopolitical tensions, and shifts in demand for nickel and chromium impact pricing. This volatility not only affects production costs but also complicates long-term procurement planning and contract negotiations. The uncertainty may lead some customers to defer investments or consider alternative materials, thus impeding consistent market growth.
Maintenance Complexity in Harsh Environments
While stainless-steel tanks are known for their durability, certain challenging environments-such as highly acidic chemical processing or extreme temperature conditions-can accelerate wear and tear. Specialized coatings or alloys are required in these scenarios, which adds complexity and cost to maintenance and customization. Failure to apply the right material grade can lead to corrosion or contamination risks, particularly in critical applications. This challenge necessitates careful material selection and increases the technical burden on both manufacturers and end users.
Regional Analysis
North America
North America accounted for approximately 19.9% of the global stainless-steel tank market in 2024, with a market value of USD 635.08 million, rising from USD 489.12 million in 2018. The market is projected to reach USD 909.31 million by 2032, growing at a CAGR of 4.6% during the forecast period. The region’s growth is driven by robust demand in food processing, beverage manufacturing, and pharmaceutical sectors, supported by stringent hygiene and quality standards. The U.S. dominates the regional market due to large-scale industrialization and ongoing investments in modernizing storage and processing infrastructure.
Europe
Europe held a significant 27.7% share of the global stainless-steel tank market in 2024, with its value increasing from USD 672.27 million in 2018 to USD 886.15 million in 2024. The market is forecasted to reach USD 1,296.66 million by 2032, registering a CAGR of 4.9%. Growth is largely attributed to the presence of well-established food, beverage, and pharmaceutical industries across Germany, France, and the U.K. Environmental regulations and a growing preference for sustainable and recyclable storage solutions also support market expansion. The region continues to invest in clean manufacturing and industrial automation, bolstering demand.
Asia Pacific
Asia Pacific dominated the global stainless-steel tank market in 2024 with a commanding 35.8% share, valued at USD 1,144.39 million, up from USD 809.51 million in 2018. The market is expected to grow at a robust CAGR of 6.1%, reaching USD 1,834.59 million by 2032. Rapid industrialization, urbanization, and rising investments in food processing, water treatment, and pharmaceuticals are key drivers. China, India, and Japan are major contributors, supported by favorable government policies and expanding manufacturing infrastructure. The need for durable, corrosion-resistant storage solutions in a variety of industries is further propelling growth in the region.
Latin America
Latin America held a modest 9.7% share of the stainless-steel tank market in 2024, with its size growing from USD 228.35 million in 2018 to USD 310.37 million. It is projected to reach USD 473.54 million by 2032, reflecting a healthy CAGR of 5.4%. The region’s growth is primarily driven by increasing demand from the food and beverage sector, particularly in Brazil, Argentina, and Mexico. Rising investments in infrastructure and water treatment facilities also contribute to market expansion. The shift toward higher quality and durable storage solutions is encouraging the replacement of traditional tank materials with stainless steel.
Middle East
The Middle East stainless-steel tank market accounted for 4.2% of global share in 2024, valued at USD 135.27 million, up from USD 100.09 million in 2018. It is anticipated to grow at a CAGR of 5.3%, reaching USD 204.81 million by 2032. Growth is fueled by increasing investments in water desalination, oil & gas storage, and industrial processing facilities. Countries such as the UAE and Saudi Arabia are enhancing their manufacturing base and infrastructure, contributing to rising demand for corrosion-resistant and hygienic storage solutions. Additionally, the region’s focus on sustainable water management supports further market expansion.
Africa
Africa represented the smallest regional market share at 3.1% in 2024, with a market size of USD 86.52 million, up from USD 66.97 million in 2018. It is expected to reach USD 122.98 million by 2032, growing at a CAGR of 4.5%. The region is gradually witnessing growth in industrialization and infrastructure development, which in turn drives demand for stainless-steel tanks in sectors like water treatment and food processing. While limited by budget constraints and slow adoption of advanced equipment, international aid and foreign investment in utilities and health infrastructure are providing opportunities for gradual market growth.
Market Segmentations:
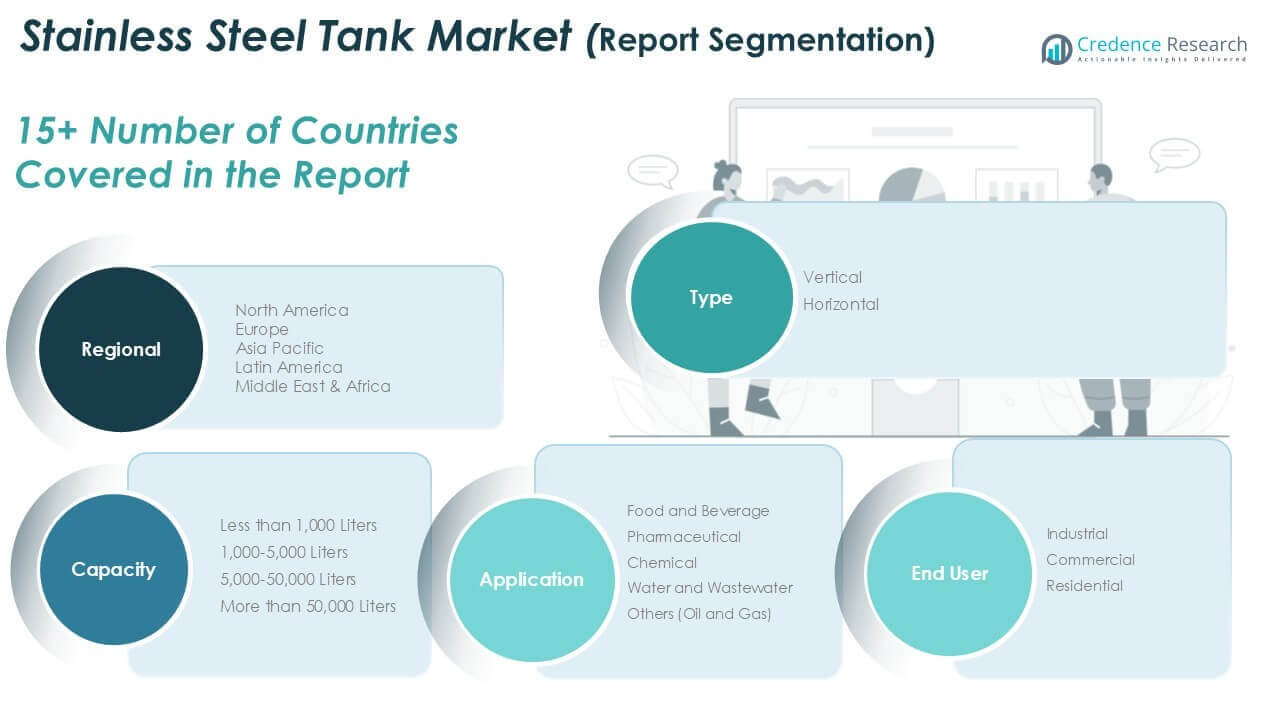
By Type
- Vertical
- Horizontal
By Capacity
- Less than 1,000 Liters
- 1,000–5,000 Liters
- 5,000–50,000 Liters
- More than 50,000 Liters
By Application
- Food and Beverage
- Pharmaceutical
- Chemical
- Water and Wastewater
- Others
By End-User Industry
- Residential
- Commercial
- Industrial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The stainless-steel tank market features a moderately fragmented competitive landscape, with key players focusing on innovation, capacity expansion, and customized solutions to strengthen their market positions. Leading companies such as Paul Mueller Company, Highland Tank & Manufacturing Company, CST Industries, and Pfaudler Inc. dominate the global market by offering a wide range of products tailored to specific industry needs, including food processing, pharmaceuticals, water treatment, and chemicals. These players emphasize stainless steel’s corrosion resistance, hygiene compliance, and durability to meet stringent regulatory standards across regions. Strategic collaborations, mergers, and investments in advanced manufacturing technologies-such as automated welding and smart monitoring systems-are increasingly common to enhance product quality and production efficiency. Additionally, regional players like MEKRO Sp. z o.o. and Kennedy Tank & Manufacturing Co. are expanding their footprint through localized offerings and flexible design capabilities. The competitive focus remains on innovation, cost-effectiveness, and sustainability to address evolving industrial demands and regulatory expectations.
Key Player Analysis
- Paul Mueller Company
- Caldwell Tanks
- Highland Tank & Manufacturing Company
- MEKRO Sp. z o.o.
- CST Industries, Inc.
- Permastore Limited
- Tank Connection
- Superior Tank Co., Inc.
- Schumann Tank
- Wheeler Tank Manufacturing, Inc.
- Hanson Tank
- Pfaudler, Inc.
- Rexarc International, Inc.
- Buckeye Fabricating Company
- Bendel Tank & Heat Exchanger
- Kennedy Tank & Manufacturing Co., Inc.
- Southern Tank & Manufacturing, Inc.
- Custom Metalcraft, Inc.
- Precision Tank, Inc.
- Highland Equipment Inc.
Recent Developments
- In July 2025, Highland Tank introduced the High-DRO® stainless-steel water storage tanks designed for potable water, fire protection, wastewater, and rainwater storage. These tanks feature rugged construction, corrosion resistance, and compliance with national codes. They also integrated High-LINK® electronic management systems for real-time data monitoring and optimized liquid operations.
- In April 2025, Bendel Tank & Heat Exchanger continues to specialize in the design and fabrication of custom stainless-steel tanks and pressure vessels, including ASME code vessels, with a focus on high-quality fabrication and custom solutions. They have over 60 years of experience in the field. They also offer value-added engineering and drafting services for pressure vessels, reactors, heat exchangers, storage tanks, and other custom-designed process equipment.
- In January 2025, Permastore introduced stainless-steel tanks designed with advanced CAD principles and high-quality welding practices adhering to ISO standards. The tanks are engineered to resist bimetallic corrosion through innovative design and protective coatings, ensuring long-lasting durability.
Market Concentration & Characteristics
The Stainless-Steel Tank Market exhibits moderate market concentration, with several well-established players holding significant shares while numerous regional manufacturers compete in niche and localized segments. It demonstrates a blend of standardized and highly customized product offerings, shaped by application-specific demands across industries such as food and beverage, pharmaceuticals, chemicals, and water treatment. The market remains quality-driven, where compliance with hygiene standards, corrosion resistance, and durability play a critical role in purchase decisions. Innovation in tank design, integration of automation, and adoption of recyclable materials characterize the competitive landscape. It reflects a strong emphasis on long-term value, operational safety, and regulatory adherence. Companies with advanced manufacturing capabilities and industry certifications continue to lead, while smaller firms focus on cost-effective solutions and local supply advantages. Demand patterns vary regionally, with Asia Pacific showing high growth momentum and mature markets in Europe and North America maintaining steady demand through equipment upgrades and regulatory compliance requirements.
Report Coverage
The research report offers an in-depth analysis based on Type, Capacity, Application, End-User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue expanding due to rising demand for hygienic and durable storage solutions in food and beverage processing.
- Pharmaceutical and biopharma industries will drive steady growth through investments in contamination-free storage systems.
- Adoption of automated and smart monitoring technologies will enhance operational efficiency and safety.
- Asia Pacific will maintain its dominance with rapid industrialization and infrastructure development.
- Demand for large-capacity tanks will increase in water treatment and chemical processing applications.
- Sustainable manufacturing practices and recyclable materials will gain priority among manufacturers.
- Customized and application-specific tank designs will see higher demand from specialized industries.
- Technological advancements in welding and fabrication will improve product quality and cost-effectiveness.
- Replacement of traditional materials with stainless-steel will grow in sectors prioritizing durability.
- Regulatory compliance and industry certifications will remain crucial for market competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Hygiene and Safety Standards in Food & Beverage
The food and beverage industry requires storage solutions that meet rigorous hygiene and safety regulations. Stainless-steel tanks are preferred for their corrosion resistance, ease of cleaning, and compliance with FDA and EU food-grade standards, driving their adoption in this sector.
Expansion of Water and Wastewater Infrastructure
Rapid urbanization and increasing investments in water and wastewater treatment facilities globally are boosting demand for stainless-steel tanks, which offer durability, resistance to rust, and suitability for handling varying pH levels in municipal and industrial applications.
Growth in Pharmaceutical and Chemical Manufacturing
The need for contamination-free, corrosion-resistant storage in pharmaceutical and chemical industries is fueling demand for high-grade stainless-steel tanks. Stringent regulatory requirements and the expansion of cleanroom and specialty chemical production further support market growth.
Adoption of Automation and Smart Monitoring
Industry 4.0 trends are leading to the integration of sensors and automation in stainless-steel tanks, enabling real-time monitoring and preventive maintenance. This enhances operational efficiency and safety, making smart tanks increasingly attractive to end users.
Shift Toward Sustainable and Recyclable Materials
Sustainability initiatives and regulatory pressures are encouraging industries to replace less durable materials with stainless steel, which is 100% recyclable. This aligns with corporate ESG goals and green building codes, supporting long-term market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Stainless-Steel Tank Market?
What factors are driving the growth of the Stainless-Steel Tank Market?
What are some challenges faced by the Stainless-Steel Tank Market?
Who are the major players in the Stainless-Steel Tank Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Vertical
- 1.2.2 Horizontal
- 1.3 By Capacity
- 1.3.1 Less than 1,000 Liters
- 1.3.2 1,000–5,000 Liters
- 1.3.3 5,000–50,000 Liters
- 1.3.4 More than 50,000 Liters
- 1.4 By Application
- 1.4.1 Food and Beverage
- 1.4.2 Pharmaceutical
- 1.4.3 Chemical
- 1.4.4 Water and Wastewater
- 1.4.5 Others
- 1.5 By End-User Industry
- 1.5.1 Residential
- 1.5.2 Commercial
- 1.5.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,197.8 million → 2032: USD 4,841.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Stainless Steel Tank Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Stainless Steel Tank Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Stainless Steel Tank Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Stainless Steel Tank Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Stainless Steel Tank Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Stainless Steel Tank Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Stainless Steel Tank Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Stainless Steel Tank Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,197.8 million → 2032: USD 4,841.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Stainless Steel Tank Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Vertical
- 12.3.7.2 Horizontal
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Capacity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Less than 1,000 Liters
- 12.4.7.2 1,000–5,000 Liters
- 12.4.7.3 5,000–50,000 Liters
- 12.4.7.4 More than 50,000 Liters
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverage
- 12.5.7.2 Pharmaceutical
- 12.5.7.3 Chemical
- 12.5.7.4 Water and Wastewater
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Residential
- 12.6.7.2 Commercial
- 12.6.7.3 Industrial
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Stainless Steel Tank End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Stainless Steel Tank Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Stainless Steel Tank Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Stainless Steel Tank Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Paul Mueller Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CST Industries, Inc.
- 18.4 Pfaudler, Inc.
- 18.5 Highland Tank & Manufacturing Company
- 18.6 Tank Connection
- 18.7 Permastore Limited
- 18.8 MEKRO Sp. z o.o.
- 18.9 Kennedy Tank & Manufacturing Co., Inc.
- 18.10 Bendel Tank & Heat Exchanger
- 18.11 Superior Tank Co., Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

