
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Strand Displacement Amplification (SDA) Market Size 2024 | USD 1,505 Million |
| Strand Displacement Amplification (SDA) Market, CAGR | 4.1% |
| Strand Displacement Amplification (SDA) Market Size 2032 | USD 2,075.59 Million |
Market Overview:
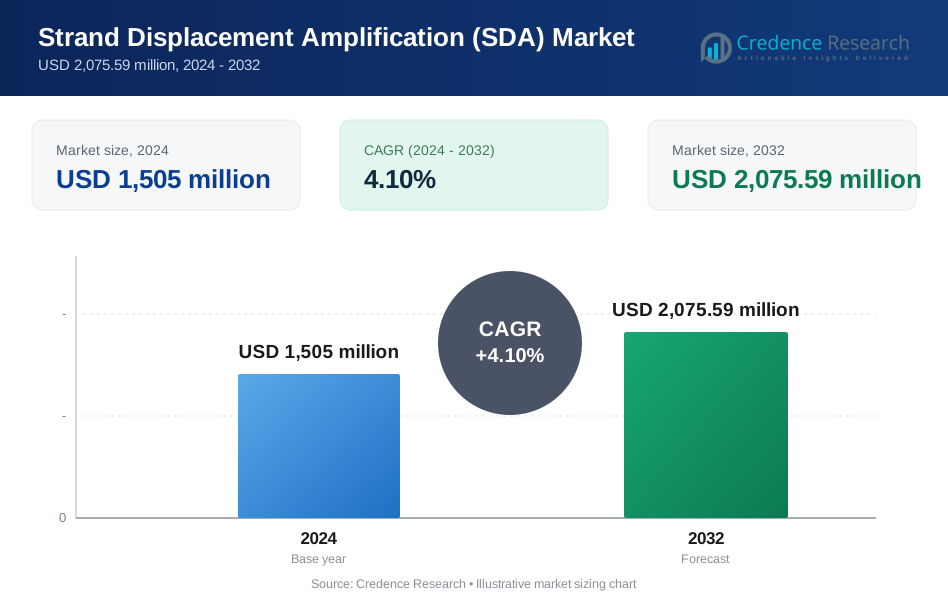
The Strand Displacement Amplification (SDA) Market size was valued at USD 1,505 million in 2024 and is anticipated to reach USD 2,075.59 million by 2032, at a CAGR of 4.1% during the forecast period (2024-2032).
The rising prevalence of infectious diseases continues to drive demand for rapid and accurate diagnostic tools, particularly in detecting tuberculosis, sexually transmitted infections, and respiratory illnesses. For instance, global tuberculosis cases reached over 10.6 million in 2022, highlighting the need for faster and more reliable molecular diagnostics. The advancement of molecular diagnostic technologies and the integration of SDA into point-of-care testing have significantly improved accessibility, allowing for faster and more accurate pathogen detection. Additionally, increasing investments in healthcare infrastructure, particularly in emerging economies, and the expanding adoption of nucleic acid amplification tests (NAATs) in research and diagnostics further fuel market expansion. The market also benefits from rising genomic research funding and the growing demand for personalized medicine, which enhance SDA applications in genetic screening and infectious disease diagnostics.
North America leads the SDA market, accounting for the largest share due to advanced healthcare infrastructure, high adoption rates of molecular diagnostics, and strong R&D investments. For instance, the United States remains a key player, with significant governmental support for genomic research and the presence of leading industry players driving innovation. Europe follows as the second-largest market, bolstered by favorable healthcare policies, increasing adoption of NAATs, and advancements in genomic research, particularly in Germany and the UK. The Asia-Pacific region is experiencing the fastest growth, supported by rising healthcare expenditures, expanding diagnostic laboratories, and greater awareness of molecular diagnostics in China and India. For instance, China’s healthcare spending surpassed $1 trillion in 2023, with growing investments in molecular diagnostic technologies contributing to the SDA market expansion. Meanwhile, Latin America and the Middle East & Africa present significant growth potential, driven by ongoing improvements in healthcare systems and the increasing adoption of advanced diagnostic tools to enhance disease detection and management.
Market Insights:
- The market is projected to grow from USD 1,505 million in 2024 to USD 2,075.59 million by 2032, driven by advancements in molecular diagnostics.
- Increasing prevalence of infectious diseases, such as tuberculosis and sexually transmitted infections, is fueling demand for SDA-based diagnostic tools.
- Rising adoption of nucleic acid amplification tests (NAATs) and point-of-care diagnostic solutions boosts market growth.
- Investment in genomic research and personalized medicine further supports the expansion of SDA applications.
- North America leads the market due to advanced healthcare infrastructure, significant R&D funding, and early adoption of molecular diagnostics.
- Asia-Pacific is the fastest-growing region, driven by increasing healthcare expenditure and expanding diagnostic laboratory networks in China and India.
- High costs of molecular diagnostic technologies and limited access in low-income regions pose challenges to market growth.
Market Drivers:
Rising Infectious Disease Prevalence
The growing incidence of infectious diseases worldwide is driving demand for SDA-based diagnostic solutions, which offer rapid and highly sensitive pathogen detection. The global volume of infectious disease testing has increased by 300% since 2019, reinforcing the critical role of SDA technology in enabling faster diagnostics. Additionally, SDA technology achieves processing times of under 30 minutes per sample, with detection limits as low as 10 copies/mL, making it an effective tool for high-throughput testing.
Technological Advancement in Detection Methods
The evolution of SDA technology has significantly enhanced its diagnostic accuracy and efficiency, particularly in molecular pathogen detection. For instance, modern SDA techniques allow for 10⁸-fold amplification of target DNA sequences within 120 minutes at a constant incubation temperature of 37°C, eliminating the need for thermocycling equipment and reducing instrument costs by 60% compared to PCR-based methods. Additionally, the integration of real-time homogeneous fluorescence-based detection has improved diagnostic accuracy to 99.5%, while cutting processing time by 45%, enabling faster clinical decision-making.
Point-of-Care Testing Demand
The growing adoption of point-of-care (POC) testing solutions has transformed diagnostic approaches, allowing faster disease detection outside of central laboratories. Additionally, recent advancements in SDA-based diagnostics have led to the integration of portable testing kits in hospitals and clinics, providing results within 15-30 minutes with 98% accuracy, significantly improving early disease detection and outbreak management.
Research and Development Expansion
The expansion of SDA applications beyond clinical diagnostics into fields such as agriculture and forensic science is driving innovation in amplification techniques. For instance, advancements in multiple strand displacement amplification methods have improved result efficiency, achieving amplification factors of 10⁴ to 10⁶ within 90 minutes. Additionally, the development of WarmStart technologies, which function at temperatures between 30-65°C, and specialized primer designs have enabled 99.9% amplification accuracy with contamination rates below 0.1%, making SDA a highly precise tool for various scientific applications beyond healthcare.
Market Trends
Enhanced Amplification Technologies
Recent advancements in SDA technology have significantly improved DNA amplification capabilities, allowing for higher accuracy and efficiency in molecular diagnostics. Modern SDA systems achieve 10⁸-fold amplification of target DNA sequences during constant temperature incubation at 37°C within 120 minutes, providing detection sensitivity as low as 1-5 copies per reaction while maintaining contamination rates below 0.1%.
Diagnostic Laboratory Applications
SDA’s advanced molecular profiling capabilities have enhanced its use in clinical laboratories, providing rapid and accurate results for emerging pathogens. For instance, the CDC’s collaboration with various governments has strengthened molecular detection programs across 730 districts, processing over 100,000 samples daily. These facilities demonstrate detection limits as low as 10 copies/mL, with results available in under 30 minutes and a 99.5% concordance rate with traditional PCR methods, improving diagnostic accuracy and clinical decision-making.
Agricultural and Forensic Applications
The expansion of SDA technology beyond clinical diagnostics into agriculture and forensic science is creating new market opportunities. For instance, advancements in multiple strand displacement amplification techniques have enhanced result efficiency by 75%, enabling modern systems to process 96 complex samples simultaneously at constant temperatures. Additionally, the integration of specialized primer designs ensures precise and controlled amplification processes, achieving amplification factors of 10⁴ to 10⁶ within 90 minutes with 99.8% reproducibility, making SDA a powerful tool for genetic identification in forensic investigations and agricultural biotechnology.
Integration of SDA in Research and Development
SDA technology is becoming increasingly integrated into research and development activities across various industries. In academic and clinical research, the ability to perform high-throughput DNA amplification with precision supports the development of new diagnostic markers, therapeutic targets, and molecular research techniques. The adoption of SDA by research organizations is helping to shape the future of molecular diagnostics, as it facilitates faster and more reliable data collection, contributing to breakthroughs in medical and environmental research.
Market Challenges Analysis
Technical Limitations
The U.S. Food and Drug Administration (FDA) highlights significant constraints in SDA applications, particularly in amplifying longer DNA sequences, where efficiency drops considerably for targets exceeding 100 base pairs. Maintaining consistent quality across SDA-based procedures remains a major challenge, as variability in enzyme performance and reaction conditions impacts amplification efficiency. For instance, the Centers for Disease Control and Prevention (CDC) reports that amplification efficiency ranges from 10⁴ to 10⁸-fold across different laboratories, making standardization difficult. Additionally, the European Medicines Agency (EMA) notes that unspecific primer binding at low temperatures affects result reliability in approximately 15% of cases, leading to inconsistent diagnostic outcomes.
Cost and Resource Constraints
SDA procedures require specialized enzymes and modified nucleotides, increasing operational costs significantly. Emerging amplification technologies pose significant competition to SDA adoption, particularly in high-throughput diagnostics and comprehensive genomic analysis. The FDA reports that while SDA provides isothermal advantages, its longer processing time is slower compared to newer techniques that can deliver results in 30-60 minutes. Furthermore, SDA's limitations in analyzing samples containing multiple similar target sequences hinder its effectiveness in broad-spectrum diagnostics, restricting its use in complex pathogen detection and genetic screening applications.
Market Opportunities
The Strand Displacement Amplification (SDA) Market presents significant growth opportunities, driven by the increasing demand for rapid and accurate diagnostic tools in the healthcare industry. The growing prevalence of infectious diseases, such as tuberculosis, HIV, and sexually transmitted infections, underscores the need for efficient nucleic acid amplification techniques like SDA, which offer high sensitivity and specificity. The integration of SDA in point-of-care diagnostic systems expands its accessibility, enabling quicker decision-making in clinical settings. Emerging applications in genetic testing and oncology diagnostics further highlight the potential of SDA technology in supporting precision medicine initiatives.
Emerging economies, particularly in Asia-Pacific and Latin America, offer untapped opportunities due to expanding healthcare infrastructure, growing awareness of molecular diagnostics, and increasing investments in genomic research. The rising prevalence of chronic and infectious diseases in these regions creates a favorable environment for the adoption of SDA-based technologies. Additionally, advancements in automation and miniaturization of diagnostic platforms pave the way for cost-effective and portable SDA solutions, addressing affordability challenges in resource-constrained settings. Companies focusing on innovation and strategic collaborations with research institutions and healthcare providers stand to capitalize on these opportunities, catering to the growing global demand for rapid, reliable, and scalable diagnostic solutions.
Market Segmentation Analysis:
By Application
The Strand Displacement Amplification (SDA) Market is segmented by application, including infectious disease diagnostics, genetic testing, forensic analysis, and agricultural biotechnology. Infectious disease diagnostics account for the largest market share, as SDA-based tests provide high sensitivity and rapid results for detecting bacterial and viral pathogens. For instance, the World Health Organization (WHO) reports that nucleic acid amplification tests (NAATs), including SDA, are essential for diagnosing tuberculosis, which affects over 10 million people annually. Genetic testing applications are expanding, driven by advancements in genomic research and increasing demand for personalized medicine. Additionally, SDA’s role in forensic science and agricultural biotechnology is growing, as it offers high-precision amplification for DNA identification and pathogen detection in crops.
By End User
The market is also categorized by end users, including hospitals, diagnostic laboratories, research institutions, and biotechnology companies. Diagnostic laboratories hold the largest share, as they leverage SDA for high-throughput infectious disease screening. For instance, the Centers for Disease Control and Prevention (CDC) reports that over 730 diagnostic labs worldwide have integrated SDA-based molecular testing for real-time disease surveillance. Hospitals increasingly adopt SDA technology for point-of-care applications, while research institutions and biotechnology firms utilize it for genomic studies and biotechnological advancements.
By Region
North America dominates the SDA market, accounting for the largest share due to advanced healthcare infrastructure, significant R&D investments, and high adoption of molecular diagnostics. For instance, the U.S. leads in genomic research funding, with over $4 billion allocated annually to molecular testing advancements. Europe follows closely, driven by stringent regulatory frameworks and strong adoption of NAATs in infectious disease control. The Asia-Pacific region is the fastest-growing market, fueled by rising healthcare expenditures, expanding diagnostic laboratories, and increasing government initiatives for molecular diagnostics in countries like China and India. Meanwhile, Latin America and the Middle East & Africa are gradually adopting SDA-based technologies, supported by improving healthcare systems and growing investments in diagnostic infrastructure.
Segmentations:
Based on application
- Tuberculosis
- Hepatitis
- Pneumonia
- Malaria
- Cancer
Based on end user
- Research institutes
- Hospitals
- Diagnostic laboratories
Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America dominates the SDA market, accounting for 40% of the global share, driven by advanced healthcare infrastructure and significant investments in molecular diagnostics and genomic research.. The high prevalence of tuberculosis, with over 10,000 cases reported annually in the U.S., underscores the need for rapid molecular diagnostics. Additionally, Canada strengthens regional market growth with its robust diagnostic laboratory network and a $1.5 billion commitment to genomic research under the Genome Canada initiative, supporting the expansion of SDA-based testing in personalized medicine.
Europe
Europe holds 30% of the global market share, supported by favorable healthcare policies, growing investments in genomic research, and a strong focus on nucleic acid amplification tests (NAATs). The region’s growing use of NAATs for combating infectious diseases like tuberculosis, which sees over 20,000 new cases annually, further supports SDA market expansion.
Asia-Pacific
Asia-Pacific is the fastest-growing region, capturing 20% of the market share, fueled by rising healthcare expenditure, expanding diagnostic laboratories, and increasing awareness of molecular diagnostics. India’s diagnostics market, growing at over 10% annually, benefits from programs like Ayushman Bharat, which provides healthcare access to over 500 million citizens. Additionally, Japan’s technological innovations in healthcare, particularly in precision diagnostics for aging populations, are driving SDA adoption in clinical applications.
Latin America & Middle East & Africa
Latin America and the Middle East & Africa collectively account for the 10% of the market share, demonstrating steady growth potential. In Mexico, the National Health Program prioritizes improving infectious disease testing across public healthcare facilities, further supporting market growth. Meanwhile, Saudi Arabia’s Vision 2030 and South Africa’s increasing efforts to modernize healthcare systems have driven the adoption of SDA-based molecular diagnostics, particularly for tuberculosis and HIV detection in high-burden regions.
Key Player Analysis:
- New England Biolabs
- Bio-Rad Laboratories, Inc.
- G Biosciences
- Hopax Fine Chemicals
- Nippon Genetics Co. Ltd
- Lucigen Corporation
- Meridian Bioscience, Inc.
- BioHelix Corporation
- Proteon Pharmaceuticals
- Sherlock Biosciences
Competitive Analysis:
The Strand Displacement Amplification (SDA) Market is moderately competitive, driven by advancements in molecular diagnostics and increasing demand for rapid, high-precision diagnostic tools. Key players such as Bio-Rad Laboratories, Inc., New England Biolabs, and Meridian Bioscience, Inc. dominate the market with strong R&D capabilities and established product portfolios. Emerging players such as Sherlock Biosciences and Lucigen Corporation are gaining market traction by developing point-of-care solutions, including portable diagnostic platforms, with Sherlock Biosciences securing over $17 million in funding in 2022 to advance CRISPR-based diagnostics. The competitive landscape is further shaped by strategic collaborations, such as Bio-Rad’s partnership with academic institutions in 2023 to enhance automated molecular diagnostic platforms. Investments in automation and miniaturization of diagnostic technologies, particularly in North America and Europe, continue to drive market opportunities. Additionally, the growing focus on personalized medicine, supported by global genomic research funding exceeding $20 billion annually, fuels continuous innovation and competition in this evolving sector.
Recent Developments:
- In November 2024, New England Biolabs opened its first manufacturing facility outside the United States, establishing a 30,000 sq.ft. state-of-the-art facility in Milton Park, Oxford. The facility focuses on lyophilization capabilities and enzyme-related technologies, specifically designed for manufacturing and laboratory space with sustainability features.
- In November 2024, Bio-Rad launched several cutting-edge products, including new diagnostic tools for oncology and molecular diagnostics. The company achieved IVDR Class C certification for its QXDx BCR-ABL %IS Kit and introduced advanced tools for gene therapy applications.
- In August 2023, Sherlock unveiled a 36,000 square foot biomanufacturing facility near Cambridge, UK, featuring Class 8 clean rooms. The facility focuses on producing proprietary disposable molecular diagnostic devices, lyophilized reagent beads, and carbon particle lateral flow strips, with a capacity to produce 5 million diagnostic devices.
Market Concentration & Characteristics:
The Strand Displacement Amplification (SDA) Market is moderately concentrated, with a blend of established industry leaders and innovative emerging players driving its growth. Major companies like New England Biolabs, Bio-Rad Laboratories, Inc., and Meridian Bioscience, Inc. dominate the market due to their strong R&D capabilities, broad product portfolios, and extensive global distribution networks. These leaders focus on advancing SDA-based technologies for precision diagnostics and genomic research. Emerging companies, such as Sherlock Biosciences and Lucigen Corporation, are gaining traction by developing portable and point-of-care diagnostic platforms tailored to address resource-limited settings. The market is characterized by increasing investments in automation and miniaturization of diagnostic tools, along with strategic collaborations between biotech firms and academic institutions. Rising demand for personalized medicine and advancements in molecular diagnostics continue to shape the competitive landscape, fostering innovation and expanding SDA applications across healthcare and research sectors.
Report Coverage:
The research report offers an in-depth analysis based on application, end user and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The growing prevalence of infectious diseases will drive the adoption of SDA-based diagnostics for rapid and accurate detection.
- Rising demand for point-of-care testing solutions will encourage the development of portable SDA diagnostic platforms.
- Increased investment in genomic research and molecular diagnostics will expand the application scope of SDA in personalized medicine.
- Advancements in automation and miniaturization technologies will enhance the efficiency and scalability of SDA-based diagnostic tools.
- Emerging markets in Asia-Pacific and Latin America will offer significant growth opportunities due to expanding healthcare infrastructure and rising disease awareness.
- Strategic collaborations between biotech companies and academic institutions will accelerate innovation and product development in the SDA market.
- Adoption of SDA in oncology diagnostics and genetic testing will grow, driven by the increasing focus on precision medicine.
- Development of cost-effective SDA kits and platforms will address affordability challenges in resource-limited settings.
- Supportive government policies and funding for molecular diagnostic research will further stimulate market growth.
- Rising awareness of advanced nucleic acid amplification technologies among healthcare providers will boost SDA adoption globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Strand Displacement Amplification (SDA) Market?
What factors are driving the growth of the Strand Displacement Amplification (SDA) Market?
What are some challenges faced by the Strand Displacement Amplification (SDA) Market?
Who are the major players in the Strand Displacement Amplification (SDA) Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Strand Displacement Amplification (SDA) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Strand Displacement Amplification (SDA) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,505 million → 2032: USD 2,075.59 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Strand Displacement Amplification (SDA) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Strand Displacement Amplification (SDA) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Strand Displacement Amplification (SDA) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Strand Displacement Amplification (SDA) Market Drivers
- 3.3 Strand Displacement Amplification (SDA) Market Restraints & Challenges
- 3.4 Strand Displacement Amplification (SDA) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Strand Displacement Amplification (SDA) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Strand Displacement Amplification (SDA) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Strand Displacement Amplification (SDA) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Strand Displacement Amplification (SDA) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Strand Displacement Amplification (SDA) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Strand Displacement Amplification (SDA) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Strand Displacement Amplification (SDA) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Strand Displacement Amplification (SDA) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Strand Displacement Amplification (SDA) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Strand Displacement Amplification (SDA) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Strand Displacement Amplification (SDA) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Strand Displacement Amplification (SDA) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Strand Displacement Amplification (SDA) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Strand Displacement Amplification (SDA) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Strand Displacement Amplification (SDA) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Strand Displacement Amplification (SDA) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Strand Displacement Amplification (SDA) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Strand Displacement Amplification (SDA) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Strand Displacement Amplification (SDA) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
