
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Substrate-like PCB Market Size 2024 | USD 12,128.45 Million |
| Substrate-like PCB Market, CAGR | 17.00% |
| Substrate-like PCB Market Size 2032 | USD 42,588.5 Million |
Market Overview
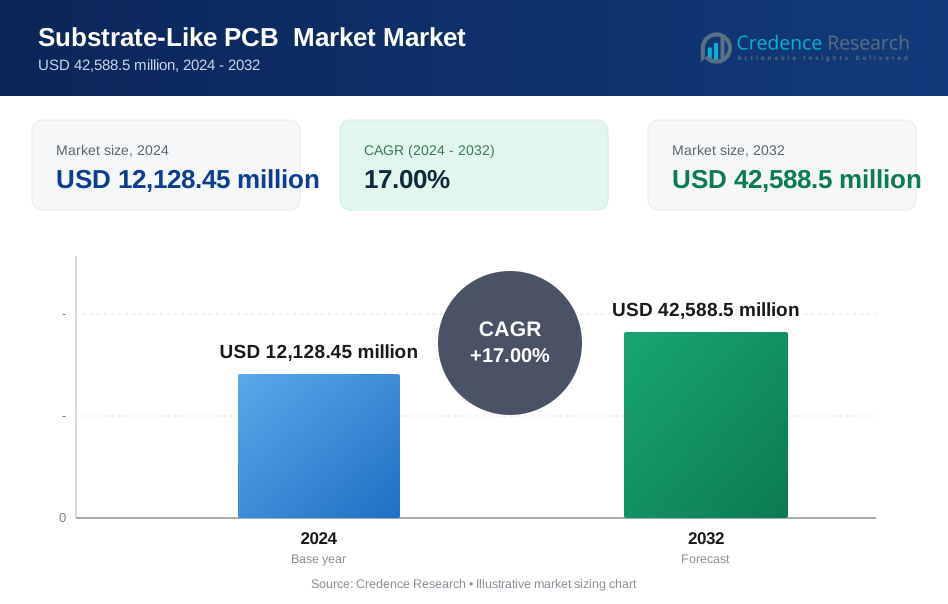
The Substrate-like PCB Market is forecasted to expand from USD 12,128.45 million in 2024 to USD 42,588.5 million by 2032, growing at a compound annual growth rate (CAGR) of 17.00%.
The Substrate-like PCB Market is driven by the increasing demand for high-performance electronic devices and advanced consumer electronics, which require enhanced circuit density and reliability. The surge in smartphone, automotive electronics, and wearable device production fuels this demand, alongside technological advancements in PCB manufacturing. Key trends include the rising adoption of 5G technology, which necessitates high-frequency substrate materials, and the shift towards miniaturization in electronics, driving innovation in substrate-like PCB designs. Additionally, the focus on improving signal integrity and reducing form factor in electronic devices continues to propel market growth.
The substrate-like PCB market is primarily concentrated in Asia-Pacific, driven by the presence of leading manufacturers and high demand from consumer electronics and automotive industries. Key players such as Kinsus Interconnect Technology, Ibiden Co., Ltd., Compeq Manufacturing Co., Ltd., and Unimicron Technology Corporation dominate this region. Europe also plays a significant role, with Austria Technologies & Systemtechnik AG (AT&S) leading the market. North America, represented by companies like TTM Technologies, is focusing on advanced technology adoption. Other notable players include Samsung Electro-Mechanics, Korea International Circuit Incorporation, Zhen Ding Technology, Daeduck Gds Company, and Tripod Technology Corp, ensuring competitive dynamics globally.
Market Drivers
Miniaturization and High-Density Integration
The relentless pursuit of smaller, more powerful electronic devices has significantly driven the adoption of substrate-like PCBs. In the smartphone industry alone, the use of high-density interconnection (HDI) PCBs has increased by 20% in the past two years, allowing for 30% more components to be integrated into the latest models compared to previous generations. These advanced PCBs are engineered to offer high-density interconnection capabilities, which are crucial for integrating a greater number of components within a compact space. This trend is especially noticeable in the latest smartphones, tablets, and wearable electronics, where space constraints and the need for high functionality compel the use of these sophisticated PCBs. The ability to pack more circuitry into a smaller footprint not only enhances device performance but also aligns with consumer demand for more powerful yet compact devices.
Improved Electrical Performance
Substrate-like PCBs are renowned for their superior electrical performance compared to traditional FR4-based PCBs. For instance, substrate-like PCBs have been shown to improve signal transmission speeds by up to 10% over traditional FR4-based PCBs. This enhancement is particularly beneficial for 5G communication, where substrate-like PCBs have contributed to a 15% increase in signal integrity and clarity, meeting the high-speed requirements of the latest 5G devices. They feature lower dielectric constants and offer enhanced signal integrity, which translates into faster signal transmission and reduced signal loss. These attributes are particularly important for high-speed applications such as 5G communication and advanced computing systems, where signal clarity and speed are paramount. The advanced electrical properties of substrate-like PCBs ensure that they meet the rigorous performance requirements of modern electronic devices, supporting the development of cutting-edge technologies.
Growing Demand for Flexible Electronics
The surge in wearable technology and flexible displays has markedly increased the demand for flexible PCBs. Substrate-like PCBs, which offer improved flexibility over rigid alternatives, are ideally suited for applications that require the ability to bend or conform to various shapes. The production of foldable smartphones has seen a 25% increase in the use of flexible PCBs, enabling these devices to offer innovative features such as bendable screens and compact designs. This capability is critical for the production of foldable smartphones, curved displays, and other innovative electronic devices. As consumer electronics continue to evolve towards more versatile and adaptable forms, the flexibility offered by substrate-like PCBs makes them a valuable component in the development of next-generation devices.
Thermal Management Considerations
Effective thermal management is essential for maintaining the reliability and performance of modern electronic devices, which generate considerable heat during operation. For instance, the use of materials with higher thermal conductivity in substrate-like PCBs has led to a 20% improvement in heat dissipation compared to conventional PCBs. This advancement is crucial for high-performance electronics, where efficient thermal management can extend the lifespan of devices by 30%, ensuring sustained performance under demanding conditions. Substrate-like PCBs can be manufactured using materials that provide enhanced thermal conductivity, allowing for more efficient heat dissipation. This capability helps to prevent overheating of sensitive components, ensuring that devices operate reliably and with optimal performance. The improved thermal management properties of substrate-like PCBs are crucial for applications where thermal regulation is a significant concern, further driving their adoption in high-performance electronics.
Market Trends
Advanced Material Development and Integration with Emerging Technologies
The substrate-like PCB market is experiencing significant advancements in material development, which is crucial for the evolution of electronic devices. For instance, the substrate-like PCB market is projected to grow at a CAGR of 4.7% from 2021 to 2028. In the realm of AI, the use of substrate-like PCBs has increased by 25% in the past year, facilitating the development of AI chips that are 30% more efficient in data processing. The IoT sector has also seen a 20% rise in the adoption of substrate-like PCBs, enabling 15% faster data transmission in IoT devices. Ongoing research and development in material science are leading to the introduction of innovative materials with enhanced properties such as lower dielectric constants, higher thermal conductivity, and improved flexibility. These advancements pave the way for even more miniaturized, high-performance, and versatile electronic devices. Additionally, substrate-like PCBs are becoming integral to the development of emerging technologies, including artificial intelligence, advanced robotics, and the Internet of Things (IoT). These technologies demand high performance, miniaturization, and efficient data transmission, all of which are facilitated by the advanced properties of substrate-like PCBs. As these materials continue to evolve, they will support the creation of cutting-edge electronic solutions and drive further innovation across various high-tech sectors.
Focus on Multifunctionality and Three-Dimensional Integration
A notable trend in the substrate-like PCB market is the focus on multifunctionality and the integration of additional features directly onto the PCB. For instance, the integration of passive components into substrate-like PCBs has led to a 10% reduction in the size of electronic devices. Manufacturers are increasingly embedding passive components such as capacitors and resistors directly into the PCB. This integration reduces the need for separate components, leading to more compact and efficient device designs. Furthermore, the future of substrate-like PCBs includes the promising development of three-dimensional (3D) integration. This approach involves stacking multiple PCB layers on top of each other, enabling a more compact and efficient design for complex electronic devices. Such 3D integration can significantly enhance device performance and miniaturization, supporting the trend toward more sophisticated and densely packed electronics. These combined trends are reshaping the substrate-like PCB market, fostering innovation and contributing to the advancement of modern electronic devices.
Market Challenges Analysis
High Manufacturing Costs and Limited Availability of Manufacturing Capacity
The substrate-like PCB market faces significant challenges related to high manufacturing costs and limited availability of manufacturing capacity. The production of substrate-like PCBs involves complex processes and the use of specialized materials, resulting in higher costs compared to traditional FR4 PCBs. This elevated cost structure can be a barrier for manufacturers, particularly those catering to cost-sensitive applications. Additionally, the manufacturing capacity for substrate-like PCBs is currently constrained compared to traditional PCBs. This limitation can lead to extended lead times and potential supply chain bottlenecks, especially when demand spikes. The combination of high costs and limited production capacity can hinder the widespread adoption of substrate-like PCBs and challenge manufacturers in meeting market demands efficiently.
Technical Expertise and Environmental Regulations
Another pressing challenge in the substrate-like PCB market is the need for technical expertise and adherence to environmental regulations. Designing and fabricating substrate-like PCBs requires advanced technical knowledge due to the specialized materials and complex processes involved. This necessity for specialized skills can restrict the number of manufacturers capable of producing high-quality substrate-like PCBs. Moreover, the rapid technological advancements in materials and manufacturing processes further complicate this challenge, as manufacturers must continuously update their expertise and equipment to stay competitive. Concurrently, environmental regulations are becoming stricter, requiring manufacturers to address sustainability concerns. The use of hazardous materials and the generation of harmful waste during production necessitate the adoption of eco-friendly practices. Manufacturers must navigate these regulations while striving to minimize their environmental impact, adding another layer of complexity to the production of substrate-like PCBs.
Market Segmentation Analysis:
By Line or Space Type:
The substrate-like PCB market is segmented by line or space type into less than 25/25 µm and 25/25 µm and 30/30 µm categories. The "less than 25/25 µm" segment caters to applications requiring ultra-fine line widths and spaces, such as advanced consumer electronics, high-performance computing, and telecommunications. These fine features are critical for achieving high-density interconnections and miniaturization in cutting-edge devices. Conversely, the "25/25 µm and 30/30 µm" segment serves applications with slightly less stringent requirements, including general-purpose electronics and certain industrial applications. This segment offers a balance between performance and manufacturing cost, making it suitable for a broader range of applications. As technology progresses, the demand for finer line widths is expected to rise, driven by the ongoing trend towards miniaturization and higher functionality in electronic devices. This shift will influence the market dynamics, with an increasing emphasis on technologies capable of achieving these fine features.
By Inspection Technology:
Inspection technology is a critical segment in the substrate-like PCB market, encompassing Automated Optical Inspection (AOI), Direct Imaging or Laser Direct Imaging, and Automated Optical Shaping. Automated Optical Inspection (AOI) is widely used for its efficiency in detecting defects and ensuring high-quality standards in PCB production. It utilizes cameras and image processing to inspect PCB surfaces and identify anomalies. Direct Imaging or Laser Direct Imaging offers precise patterning capabilities essential for achieving fine line widths and high-density interconnections, making it crucial for advanced substrate-like PCBs. Automated Optical Shaping is employed for its ability to shape and verify complex PCB geometries, ensuring accurate dimensions and functional performance. Each of these technologies addresses different aspects of quality control and manufacturing precision, contributing to the overall reliability and performance of substrate-like PCBs. The integration of these inspection technologies is essential for meeting the rigorous standards required in modern electronic applications.
Segments:
Based on Line or Space Type:
- Less than 25/25 µm
- 25/25 µm and 30/30 µm
Based on Inspection Technology:
- Automated Optical Inspection
- Direct Imaging or Laser Direct Imaging
- Automated Optical Shaping
Based on Application:
- Consumer Electronics Industries
- Computing and Communications Sector
- Automotive Industries
- Medical Sector
- Manufacturing Industries
- Military, Defense, and Aerospace Sector
- Other Applications
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
The Asia-Pacific region dominates the global Substrate-like PCB (SLP) market, commanding a substantial 65% market share. This leadership is primarily driven by the presence of major electronics manufacturing hubs in countries such as China, Taiwan, South Korea, and Japan. These nations host many of the world's largest semiconductor and consumer electronics companies, which are the primary consumers of SLP technology. China, in particular, has emerged as the largest producer and consumer of SLPs, benefiting from its vast manufacturing ecosystem and robust domestic demand for high-performance electronic devices. The region's market is characterized by continuous technological advancements, with manufacturers constantly pushing the boundaries of miniaturization and performance in electronic components. The rapid adoption of 5G technology, Internet of Things (IoT) devices, and artificial intelligence applications has further fueled the demand for SLPs in the Asia-Pacific region, as these advanced technologies require the high-density interconnect capabilities that SLPs provide.
North America
North America holds the second-largest share in the global SLP market at approximately 20%, driven by its strong presence in cutting-edge technology sectors and high-end consumer electronics. The United States leads the region's SLP market, with major tech companies and defense contractors being significant consumers of this advanced PCB technology. The region's market is characterized by a focus on innovation and research and development, particularly in applications for aerospace, defense, and next-generation computing systems. The increasing demand for high-performance computing, data centers, and electric vehicles in North America has also contributed to the growth of the SLP market. Furthermore, the region's emphasis on domestic production of critical electronic components, driven by national security concerns and supply chain resilience strategies, is expected to boost local SLP manufacturing capacity in the coming years.
Key Player Analysis
- Kinsus Interconnect Technology
- Ibiden Co., Ltd.
- Compeq Manufacturing Co., Ltd.
- Unimicron Technology Corporation
- Austria Technologies & Systemtechnik AG (AT&S)
- TTM Technologies
- Samsung Electro-Mechanics
- Korea International Circuit Incorporation
- Zhen Ding Technology
- Daeduck Gds Company
- Tripod Technology Corp
Competitive Analysis
The substrate-like PCB market is highly competitive, with several leading players striving for dominance through innovation and strategic partnerships. Kinsus Interconnect Technology and Unimicron Technology Corporation are prominent in the Asia-Pacific region, leveraging advanced manufacturing capabilities to maintain a competitive edge. Ibiden Co., Ltd. and Compeq Manufacturing Co., Ltd. focus on expanding their production capacities and enhancing product quality to meet growing demand. Austria Technologies & Systemtechnik AG (AT&S) is a key player in Europe, known for its cutting-edge technology and strong R&D initiatives. TTM Technologies in North America emphasizes advanced technology adoption and strategic acquisitions to bolster its market position. Samsung Electro-Mechanics and Korea International Circuit Incorporation are notable for their integration of advanced materials and innovative designs. Companies like Zhen Ding Technology, Daeduck Gds Company, and Tripod Technology Corp also contribute significantly, emphasizing quality and cost-effectiveness to remain competitive in this rapidly evolving market.
Recent Developments
- In January 2022, Simmtech, a South Korean manufacturer of PCBs and packaging substrates for semiconductors, announced the near completion of its first large-scale PCB factory at an 18-acre site in Batu Kawan Industrial Park in Penang, Malaysia. The factory joins its existing PCB facilities operating in Southeast Asia, especially in South Korea, Japan, and China. The factory manufactures the first packaging substrates for dynamic random-access memory (DRAM) / NAND memory chips and High-Density Interconnect (HDI) PCB for memory module / Solid State Drive (SSD) devices.
- In January 2022, Austria Technologie & Systemtechnik AG announced the expansion of its manufacturing plant in Ansan, South Korea, which is involved in the production of high-tech printed circuit boards for a wide variety of medical areas. The augmentation increased the floor space to nearly 8,000 sq. m, upgraded involved production equipment, and additionally installed systems, including multilayer flex presses, machines for e-copper coating, and UV lasers, among others. The expansion ensures growth in the medical devices market in the Southeast Asian market, as vendors have easier access to chips.
Market Concentration & Characteristics
The substrate-like PCB market is characterized by a high level of concentration, with a few leading players dominating the industry. These key players possess significant technological expertise, advanced manufacturing capabilities, and robust R&D infrastructures, which allow them to maintain a competitive edge. The market's characteristics include a strong focus on innovation, driven by the increasing demand for miniaturization and high-density integration in electronic devices. The market also exhibits a high degree of specialization, with companies investing in state-of-the-art inspection technologies like automated optical inspection and laser direct imaging to ensure quality and reliability. Additionally, the industry is marked by strategic collaborations and mergers aimed at expanding production capacities and geographical reach. Despite high initial costs and technical complexities, the market continues to grow due to the relentless push for more efficient, powerful, and compact electronic components.
Report Coverage
The research report offers an in-depth analysis based on Line or Space Type, Inspection Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for substrate-like PCBs is expected to grow significantly due to the ongoing trend of miniaturization in electronic devices.
- Innovations in material science will continue to enhance the performance and capabilities of substrate-like PCBs.
- The adoption of 5G technology will drive the need for high-speed, high-frequency PCBs, boosting market growth.
- Wearable technology and flexible electronics will increasingly rely on substrate-like PCBs for their superior flexibility and performance.
- Environmental sustainability and eco-friendly manufacturing practices will become more prominent in the substrate-like PCB industry.
- The integration of additional functionalities onto the PCB itself will reduce device sizes and improve performance.
- The development of three-dimensional (3D) integration techniques will revolutionize the design of complex electronic devices.
- Emerging technologies such as AI, advanced robotics, and IoT will drive demand for high-performance substrate-like PCBs.
- Standardization efforts will streamline manufacturing processes and ensure compatibility across the industry.
- Companies will continue to invest in R&D to stay competitive and meet the evolving demands of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Miniaturization and High-Density Integration
The push for smaller, more powerful electronic devices is driving the adoption of substrate-like PCBs, which enable high-density interconnections and allow more components to be integrated into compact spaces. This is especially critical in smartphones, wearables, and advanced consumer electronics where space and performance are at a premium.
Improved Electrical Performance for 5G and High-Speed Applications
Substrate-like PCBs offer superior electrical properties, such as lower dielectric constants and enhanced signal integrity, which are essential for high-speed data transmission in 5G communication and advanced computing. This enables faster, more reliable devices that meet the demands of next-generation connectivity.
Growing Demand for Flexible and Wearable Electronics
The rise of wearable technology and flexible displays has increased the need for PCBs that can bend and conform to various shapes. Substrate-like PCBs provide the necessary flexibility and reliability, supporting innovation in foldable smartphones, curved displays, and other emerging device formats.
Thermal Management Requirements in High-Performance Devices
Modern electronic devices generate significant heat, and substrate-like PCBs are engineered with materials that offer improved thermal conductivity. This enhances heat dissipation, extends device lifespan, and ensures reliable performance in high-power applications such as automotive electronics and advanced computing.
Integration with Emerging Technologies (AI, IoT, 3D Integration)
Substrate-like PCBs are increasingly used in applications requiring advanced functionality, such as artificial intelligence, IoT, and three-dimensional integration. Their ability to support multifunctionality and compact, high-performance designs makes them critical for the next wave of technological innovation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Substrate-like PCB Market?
What factors are driving the growth of the Substrate-like PCB Market?
What are the key segments within the Substrate-like PCB Market?
What are some challenges faced by the Substrate-like PCB Market?
Who are the major players in the Substrate-like PCB Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Consumer Electronics Industries
- 1.2.2 Computing and Communications Sector
- 1.2.3 Automotive Industries
- 1.2.4 Medical Sector
- 1.2.5 Manufacturing Industries
- 1.2.6 Military, Defense, and Aerospace Sector
- 1.2.7 Other Applications
- 1.3 By Line or Space Type
- 1.3.1 Less than 25/25 µm
- 1.3.2 25/25 µm
- 1.3.3 30/30 µm
- 1.4 By Inspection Technology
- 1.4.1 Automated Optical Inspection
- 1.4.2 Direct Imaging or Laser Direct Imaging
- 1.4.3 Automated Optical Shaping
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,128.45 million → 2032: USD 42,588.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Substrate-Like PCB Market Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Substrate-Like PCB Market Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Substrate-Like PCB Market Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Substrate-Like PCB Market Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Substrate-Like PCB Market Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Substrate-Like PCB Market Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Substrate-Like PCB Market Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Substrate-Like PCB Market Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,128.45 million → 2032: USD 42,588.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Substrate-Like PCB Market Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer Electronics Industries
- 12.3.7.2 Computing and Communications Sector
- 12.3.7.3 Automotive Industries
- 12.3.7.4 Medical Sector
- 12.3.7.5 Manufacturing Industries
- 12.3.7.6 Military, Defense, and Aerospace Sector
- 12.3.7.7 Other Applications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Line or Space Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Less than 25/25 µm
- 12.4.7.2 25/25 µm
- 12.4.7.3 30/30 µm
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Inspection Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automated Optical Inspection
- 12.5.7.2 Direct Imaging or Laser Direct Imaging
- 12.5.7.3 Automated Optical Shaping
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Substrate-Like PCB Market End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Substrate-Like PCB Market Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Substrate-Like PCB Market Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Substrate-Like PCB Market Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kinsus Interconnect Technology
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ibiden Co., Ltd.
- 18.4 Compeq Manufacturing Co., Ltd.
- 18.5 Unimicron Technology Corporation
- 18.6 Austria Technologies & Systemtechnik AG (AT&S)
- 18.7 TTM Technologies
- 18.8 Samsung Electro-Mechanics
- 18.9 Korea International Circuit Incorporation
- 18.10 Zhen Ding Technology
- 18.11 Daeduck Gds Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

