
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
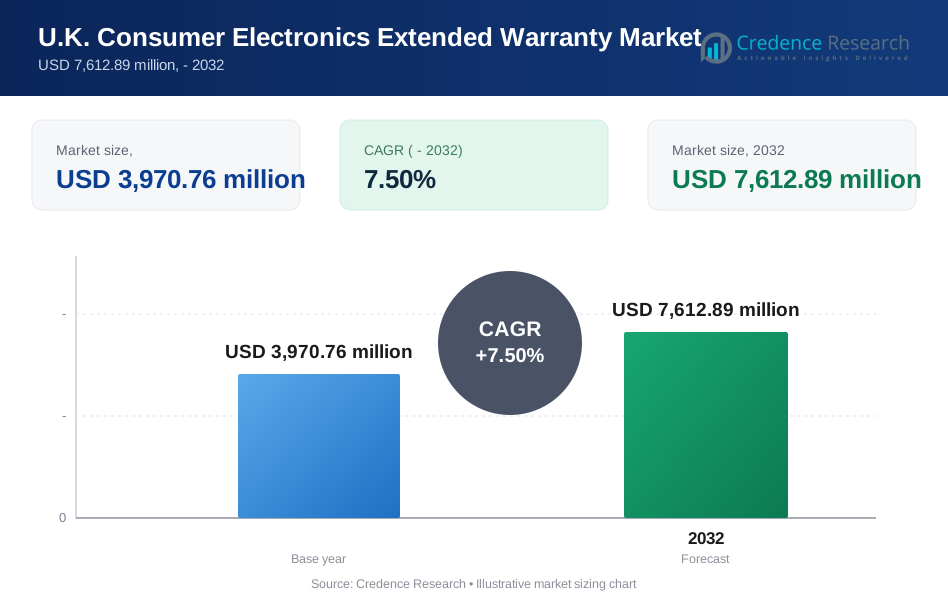
| U.K. Consumer Electronics Extended Warranty Market Size 2023 | USD 3,970.76 Million |
| U.K. Consumer Electronics Extended Warranty Market, CAGR | 7.50% |
| U.K. Consumer Electronics Extended Warranty Market Size 2032 | USD 7,612.89 Million |
Market Overview
The U.K. Consumer Electronics Extended Warranty Market is experiencing substantial growth, projected to increase from USD 3,970.76 million in 2023 to an estimated USD 7,612.89 million by 2032. This expansion reflects a robust compound annual growth rate (CAGR) of 7.50% from 2024 to 2032. This surge is fueled by the increasing demand for high-value consumer electronics coupled with consumers' heightened awareness of the benefits of extended warranty coverage. Such warranties are increasingly sought after to mitigate repair costs associated with sophisticated and high-tech consumer electronics. The trend towards digital transformation, which has led to an increase in the adoption of smart home devices and other advanced technologies, underscores the necessity for extended warranties to ensure long-term product reliability and customer satisfaction.
Several key drivers are propelling the U.K. Consumer Electronics Extended Warranty Market forward. Firstly, the rapid technological advancements in consumer electronics, such as smart appliances and wearable technology, make extended warranties more appealing as they help manage repair costs that could otherwise be significant. Additionally, the rise in the average selling price of consumer electronics has encouraged consumers to opt for extended warranty plans to protect their investments. The market is also witnessing a trend towards customization and personalization of warranty services, where providers are offering flexible warranty terms and multiple service options to cater to diverse consumer needs. This responsiveness to consumer preferences is enhancing customer loyalty and driving market growth.
Geographically, the market's expansion is predominantly concentrated in urban areas where consumer spending on electronics is higher and awareness of extended warranty benefits is more pronounced. Major players in the U.K. Consumer Electronics Extended Warranty Market include companies like Assurant, Inc., SquareTrade, Inc., and Domestic & General Group Limited. These key players are actively enhancing their offerings and expanding their services to capitalize on the growing market demand. Their strategies often involve partnerships with electronics manufacturers and retailers to offer warranty services at the point of sale, which simplifies the customer experience and helps in building consumer trust. As the market matures, these companies are expected to further innovate and possibly consolidate to maintain a competitive edge in this dynamic industry.
Market Drivers
Increasing Complexity and Cost of Consumer Electronics:
As technology advances, consumer electronics are becoming increasingly complex and expensive. For instance, the smartphone market in the U.K., which is a significant part of the consumer electronics sector, is expected to reach revenues of roughly ten billion British pounds in 2024. This complexity often translates into higher repair costs should the devices malfunction. Extended warranties offer consumers peace of mind by covering repair costs beyond the standard warranty period, making them a compelling option for protecting investments in high-value electronics. This driver is particularly significant in the context of a consumer base that is keen on adopting the latest technologies but is also risk-averse regarding potential repair expenses.
Consumer Preference for Extended Coverage:
Modern consumers are more aware than ever of the financial risks associated with the repair or replacement of high-tech devices. Extended warranties provide a safety net that appeals to this risk-conscious mindset. For example, approximately 31 percent of U.K. shoppers bought technology and electronics online rather than in-store, a marked increase in e-commerce user penetration compared to pre-pandemic levels. Additionally, there is a growing preference for extended warranties as consumers seek to manage the lifecycle costs of their electronics more effectively. This trend is supported by aggressive marketing by warranty providers who highlight the cost benefits and convenience of extended coverage, thereby encouraging more consumers to opt for extended warranties at the point of purchase.
Regulatory Support and Standardization:
The regulatory environment in the U.K. has been increasingly supportive of consumer rights, which indirectly boosts the extended warranty market. Regulations that mandate clear, understandable warranty terms and the right to seek redress for unsatisfactory goods influence consumers' decisions to purchase extended warranties. For instance, under the Consumer Rights Act 2015, a guarantee stands as a promise made by a trader to a consumer, without any additional charge, to repair, replace, or refund goods that do not meet the standards set out in the guarantee. Furthermore, efforts by industry bodies to standardize warranty services ensure that consumers receive transparent and fair services, enhancing trust and reliability in the extended warranty market. This regulatory support reassures consumers that their warranty claims will be handled professionally and fairly, thus driving market growth.
Strategic Partnerships and Integrated Offering at Point of Sale:
Extended warranty providers are entering into strategic partnerships with manufacturers and retailers to offer warranty products directly to consumers at the point of sale. This integration simplifies the purchasing process, making it more convenient for consumers to opt-in for extended coverage as they buy their electronics. Retailers and manufacturers benefit from these partnerships through additional revenue streams and enhanced customer satisfaction, as customers appreciate the convenience of one-stop shopping for both products and their associated protection plans. These partnerships are instrumental in driving the uptake of extended warranties, thereby contributing significantly to the market's expansion.
Market Trends
Customization and Flexibility:
There is an increasing demand for customized warranty solutions that cater to individual needs and preferences For instance, extended warranties for electric vehicles in the U.K. have emerged on the market in 2019. These warranties often come with various levels of coverage, allowing car owners to choose a plan that best suits their needs and budget.
Integration of Technology in Service Delivery:
Technological advancements are being leveraged to improve service delivery and customer experience in the extended warranty space. For example, extended warranty services are increasingly offering digital platforms for warranty registration, claims management, and customer support. Mobile apps, online portals, and self-service options are becoming standard features, allowing customers to easily access warranty information and file claims from their preferred devices.
Increased Online Sales:
The shift towards online shopping has been significantly accelerated by recent global events, including the pandemic. For instance, the estimated U.K. extended warranty market reached 8.6 million policies in 2022. This trend extends to the purchase of extended warranties, where there is a noticeable increase in consumers buying warranties online concurrently with their electronics.
Rising Awareness of Consumer Rights:
There is a growing awareness among consumers about their rights and the benefits of extended warranties. For example, under the Consumer Rights Act 2015, a guarantee stands as a promise made by a trader to a consumer, without any additional charge, to repair, replace, or refund goods that do not meet the standards set out in the guarantee. This regulatory support reassures consumers that their warranty claims will be handled professionally and fairly, thus driving market growth.
Partnerships and Collaborations:
Extended warranty providers are increasingly collaborating with electronics manufacturers and retailers to offer bundled products. These partnerships are mutually beneficial as they enhance product offerings and improve consumer trust and satisfaction. They also help in standardizing warranty services across different platforms and retailers, creating a more unified market.
Focus on Sustainable Practices:
Sustainability is becoming a significant concern among consumers, and this extends to the extended warranty market. Providers are now looking at ways to include sustainable practices in their operations, such as offering services that promote product longevity and reduce electronic waste. This not only appeals to environmentally conscious consumers but also aligns with global sustainability goals.
Expansion of Coverage to Include Accidental Damage:
Traditionally, extended warranties covered failures due to manufacturing defects or normal wear and tear. However, there is a trend towards including coverage for accidental damage, such as screen breaks and liquid damage. This broader coverage is becoming a key selling point, particularly for portable electronics, which are prone to such accidents.
Market Restraints and Challenges
Consumer Skepticism and Trust Issues:
A major restraint in the market is the level of skepticism among consumers regarding the true value of extended warranties. This skepticism is often fueled by past experiences where consumers felt that the terms of the warranty were not sufficiently clear or that the claims process was overly cumbersome and restrictive. Additionally, high-profile cases of mis-selling and lack of transparency have led to trust issues, making consumers hesitant to opt for extended warranties.
Regulatory Challenges:
The extended warranty sector faces stringent regulatory scrutiny, particularly concerning consumer protection and the fairness of terms in warranty contracts. Complying with these regulations can be challenging for providers, requiring them to invest in legal and compliance functions, which can increase operational costs. Moreover, changes in regulatory frameworks can necessitate adjustments in business practices, which can be both time-consuming and costly.
Competition from Free Warranty Extensions and Credit Card Benefits:
Many credit card companies offer extended warranty benefits as part of their service packages, which can act as a direct competitor to traditional extended warranty services. Additionally, manufacturers may offer extended warranty periods as a promotional tactic or a feature of premium products. These alternatives can limit the market for third-party extended warranty providers, as consumers might opt for these free or included services instead of purchasing additional coverage.
Economic Downturns:
Economic instability or downturns significantly impact consumer spending patterns, particularly in terms of discretionary expenditures such as extended warranties. During economic slowdowns, consumers are more likely to prioritize essential purchases and cut back on additional coverages, which can lead to reduced sales in the extended warranty market.
Technological Durability:
The increasing durability and reliability of consumer electronics can also pose a challenge to the extended warranty market. As technology advances, electronics are being built to last longer and with fewer mechanical issues, reducing the perceived necessity of purchasing extended warranties.
Market Saturation:
The U.K. market for extended warranties is becoming increasingly saturated with numerous players offering similar services. This saturation leads to intense competition, which can pressure profit margins and force companies to lower prices or offer additional services, impacting their overall profitability.
Market Segmentation Analysis
By Product Type
Smartphones and tablets, laptops and PCs, and home appliances each represent crucial segments within the U.K. Consumer Electronics Extended Warranty Market. The smartphones and tablets segment holds a significant market share, driven by the high costs and vulnerability to damage associated with these devices. Meanwhile, extended warranties for laptops and PCs are widely favored among both individual consumers and businesses, aimed at safeguarding their investments in essential computing technology. Additionally, as smart home technologies and costly appliances become more prevalent, there is an increasing demand for extended warranties to protect these high-value items, ensuring their longevity and performance.
By Coverage Type
In the U.K. Consumer Electronics Extended Warranty Market, various coverage options cater to different consumer needs. Standard Protection Plans typically address mechanical failures and manufacturer defects beyond the original warranty period. As many consumer electronics are portable, Accidental Damage Protection plans are increasingly favored, covering incidents such as drops or liquid spills. Furthermore, Comprehensive Coverage plans offer the most extensive protection, safeguarding against a broad spectrum of issues, including theft and loss, thereby providing consumers with the highest level of security for their electronic devices.
By Distribution Channel
Retail stores, online platforms, and direct sales each play significant roles in the distribution of extended warranties in the U.K. Consumer Electronics Extended Warranty Market. Many consumers prefer purchasing extended warranties directly at the point of sale when buying their electronics, positioning retail stores as a vital distribution channel. Concurrently, the rise of e-commerce has made online platforms an increasingly popular channel for acquiring extended warranties, thanks to their convenience and often competitive pricing. Additionally, some warranty providers leverage direct sales, selling warranties directly to consumers through their websites or customer service centers, which allows them to provide more customized or specialized warranty services. These diverse distribution channels ensure that consumers have multiple avenues to secure the protection they need for their electronic purchases.
Segments
Based on Product Type
- Smartphones and Tablets
- Laptops and PCs
- Home Appliances
Based on Coverage Type
- Standard Protection Plans
- Accidental Damage Protection
- Comprehensive Coverage
Based on Distribution Channel
- Retail Stores
- Online Platforms
- Direct Sales
Regional Analysis
London (22%):
As the economic powerhouse of the U.K., London dominates the consumer electronics extended warranty market, accounting for approximately 22% of the market share. The high concentration of tech-savvy consumers and the presence of numerous multinational corporations drive demand for extended warranties, especially for high-end electronics and smart devices. The region's affluent consumer base is more likely to invest in protecting their technological investments, making it a critical area for warranty providers.
South East (18%):
Following closely, the South East holds around 18% of the market share. This region benefits from its proximity to London and a similarly high standard of living. Consumers in the South East show a strong preference for comprehensive coverage plans, particularly for consumer electronics that are integral to remote work and home entertainment.
North West (15%):
The North West, with a market share of about 15%, shows a robust demand for extended warranties, driven by a large population and a growing tech industry. Cities like Manchester and Liverpool have seen rapid technological adoption, which in turn fuels the extended warranty market.
West Midlands (12%):
Accounting for approximately 12% of the market, the West Midlands' demand for extended warranties is bolstered by an increasing number of small to medium-sized enterprises adopting advanced tech solutions. The region's focus on economic diversification into digital and tech sectors also supports growth in this market.
Key players
- Maplin
- Amazon UK Protection Plans
- Richer Sounds
- John Lewis & Partners
- Currys PC World
- Domestic & General
Competitive Analysis
The U.K. Consumer Electronics Extended Warranty Market is marked by intense competition among established and specialized players. Domestic & General stands out with its comprehensive offerings tailored to various consumer electronics, backed by decades of experience in warranty services. Currys PC World leverages its vast retail presence, offering warranty services at the point of sale, which is crucial for customer convenience. John Lewis & Partners and Richer Sounds differentiate themselves through premium service quality and customer-centric policies. Amazon UK Protection Plans capitalizes on its robust online platform to offer seamless warranty purchases. Maplin, focusing on electronic components and gadgets, provides niche coverage that appeals to tech enthusiasts. Each player’s strategy focuses on enhancing customer experience, trust, and tailored warranty solutions, which are key to gaining and retaining market share in this competitive landscape.
Recent Developments
In January 2023, Voltas and OneDios joined forces to roll out a nationwide extended warranty program, empowering customers to purchase extended warranties for Voltas and Voltas Beko products via the OneDios app. This collaboration ensures access to brand-authorized services, original spare parts, and competitive pricing, while the app simplifies warranty claims and enables users to lodge complaints in under 60 seconds.
In February 2024, AmTrust disclosed adjustments in automotive warranty program claim severity amidst shifting industry dynamics. Concurrently, the company intensified its focus on engaging with past customers, aiming to bolster customer satisfaction and retention.
In March 2024, ASSURANT Inc. unveiled an innovative AI-powered claims chatbot designed to facilitate swift and hassle-free claims processing for customers, enhancing overall service efficiency and customer experience.
By April 2024, Asurion had forged a partnership with electric scooter manufacturer Okinawa Autotech to introduce an extended warranty initiative in India, covering essential powertrain components. This collaboration aims to provide Okinawa Autotech customers with added peace of mind and confidence in their electric scooter ownership experience.
Market Concentration and Characteristics
The U.K. Consumer Electronics Extended Warranty Market exhibits a moderately concentrated structure, characterized by the presence of a few major players alongside several smaller, niche firms. Key players like Domestic & General, Currys PC World, and John Lewis & Partners dominate the market, leveraging their extensive retail networks and strong brand reputations to capture significant market shares. These major players are complemented by specialized providers such as Richer Sounds and Maplin, who cater to specific segments of the consumer electronics spectrum, offering detailed and often more personalized warranty solutions. This market concentration is further defined by strategic partnerships between warranty providers and manufacturers or retailers, aimed at offering integrated warranty services at the point of sale. Such collaborations enhance the accessibility and attractiveness of extended warranties to consumers, reinforcing the market's competitive dynamics and its focus on customer service and comprehensive coverage options.
Report Coverage
The research report offers an in-depth analysis based on Type, Coverage Type, Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As smart home technologies become increasingly prevalent, the demand for extended warranties covering these devices will surge, offering protection against technological obsolescence and malfunctions.
- The proliferation of Internet of Things (IoT) devices will drive the need for comprehensive coverage plans that include not only hardware malfunctions but also software issues and connectivity disruptions.
- Companies will invest in improving the customer service aspect of warranty claims, utilizing AI and machine learning to expedite claim processing and enhance user satisfaction.
- Future offerings will likely include more flexible coverage options that can be personalized to fit individual consumer needs, focusing on scalability and adaptability.
- Extended warranties will become more integrated with the retail experience, offered seamlessly at the point of sale, particularly in online platforms, to capitalize on the e-commerce boom.
- There will be a stronger emphasis on sustainability, with warranty providers offering services that encourage longer lifespans for electronics, reducing environmental impact.
- Subscription-based warranty models might gain popularity, offering consumers ongoing protection for a monthly fee, thus ensuring continuous coverage without the need for contract renewals.
- The market may see consolidation with larger players acquiring smaller competitors to broaden their service offerings and geographic reach within the U.K.
- Changes in consumer protection laws and regulations will continue to shape the market, possibly tightening standards around transparency and consumer rights in warranty contracts.
- Advances in technology, such as the development of more durable and self-diagnosing devices, might challenge the traditional warranty market, pushing companies to innovate and redefine what extended warranties cover.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size, CAGR, and growth trajectory of the U.K. Consumer Electronics Extended Warranty Market?
What is driving the growth of the U.K. Consumer Electronics Extended Warranty Market?
How are extended warranty providers adapting to consumer preferences for personalized services?
What role do strategic partnerships play in the extended warranty market?
How are technological advancements impacting the extended warranty industry?
What are the key factors influencing consumer decisions to purchase extended warranties?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.K. Consumer Electronics Extended Warranty Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.K. Consumer Electronics Extended Warranty Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 3,970.76 million → 2032: USD 7,612.89 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.K. Consumer Electronics Extended Warranty Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.K. Consumer Electronics Extended Warranty Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.K. Consumer Electronics Extended Warranty Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.K. Consumer Electronics Extended Warranty Market Drivers
- 3.3 U.K. Consumer Electronics Extended Warranty Market Restraints & Challenges
- 3.4 U.K. Consumer Electronics Extended Warranty Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.K. Consumer Electronics Extended Warranty Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.K. Consumer Electronics Extended Warranty Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.K. Consumer Electronics Extended Warranty category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.K. Consumer Electronics Extended Warranty Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.K. Consumer Electronics Extended Warranty Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.K. Consumer Electronics Extended Warranty market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.K. Consumer Electronics Extended Warranty Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.K. Consumer Electronics Extended Warranty Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.K. Consumer Electronics Extended Warranty Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.K. Consumer Electronics Extended Warranty (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.K. Consumer Electronics Extended Warranty Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.K. Consumer Electronics Extended Warranty Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.K. Consumer Electronics Extended Warranty Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.K. Consumer Electronics Extended Warranty Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.K. Consumer Electronics Extended Warranty Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.K. Consumer Electronics Extended Warranty Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.K. Consumer Electronics Extended Warranty Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.K. Consumer Electronics Extended Warranty Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.K. Consumer Electronics Extended Warranty Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
