
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK High-End Beef Market Size 2023 | USD 735.62 million |
| UK High-End Beef Market, CAGR | 6.28% |
| UK High-End Beef Market Size 2032 | USD 1,197.37 million |
Market Overview
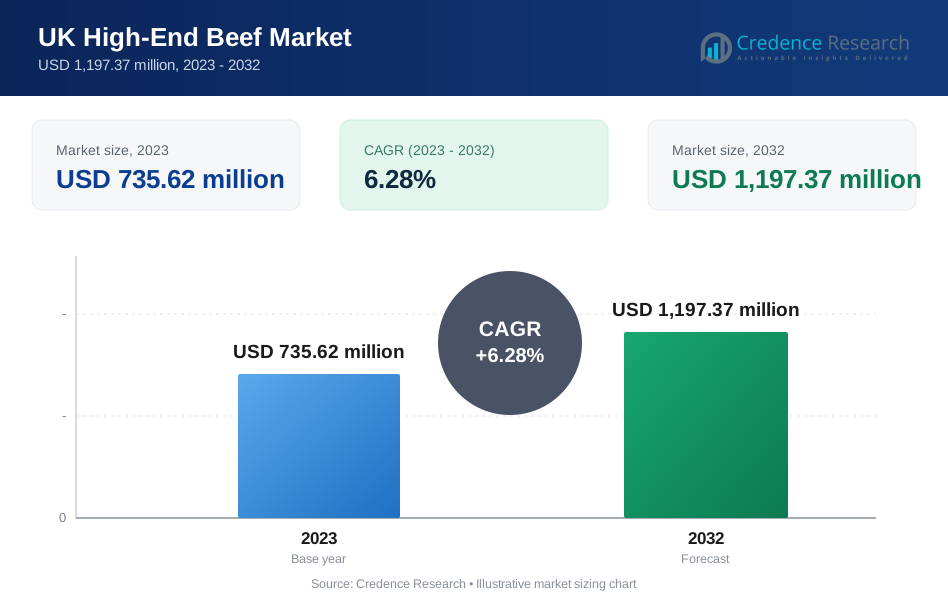
The UK High-End Beef Market is projected to grow from USD 735.62 million in 2023 to USD 1,197.37 million by 2032, reflecting a CAGR of 6.28% from 2024 to 2032. This steady growth is driven by increasing consumer demand for premium, ethically sourced, and sustainably produced beef.
Several key factors are driving the market's growth. The rising disposable income of consumers and a growing preference for premium and organic meat products have fueled demand for high-end beef. Additionally, increasing awareness of animal welfare and sustainable farming practices is prompting consumers to choose ethically sourced beef, boosting sales of grass-fed and free-range varieties. Technological advancements in meat processing, packaging, and traceability solutions also contribute to market growth, ensuring quality, safety, and extended shelf life.
Geographically, London and other metropolitan regions lead the market due to high consumer spending on premium food products. Demand is also growing in suburban and rural areas as specialty retailers and online platforms expand their reach. Key players in the UK High-End Beef Market include Dovecote Park Ltd., ABP Food Group, Cargill Inc., Tyson Foods, and Creekstone Farms, among others. These companies focus on sustainable sourcing, innovative product offerings, and premium branding strategies to strengthen their market presence.
Market Insights
- The UK High-End Beef Market is projected to grow from USD 735.62 million in 2023 to USD 1,197.37 million by 2032, driven by a CAGR of 6.28%.
- Increasing consumer preference for high-quality cuts like Wagyu and dry-aged beef fuels market growth, particularly in the fine dining and gourmet home cooking sectors.
- Growing awareness of animal welfare and sustainable farming practices is leading to higher demand for grass-fed and ethically sourced beef.
- Meat processing innovations, along with packaging and traceability solutions, are enhancing quality control and extending product shelf life.
- London and metropolitan areas are the largest markets, with increasing demand also seen in suburban and rural regions through specialty retailers and online platforms.
- Rising feed and land costs, along with labor shortages, are challenges faced by producers, impacting the pricing of high-end beef products.
- Major players like Cargill Inc., ABP Food Group, and Tyson Foods are focusing on sustainable sourcing and innovative product differentiation to maintain market leadership.
Market Drivers
Rising Consumer Demand for Premium and Ethical Meat Products
The increasing consumer preference for premium-quality beef is a primary driver of market growth. Discerning consumers are actively seeking superior taste, texture, and marbling, making high-end beef varieties such as Wagyu, Angus, and dry-aged beef increasingly popular. This trend is largely driven by a growing food culture that emphasizes gourmet dining experiences, even at home. The rise in food-related content across social media, television programs, and online recipe platforms has contributed to this demand as consumers become more knowledgeable about high-quality cuts and preparation techniques. For instance, Brandt Beef emphasizes that its Holstein steers are raised within the organization, with cattle feed grown on 600 acres of adjacent land. This level of transparency and quality control resonates with modern consumers.Ethical considerations also play a crucial role in purchasing decisions. Modern consumers are more conscious of animal welfare, sustainability, and transparency in food sourcing. As a result, they prefer grass-fed, free-range, and organically raised beef, which are perceived as healthier and more environmentally responsible options. The emphasis on clean labeling and traceability has prompted premium beef producers to adopt stringent quality control measures, reinforcing consumer trust and market growth. These factors collectively drive the demand for premium and ethical meat products.
Increasing Disposable Income and Changing Lifestyle Preferences
Rising disposable income levels in the UK have significantly influenced the high-end beef market, enabling consumers to spend more on luxury food items. As the standard of living improves, many consumers are shifting towards quality over quantity, opting for premium cuts rather than lower-cost alternatives. This trend is particularly noticeable among affluent households and urban professionals who prioritize gourmet and fine dining experiences. For instance, in 2022, food service sales of certified Angus beef products experienced growth, highlighting the increasing consumer preference for high-quality beef in upscale dining settings.Additionally, changing dietary habits contribute to this shift. Consumers are becoming increasingly interested in protein-rich diets and healthier eating patterns, further driving the demand for lean, high-quality beef. The popularity of low-carb and high-protein diets such as keto and paleo has increased the appeal of premium beef as a nutrient-dense protein source. Furthermore, the growing trend of at-home fine dining and food experimentation—accelerated by the pandemic—has led to a surge in demand for premium meat cuts and specialty beef products in retail and online markets. These evolving lifestyle preferences underscore the growing importance of premium beef as part of modern dietary choices.
Expansion of Specialty Retail, E-Commerce, and Direct-to-Consumer Channels
The retail landscape for high-end beef has evolved significantly with specialty butcher shops, gourmet food markets, and online platforms playing pivotal roles in increasing accessibility to premium beef products. The rise of e-commerce and direct-to-consumer (DTC) models has allowed premium beef producers to reach a broader audience by offering subscription boxes, curated meat selections, and farm-to-table delivery services. For instance, S-Group in Finland uses its e-commerce capabilities to connect customers directly with a beef farmer, facilitating online orders and deliveries through their system.Consumers now have greater access to high-quality beef from specialty farms and independent producers thanks to digital marketplaces that provide detailed information about sourcing, grading, and processing methods. The convenience of ordering premium beef cuts online—coupled with the assurance of quality through vacuum-sealed packaging and cold-chain logistics—has contributed to strong market growth. Additionally, luxury supermarkets, gourmet restaurants, and high-end food service providers are expanding their premium beef offerings to cater to growing demand. Exclusive partnerships between high-end beef producers and upscale retailers further strengthen the availability and visibility of premium beef products across the UK.
Advancements in Sustainable and Ethical Beef Production Practices
Sustainability has become a major driving force in the UK high-end beef market, influencing both consumer purchasing behavior and industry practices. Consumers increasingly demand sustainably sourced beef, encouraging producers to adopt eco-friendly farming methods that prioritize animal welfare, reduced carbon footprint, and responsible land management. For instance, the US Roundtable for Sustainable Beef (USRSB) has designed priority indicators—including metrics for water resource use, animal welfare practices, and greenhouse gas emissions—to advance sustainable production practices within the industry.The adoption of regenerative agriculture—which emphasizes soil health, biodiversity, and carbon sequestration—has gained momentum in the premium beef industry. Producers are investing in grass-fed and pasture-raised systems that align with sustainability goals while enhancing nutritional quality and flavor profiles. Moreover, blockchain technology is being utilized to provide transparent sourcing information that reinforces consumer confidence in ethical meat production. Government regulations promoting sustainable livestock farming also shape market dynamics by encouraging carbon-neutral farming techniques under initiatives such as the UK’s Net Zero commitment. These advancements not only enhance brand reputation but also solidify high-end beef's position as a responsible luxury food choice among discerning consumers.
Market Trends
Growing Preference for Ethical and Sustainable Beef Production
Sustainability and ethical sourcing have become central to consumer purchasing decisions in the high-end beef market. Consumers are increasingly prioritizing grass-fed, free-range, and organically raised beef, as these options align with ethical consumption and environmental responsibility. The focus on animal welfare, lower carbon emissions, and regenerative agriculture is shaping both production methods and marketing strategies for premium beef brands. For instance, a 2022 Kearney study revealed a growing interest in sustainability, with Google searches for the carbon footprint of beef increasing significantly. Additionally, the National Cattlemen’s Beef Association’s Consumer Beef Tracker highlighted that beef ranks as the top protein choice among consumers who prioritize causes like environmental responsibility and ethical sourcing.Regenerative farming practices, which enhance soil health and biodiversity, are gaining traction among high-end beef producers. These methods contribute to carbon sequestration and reduced environmental impact, making beef production more sustainable. Many brands are also incorporating blockchain technology for traceability, allowing consumers to track the journey of beef from farm to table. Government initiatives promoting carbon neutrality further encourage eco-friendly practices. With rising awareness about climate impact and animal welfare, certifications like "Certified Organic" and "Carbon Neutral" are becoming essential in differentiating premium beef products in markets such as the UK.
Surge in Demand for Premium Beef in Home Dining and E-Commerce
The rise of gourmet home cooking and the expansion of digital retail platforms have reshaped how consumers purchase and consume high-end beef. As more people experiment with restaurant-style meals at home, the demand for luxury cuts and specialty beef products has increased significantly. For instance, research shows that 76% of meals are now cooked at home, with 94% of consumers who increased home cooking during the pandemic planning to continue this trend. Furthermore, the "Today's Beef Consumer" report found that 64% of shoppers order groceries online, with 44% including fresh beef in their orders.Subscription-based meat delivery services have gained popularity, offering curated selections of premium beef cuts directly to consumers. These services provide convenience and exclusivity, catering to discerning buyers who seek high-quality beef without visiting specialty stores. E-commerce platforms have become key distribution channels for high-end beef, enabling consumers to access detailed product descriptions and traceability information before making a purchase. Specialty meal kits featuring pre-marinated premium cuts are also gaining traction among urban consumers who enjoy luxury dining at home without extensive preparation. This shift toward online shopping and direct-to-consumer models has allowed high-end beef producers to expand their market reach beyond traditional retail channels.
Innovation in Dry-Aged and Specialty Beef Cuts
The demand for unique and specialty beef cuts has surged as consumers seek refined dining experiences. High-end restaurants and gourmet butchers are capitalizing on this trend by offering custom dry-aging services and exclusive cuts. Dry-aged beef, known for its enhanced tenderness and intensified flavor, is becoming a staple in premium butcher shops and upscale dining establishments. For instance, studies have shown that dry-aged steaks exhibit significantly higher intensities of beefy and roasted flavors compared to unaged steaks, making them a sought-after choice for steak enthusiasts.Consumers are also showing interest in underutilized cuts such as Denver steak, Bavette, and Picanha, which offer distinctive textures and flavors beyond traditional choices like sirloin or ribeye. Restaurants are experimenting with custom aging techniques such as whiskey-aged or butter-aged beef to introduce unique flavor profiles that cater to high-end consumers who appreciate craftsmanship in meat processing. Wagyu beef continues to dominate the high-end segment due to its exceptional marbling and buttery texture. Many UK farms now produce locally sourced Wagyu to reduce import dependence while maintaining world-class quality. This growing preference for specialty options highlights a shift toward experiential dining where culinary exploration drives purchasing decisions.
Rise of High-Protein Diets and Health-Conscious Consumption
Consumers are increasingly health-conscious, influencing the demand for nutrient-dense, high-protein food sources like premium beef. The rise of protein-focused diets such as keto, paleo, and carnivore diets has made lean, high-quality beef a preferred choice among fitness enthusiasts and health-driven individuals. For instance, a 6oz portion of 80% lean beef provides 46 grams of protein along with essential amino acids like cysteine, glutamate, and glycine—precursors to glutathione that support overall health.Grass-fed and organic beef is gaining popularity due to its higher levels of Omega-3 fatty acids, CLA (conjugated linoleic acid), and antioxidants compared to grain-fed alternatives. Many consumers now adopt a "less but better" eating approach—reducing overall meat consumption while opting for premium quality when they do consume it. Functional products like collagen-rich cuts, bone marrow-based offerings, and liver supplements are also gaining traction within wellness circles as they cater to holistic nutrition needs. Nitrate-free, antibiotic-free, and hormone-free options are becoming mainstream as brands highlight these attributes on clean labels to attract health-conscious buyers. As consumer preferences evolve toward better nutrition and ethical options, the high-end beef market continues adapting with transparency-focused innovations.
Market Challenges
High Production Costs and Supply Chain Constraints
The production of premium beef is marked by significantly higher operational costs, presenting challenges for both producers and consumers. Raising grass-fed, free-range, and organically certified cattle requires large grazing areas, sustainable feed options, and adherence to strict animal welfare practices, all of which add to production expenses. Furthermore, compliance with stringent regulations on livestock farming and sustainability increases the financial burden for producers. Rising feed costs, labor shortages, and escalating land expenses contribute to the higher price of high-end beef, limiting its accessibility. Supply chain disruptions, including transportation delays and processing inefficiencies, can also affect the availability of specialty cuts, such as Wagyu and dry-aged beef. Additionally, the limited local sourcing of premium breeds often forces reliance on imports, leaving the market vulnerable to global price fluctuations and trade restrictions. To overcome these obstacles, industry players must focus on supply chain optimization, sustainable farming practices, and cost-efficient processing methods while preserving premium quality standards.
Changing Consumer Preferences and Market Competition
Despite strong demand for premium beef, changing consumer preferences and the growing competition from alternative protein sources pose potential threats to market growth. As consumers become more conscious of health, sustainability, and ethical consumption, many are turning to plant-based meats, lab-grown proteins, and flexitarian diets, reducing their beef consumption. The rise of veganism, plant-based diets, and government initiatives supporting sustainability has spurred interest in low-carbon footprint protein alternatives. Additionally, premium poultry and seafood are gaining traction as substitutes for high-end beef, providing luxury dining options with a reduced environmental impact. The market also faces heightened competition from artisanal butchers, specialty retailers, and international beef brands, compelling local producers to differentiate their offerings through superior quality, branding, and consumer engagement. To remain competitive, high-end beef brands must emphasize ethical sourcing, exceptional taste, nutritional benefits, and unique dining experiences.
Market Opportunities
Expansion of Direct-to-Consumer (DTC) and Digital Retail Channels
The growing demand for premium, ethically sourced beef has led to the rise of online retail and direct-to-consumer (DTC) channels, including subscription-based services and farm-to-table delivery models. Consumers are increasingly gravitating toward convenient, high-quality meat purchasing options, prompting the expansion of e-commerce platforms, specialty butcher websites, and gourmet meal kits that feature premium beef. By establishing direct partnerships with consumers, high-end beef brands are able to offer fresh, traceable, and exclusive cuts, reducing supply chain disruptions. Subscription services that curate beef selections and offer customized meal plans are becoming more popular, providing consumers with assurance of quality and convenience. Furthermore, blockchain-based traceability solutions are enhancing transparency, reinforcing consumer trust in sustainably sourced and ethically produced beef.
Growing Demand for Sustainable and Specialty Beef Products
Consumers are placing greater emphasis on sustainability, health-conscious diets, and ethical meat consumption, creating opportunities for premium beef producers to offer grass-fed, organic, and regenerative-farmed products. These offerings differentiate brands by highlighting superior nutritional value, animal welfare, and eco-friendly farming practices. Certified organic, free-range, and low-carbon beef products are especially appealing to health-conscious and environmentally aware buyers. Additionally, specialty cuts and aged beef varieties provide opportunities for premium pricing in fine dining, high-end retail, and gourmet home cooking markets. Brands can further enhance their competitive edge by incorporating storytelling and sustainability certifications, which resonate with a growing segment of ethical consumers.
Market Segmentation Analysis
By Product Type
The UK High-End Beef Market offers a wide array of premium beef varieties designed to meet diverse consumer tastes and quality demands. Wagyu, renowned for its exceptional marbling, rich flavor, and tenderness, remains a dominant choice in the high-end segment. Both Japanese-imported and locally produced British Wagyu are gaining popularity among fine-dining restaurants and gourmet home chefs. Angus beef, valued for its juiciness and consistent quality, is a leading choice for premium steak cuts, with many UK farms focusing on grass-fed Angus to meet the rising demand for sustainably sourced meat. Hereford, a heritage breed, is cherished for its natural tenderness and robust beefy taste, appealing to consumers looking for locally sourced, ethically raised beef. Charolais, known for its leaner, high-protein cuts, is favored by health-conscious consumers seeking lower-fat premium beef options. Additionally, specialty breeds like Dexter and Longhorn cater to niche markets that appreciate traditional British beef with unique flavor profiles.
By End User
The UK High-End Beef Market primarily serves two key consumer segments: households and the food service industry. The growing trend of gourmet home cooking and premium meal preparation has significantly increased the demand for high-end beef among households, with consumers opting for dry-aged cuts, Wagyu steaks, and organic beef for upscale dining at home. The food service industry remains the largest driver of demand, with high-end restaurants, luxury hotels, and fine-dining establishments sourcing premium beef cuts to enhance their menus. These venues offer exclusive items like Wagyu steaks and aged beef selections to attract affluent customers. Additionally, specialty catering services and gourmet food retailers contribute to market growth by sourcing high-quality beef for curated dining experiences and premium meal kits.
Segments
Based on Product Type
- Wagyu Beef
- Angus Beef
- Hereford and Charolais Beef
- Other
Based on End User
- Households
- Food Service Industry
- Others
Based on Distribution Channel
- Online Retail
- Specialty Butcher Shops
- Supermarkets/Hypermarkets
- Others
Based on Region
- London & South East England
- Midlands & North England
- Scotland
- South West England & Wales
Regional Analysis
London & South East England (40%)
London and the surrounding South East region are the leading contributors to the UK High-End Beef Market, accounting for approximately 40% of the market share. This area's dominance is driven by its high concentration of affluent consumers, a thriving food service sector, and a large number of gourmet restaurants and upscale supermarkets. Wagyu beef, dry-aged cuts, and other premium products are in high demand in this region, fueled by both fine dining establishments and luxury home cooking. The presence of high-end food retailers such as Waitrose, Harrods, and Whole Foods further strengthens demand. Additionally, the strong online retail presence in London has significantly expanded the availability of specialty beef cuts directly to consumers.
Midlands & North England (25%)
The Midlands and North England region contributes approximately 25% of the overall market share, with key cities such as Manchester, Birmingham, and Leeds serving as hubs for premium beef consumption. While this region may not match London in overall spending power, the growing interest in premium cuts and the rise of sustainable, locally sourced beef have created a strong demand for high-end beef. The popularity of Angus beef and free-range options is prominent here, particularly in both household purchases and food service sectors. The strong presence of independent butchers and specialty meat retailers in this region plays a crucial role in catering to a more discerning consumer base seeking ethical and high-quality beef products.
Key players
- Cargill, Inc.
- National Beef Packing Company, LLC
- Marfrig Global Foods S.A.
- Hormel Foods Corporation
- Smithfield Foods, Inc.
- Perdue Farms Inc.
- BRF S.A.
- Vion Food Group
- Minerva Foods
- NH Foods Ltd.
- Danish Crown
- OSI Group, LLC
- Keystone Foods
- American Foods Group, LLC
- Foyle Food Group
- ABP Food Group
- Meyer Natural Foods
- Greater Omaha Packing Company, Inc.
Competitive Analysis
The UK High-End Beef Market is highly competitive, with both global and regional players vying for market share. Cargill, Inc. and National Beef Packing Company, LLC lead in terms of production capacity and global reach, offering a wide range of premium beef products. These companies focus on sustainable farming practices, quality assurance, and traceability to meet rising consumer demand for ethically sourced beef. Other key players like Marfrig Global Foods S.A., Smithfield Foods, Inc., and ABP Food Group emphasize product differentiation through value-added offerings, including specialty cuts and dry-aged beef. Smaller companies such as Foyle Food Group and Greater Omaha Packing Company, Inc. focus on local sourcing and high-end meat processing to cater to niche, quality-conscious markets. These players are also increasingly adopting digital and direct-to-consumer platforms to expand their reach, ensuring access to premium beef cuts for a growing consumer base.
Recent Developments
- In November 2024, Cargill announced plans to expand its operations to cater to growing consumer demand for premium beef products. The company is focusing on innovation and investment in specialty beef offerings, aligning with consumer trends toward indulgence and sustainability. Additionally, Cargill implemented workforce restructuring in December 2024, consolidating its agricultural footprint, including meat processing operations, amidst challenges like declining global crop prices and a shortage of U.S. cattle.
- In Q3 2024, Marfrig reported a 12.4% revenue increase driven by strong operational performance despite challenges in North America. The company has also strengthened its partnership with BRF S.A., launching Sadia as a global beef brand in January 2025. This strategic move aims to expand Marfrig's international presence, particularly in the Middle East halal market, while leveraging synergies with BRF for premium beef exports
- During fiscal 2024, Hormel Foods achieved significant sales growth in its premium prepared proteins segment. The company emphasized its focus on high-quality meats and innovative product lines, such as Hormel Fire Braised meats and Hormel Bacon 1, which cater to the premium beef market. Hormel also reported progress in its Transform and Modernize (T&M) initiative, generating $75 million in operational benefits by the end of fiscal 2024.
- In August 2024, Smithfield Foods carved out its European operations to establish standalone strategies tailored to regional market dynamics. This includes targeting the UK market with fresh pork and packaged meats under its Morliny Foods subsidiary. Additionally, Smithfield announced plans for an IPO in January 2025 to enhance its financial flexibility and focus on expanding its packaged meats segment.
- In October 2024, Vion Food Group reported financial losses due to impairments from exiting the German market but highlighted growth opportunities in premium beef products for European markets like the UK. Vion continues to focus on customer-oriented innovations through its Consumer Monitor insights, ensuring high-quality offerings tailored to shifting consumer preferences.
Market Concentration and Characteristics
The UK High-End Beef Market exhibits a moderate level of market concentration, with a few key players holding substantial market share while also being characterized by significant competition from both global corporations and local artisanal producers. Large-scale companies like Cargill, Inc., National Beef Packing Company, LLC, and Marfrig Global Foods S.A. dominate production and distribution, leveraging economies of scale, supply chain efficiencies, and widespread distribution networks. However, smaller players such as ABP Food Group and Foyle Food Group are also influential, focusing on specialized products and premium offerings, catering to niche markets. The market is driven by consumer preferences for high-quality, ethically sourced beef, including grass-fed and organic varieties, as well as specialty cuts like Wagyu and dry-aged beef. Increasing interest in sustainability and traceability is also pushing players toward innovative production practices and digital retail channels to meet evolving demand.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK High-End Beef Market will continue to experience growing demand for premium beef cuts such as Wagyu, Angus, and dry-aged beef, driven by the rise in gourmet dining and home cooking.
- Consumers will increasingly prioritize sustainably sourced, grass-fed, and ethically raised beef, as awareness of animal welfare and environmental impact grows.
- Online platforms and subscription-based services will dominate the distribution of high-end beef, offering convenience, traceability, and premium product accessibility to consumers.
- With the rise in health-focused diets, high-protein and nutrient-rich beef options, such as lean cuts and organic beef, will gain traction among fitness-conscious individuals.
- Innovations in meat processing and packaging technologies will improve product quality, shelf life, and food safety, boosting the appeal of premium beef products.
- Consumers will demand greater product transparency, with technologies like blockchain providing detailed information on sourcing, quality, and sustainability.
- The market will see wider adoption of regenerative agriculture and carbon-neutral farming techniques, improving environmental credentials of premium beef brands.
- As consumer preferences become more localized, demand for regionally sourced, high-quality beef will increase, especially for heritage breeds like Hereford and Charolais.
- Ongoing competition will spur product innovation, with premium beef producers focusing on unique flavor profiles, custom cuts, and value-added offerings to differentiate their brands.
- Expect more investments in high-end beef production, particularly in sustainable farming practices and ethical supply chains, aligning with shifting consumer values towards quality and responsibility.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UK High-End Beef Market in 2023 and 2032?
What is driving the growth of the UK High-End Beef Market?
Which regions lead the UK High-End Beef Market?
What are the key factors influencing consumer demand for high-end beef?
Who are the key players in the UK High-End Beef Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK High-End Beef Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK High-End Beef Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 735.62 million → 2032: USD 1,197.37 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK High-End Beef Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK High-End Beef Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK High-End Beef Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK High-End Beef Market Drivers
- 3.3 UK High-End Beef Market Restraints & Challenges
- 3.4 UK High-End Beef Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK High-End Beef Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK High-End Beef Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK High-End Beef category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK High-End Beef Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK High-End Beef Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK High-End Beef market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK High-End Beef Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK High-End Beef Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK High-End Beef Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK High-End Beef (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK High-End Beef Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK High-End Beef Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK High-End Beef Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK High-End Beef Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK High-End Beef Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK High-End Beef Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK High-End Beef Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK High-End Beef Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK High-End Beef Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
