
Market Overview
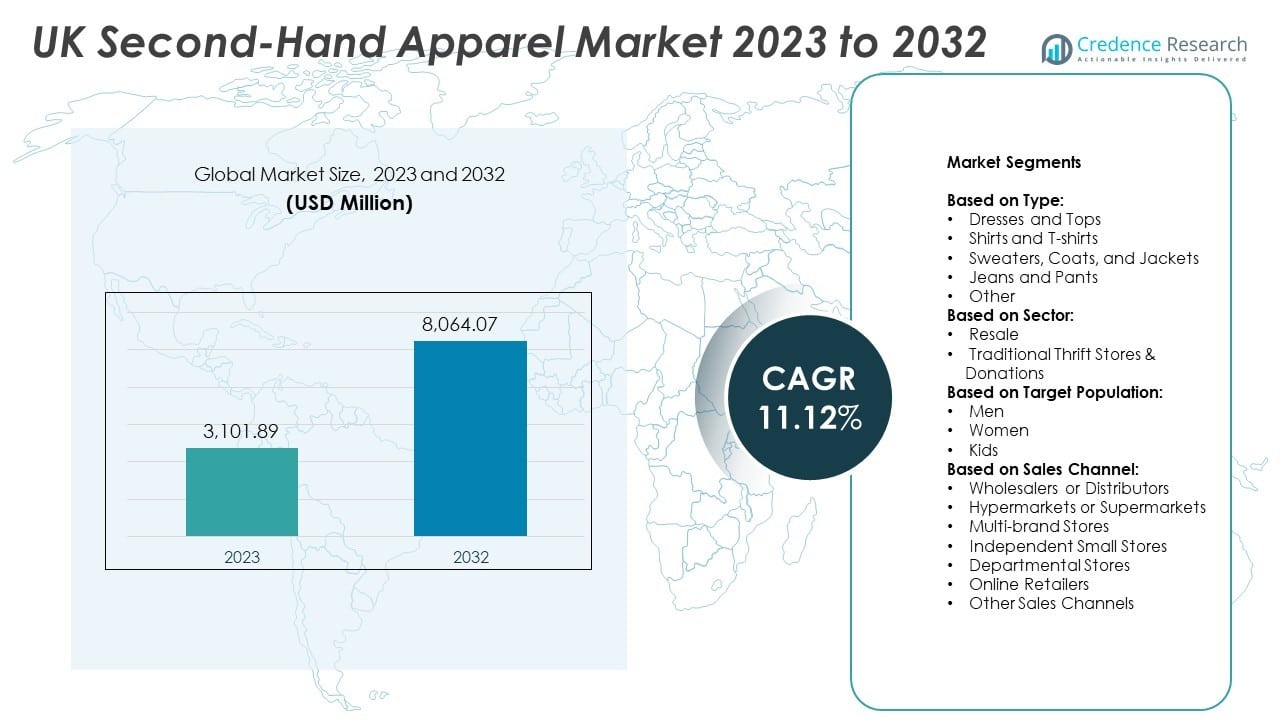
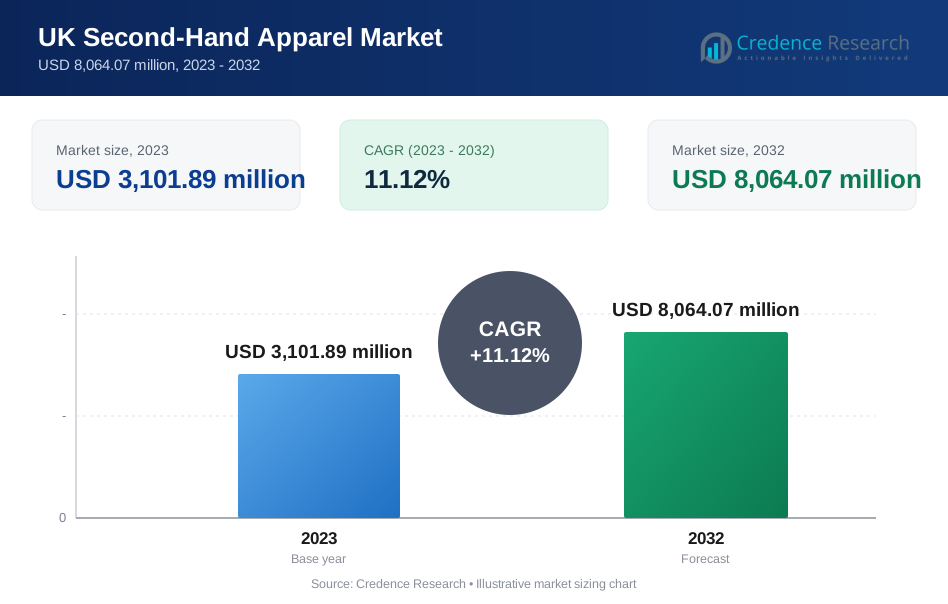
The UK Second-Hand Apparel Market size was valued at USD 3,101.89 million in 2023 and is anticipated to reach USD 8,064.07 million by 2032, expanding at a CAGR of 11.12% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Second-Hand Apparel Market Size 2024 | USD 3,101.89 Million |
| UK Second-Hand Apparel Market, CAGR | 11.12% |
| UK Second-Hand Apparel Market Size 2032 | USD 8,064.07 Million |
The UK Second-Hand Apparel market advances through strong drivers and evolving trends that reshape consumer behavior. Rising sustainability awareness and cost-conscious shopping habits push demand for pre-owned clothing, with younger generations embracing resale as a mainstream choice. Digital platforms and mobile applications enhance accessibility, offering authentication services and seamless logistics that build consumer trust. It benefits from economic factors encouraging affordable alternatives to fast fashion, while growing cultural appreciation for vintage and luxury resale adds aspirational appeal.
The UK Second-Hand Apparel market demonstrates strong geographical variation, with urban centers such as London, Manchester, and Edinburgh driving adoption through digital resale platforms, boutique stores, and fashion-conscious populations, while rural areas expand gradually through thrift shops and community-led initiatives. Scotland shows rising interest in vintage and sustainable fashion, supported by younger demographics and local campaigns. Key players shaping the market include Vinted, eBay, and Depop, which dominate online resale activity, alongside Vestiaire Collective that specializes in luxury segments. Their combined presence reinforces accessibility, authenticity, and style diversity, ensuring robust growth across different consumer groups and regional landscapes.
Market Insights
- The UK Second-Hand Apparel market was valued at USD 3,101.89 million in 2023 and is expected to reach USD 8,064.07 million by 2032, growing at a CAGR of 11.12% during the forecast period.
- Market growth is driven by rising consumer preference for sustainable fashion and cost-effective alternatives to fast fashion, supported by younger generations seeking eco-conscious choices.
- Trends highlight the increasing influence of digital resale platforms, mobile applications, and authentication technologies that enhance consumer trust and expand accessibility across diverse demographics.
- Competitive activity is shaped by major players such as Vinted, eBay, Depop, and Vestiaire Collective, which leverage strong online presence, user-friendly platforms, and brand collaborations to capture varied consumer segments.
- Restraints include quality control issues, counterfeit risks in luxury resale categories, and logistical challenges related to returns, storage, and grading of second-hand clothing.
- Regional dynamics show urban areas such as London, Manchester, and Edinburgh leading adoption through strong cultural influence and infrastructure, while rural areas grow steadily via thrift stores, community-driven events, and improving e-commerce reach.
- The market reflects a balanced outlook, with affordability, digital innovation, and sustainability positioning second-hand apparel as a mainstream fashion choice, while addressing operational constraints will be critical for maximizing long-term growth potential.
Market Drivers
Growing Consumer Shift Toward Sustainability and Circular Fashion
The UK Second-Hand Apparel market gains momentum from rising sustainability concerns and the circular economy movement. Consumers prefer pre-owned clothing to reduce waste and extend the lifecycle of garments. Younger generations, especially Gen Z and millennials, are more conscious of ethical fashion choices. It benefits from widespread awareness campaigns highlighting the environmental impact of fast fashion. Major fashion retailers promote second-hand sales through dedicated platforms. The trend aligns with broader societal demand for eco-friendly consumption and transparent sourcing practices.
- For instance, H&M’s “Garment Collecting” initiative collected 20,649 tonnes of textiles in 2023, equivalent to 100 million T-shirts, reinforcing consumer participation in circular fashion.
Digital Platforms and Resale Marketplaces Driving Accessibility
E-commerce platforms and resale marketplaces expand the reach of the UK Second-Hand Apparel market. Online apps, peer-to-peer selling, and dedicated resale portals create convenience and trust among buyers and sellers. It benefits from features such as authentication services, user reviews, and seamless logistics support. Digitalization reduces entry barriers for consumers across age groups. Retailers integrate second-hand options into their mainstream channels to meet demand. The growth of mobile shopping habits strengthens transaction volumes and widens the consumer base.
- For instance, Vinted reported In 2024, Vinted Group delivered consolidated revenue of €813.4 million, a 36% increase.
Price Sensitivity and Economic Factors Encouraging Demand
The UK Second-Hand Apparel market thrives on affordability during economic uncertainty. Consumers adopt pre-owned fashion to balance style aspirations with cost efficiency. It attracts students, families, and budget-conscious shoppers seeking value. Inflation and rising living costs further push demand for cheaper yet quality alternatives. Retailers position second-hand clothing as both a practical and fashionable option. Economic conditions reinforce second-hand purchases as a mainstream choice rather than a niche practice.
Fashion Diversity, Vintage Appeal, and Rapid Style Turnover
The UK Second-Hand Apparel market benefits from strong demand for vintage clothing and unique styles. It offers variety that fast fashion often fails to replicate. Consumers value individuality and distinctiveness in their wardrobes. Vintage collections, luxury resale, and limited-edition pieces gain traction across segments. Celebrity endorsements and social media trends accelerate adoption of second-hand fashion. Style-conscious consumers embrace resale platforms to constantly refresh their collections without overspending.
Market Trends
Integration of Second-Hand Fashion into Mainstream Retail Channels
The UK Second-Hand Apparel market witnesses a significant trend of integration into mainstream retail. Large fashion brands and retailers introduce dedicated resale sections within their stores and online platforms. It creates a hybrid model where consumers can purchase both new and pre-owned clothing in one place. This shift reduces stigma associated with second-hand fashion and drives higher adoption. Partnerships between retailers and resale platforms strengthen market visibility. The strategy aligns with consumer demand for sustainable fashion choices and affordability.
- For instance, Depop generated 85 million transactions in 2024, with 90% of its active users under 26, highlighting how affordability drives adoption among younger consumers.
Technology-Enabled Resale Platforms and Authentication Services
The UK Second-Hand Apparel market evolves rapidly with the support of digital innovations. AI-driven recommendations, blockchain authentication, and secure payment systems enhance trust in resale transactions. It reduces counterfeit risks and assures buyers of product quality. Virtual try-on features and improved logistics systems streamline the customer experience. Mobile apps offering easy listings and instant resale options appeal to younger demographics. These advancements set new standards in consumer convenience and marketplace credibility.
- For instance, Vestiaire Collective added over 250,000 authenticated vintage items to its “Archive Room”, catering to buyers seeking exclusivity and heritage fashion.
Rising Popularity of Vintage and Luxury Resale Categories
The UK Second-Hand Apparel market experiences strong growth in vintage and luxury resale segments. Consumers value exclusivity, craftsmanship, and unique fashion heritage found in older collections. It appeals to style-conscious shoppers seeking individuality beyond mainstream fast fashion. Luxury resale, in particular, benefits from authentication guarantees and premium positioning. Celebrity endorsements and influencer-led promotions elevate the desirability of vintage and designer resale. This trend expands the market beyond cost-conscious buyers to include affluent fashion enthusiasts.
Growing Consumer Awareness of Environmental and Social Impact
The UK Second-Hand Apparel market reflects rising consumer concern over fashion’s environmental footprint. Awareness campaigns highlight textile waste, carbon emissions, and unsustainable production cycles. It motivates consumers to adopt resale practices as a more responsible choice. Schools, universities, and local communities promote second-hand clothing swaps and events. Governmental support for sustainability further encourages widespread acceptance. Social media movements amplify these messages, positioning resale fashion as both ethical and aspirational.
Market Challenges Analysis
Quality Control, Counterfeit Risks, and Consumer Trust Barriers
The UK Second-Hand Apparel market faces challenges related to quality assurance and authenticity. Consumers often express concern about the condition of pre-owned clothing, ranging from wear and tear to hygiene issues. It must address counterfeit risks, especially within luxury resale segments, where fraudulent items undermine trust. Limited standardization in grading systems creates inconsistency and confusion for buyers. Platforms invest in verification technologies, but the cost and complexity remain high. Without strong assurance measures, consumer hesitation can slow the pace of adoption.
Logistical Complexities, Competition, and Perception Constraints
The UK Second-Hand Apparel market encounters difficulties in managing logistics, storage, and returns. Handling varied product conditions requires specialized supply chain processes. It also contends with intense competition from fast fashion brands that deliver low-cost clothing at speed. Consumer perception still poses hurdles, with some demographics associating second-hand clothing with lower status. Regulatory frameworks around waste management and resale taxation add operational pressures for retailers. Balancing affordability, convenience, and sustainable messaging remains a demanding task for the sector.
Market Opportunities
Expansion Through Digital Innovation and New Retail Models
The UK Second-Hand Apparel market holds strong opportunities in digital expansion and integration with mainstream retail. Online platforms supported by AI-driven personalization, blockchain-based authentication, and mobile-first experiences can strengthen buyer confidence. It can also leverage omnichannel strategies where physical stores and digital platforms combine to create seamless resale ecosystems. Retailers have the chance to partner with resale startups, offering consumers both convenience and variety. Subscription-based models and rental services present further avenues for growth. These innovations broaden consumer access while reinforcing sustainable consumption habits.
Rising Acceptance of Sustainable Fashion and Global Resale Growth
The UK Second-Hand Apparel market benefits from growing consumer preference for ethical and environmentally conscious fashion. Rising awareness of textile waste and carbon reduction efforts creates a favorable environment for adoption. It can expand further by targeting premium and luxury resale categories, appealing to affluent buyers seeking authenticity and exclusivity. Export opportunities to international markets also support sector development. Educational campaigns and influencer-led advocacy strengthen public perception of second-hand clothing as aspirational. This positioning enables the market to reach beyond price-sensitive consumers and establish a mainstream cultural presence.
Market Segmentation Analysis:
By Type:
The UK Second-Hand Apparel market demonstrates varied demand patterns across clothing categories. Dresses and tops dominate resale platforms due to their versatility and strong appeal among women. Shirts and T-shirts also maintain steady traction, driven by affordability and unisex popularity. Sweaters, coats, and jackets attract attention in colder seasons, with branded outerwear and vintage pieces commanding premium interest. Jeans and pants show resilience in demand because of durability and timeless fashion relevance. Other categories, such as accessories and specialty wear, contribute niche opportunities, particularly in online marketplaces targeting younger demographics.
- For instance, ASOS Marketplace hosts over 900 independent vintage and second-hand boutiques, listing more than 200,000 apparel items annually across diverse categories.
By Sector:
The UK Second-Hand Apparel market splits between resale platforms and traditional thrift stores and donations. Resale platforms expand rapidly through digital convenience, authentication services, and influencer-driven marketing. It benefits from scalable business models that reach diverse consumer groups through e-commerce and mobile applications. Traditional thrift stores and donations, while longstanding, continue to serve cost-conscious shoppers and socially motivated buyers. They hold strong community engagement but face challenges in logistics and quality assurance. Both segments reinforce the broader market by catering to distinct consumer motivations ranging from affordability to sustainability.
- For instance, Oxfam processed over 14,000 tonnes of donated clothing in 2023, reselling and recycling items to support both sustainability goals and charitable initiatives.
By Target Population:
The UK Second-Hand Apparel market reveals gender and age-based preferences that shape buying behavior. Women account for a significant portion of demand, drawn to fashion diversity, trend cycles, and luxury resale opportunities. Men increasingly adopt resale purchases, particularly in casualwear, jackets, and sportswear categories. Kids’ apparel presents strong growth potential, with parents seeking affordable and sustainable options for rapidly changing wardrobe needs. It also reflects broader consumer acceptance of circular fashion principles across demographics. Each group strengthens the market by contributing unique demand drivers, ensuring steady growth across all population segments.
Segments:
Based on Type:
- Dresses and Tops
- Shirts and T-shirts
- Sweaters, Coats, and Jackets
- Jeans and Pants
- Other
Based on Sector:
- Resale
- Traditional Thrift Stores & Donations
Based on Target Population:
- Men
- Women
- Kids
Based on Sales Channel:
- Wholesalers or Distributors
- Hypermarkets or Supermarkets
- Multi-brand Stores
- Independent Small Stores
- Departmental Stores
- Online Retailers
- Other Sales Channels
Based on the Region:
- Urban Areas
- London
- Scotland
- Rural Areas
Regional Analysis
Urban Areas
Urban areas command a substantial share of 60% in the UK Second-Hand Apparel market, underlining the importance of large metropolitan centers in driving adoption. London, Manchester, Birmingham, and Edinburgh remain the core hubs where resale fashion has become mainstream. The capital city leads with a vibrant resale ecosystem supported by specialized boutiques, large-scale thrift fairs, and strong digital penetration. It thrives on diverse consumer bases, ranging from students and young professionals to luxury buyers seeking authenticated vintage fashion. Urban logistics infrastructure ensures seamless delivery and returns, strengthening trust in online resale platforms. Social media engagement and influencer-driven campaigns amplify second-hand apparel’s appeal, particularly among Gen Z and millennials. The combination of cultural diversity, sustainability awareness, and trend-driven consumer preferences secures the dominance of urban regions.
London
London accounts for 25% of the UK Second-Hand Apparel market, making it the single largest contributor among all regions. The city benefits from being a global fashion capital, where sustainability trends intersect with high consumer spending power. It houses dedicated resale boutiques, charity shops, and online platform headquarters that anchor growth. London’s multicultural environment drives demand for both luxury resale and everyday thrift, creating diversity in supply and demand. Events such as vintage pop-ups and collaborations between retailers and charities enhance visibility. Social trends around individuality and authenticity, amplified by digital influencers based in the capital, further reinforce consumer interest. London’s position ensures it remains the strategic growth engine of the national second-hand apparel industry.
Scotland
Scotland contributes 15% to the UK Second-Hand Apparel market, led by cities such as Edinburgh and Glasgow. The region shows strong engagement with vintage fashion and charity-led initiatives. It benefits from university populations and younger consumers who actively seek affordable, sustainable alternatives to fast fashion. It also enjoys growth through independent thrift shops and online resale adoption, supported by increasing logistics reach. Cultural events and local campaigns around sustainability reinforce consumer awareness. Scottish buyers value individuality and affordability, and this combination strengthens the presence of second-hand apparel in the region. Scotland continues to emerge as a key regional market with high potential for long-term expansion.
Rural Areas
Rural areas represent 20% of the UK Second-Hand Apparel market, showing gradual but consistent growth. Consumers rely more heavily on charity shops, donation centers, and local thrift events compared to digital platforms. It faces logistical challenges and limited promotional exposure compared to urban centers, but affordability remains a strong driver of adoption. Parents in rural communities often seek second-hand clothing for kids due to frequent wardrobe changes. The market also benefits from community-driven swaps and sustainability campaigns. Expanding e-commerce access and improving delivery networks are expected to boost rural participation further. Rural regions, though smaller in share, add balance to the overall market by ensuring inclusivity and extending the lifecycle of apparel across the country.
Key Player Analysis
Competitive Analysis
The leading players in the UK Second-Hand Apparel market include Vinted, eBay, Depop, Vestiaire Collective, and Amazon. These companies dominate the sector by leveraging strong digital platforms, diverse product offerings, and consumer-focused strategies that enhance trust and accessibility. Each player addresses distinct market segments, creating a competitive environment that stimulates innovation and customer engagement. One core strength of the competition lies in digital-first strategies. Platforms invest in authentication technologies, mobile-friendly interfaces, and seamless logistics to build credibility and expand reach. Urban consumers, in particular, benefit from these advancements, while rural areas gain gradual access through expanding delivery networks. Competition also intensifies in luxury resale, where authentication and exclusivity are critical. Strategic collaborations with fashion brands and sustainability-driven campaigns further strengthen their influence.Market rivalry fosters constant improvement in user experience, with intuitive search tools, integrated payment systems, and customer protection policies. Price competitiveness, variety in apparel categories, and targeted marketing campaigns reinforce loyalty among younger generations. By aligning affordability with sustainability, these companies succeed in positioning second-hand apparel as a desirable mainstream option. The competitive landscape continues to evolve, ensuring that innovation, consumer trust, and sustainability remain at the forefront of market growth.
Recent Developments
- In March 2025, Vinted’s CEO highlighted the platform’s rapid expansion into luxury fashion resale
- In April 2024, Vestiaire Collective relaunched its vintage collection, adding over 250,000 refreshed items to its archive room.
- In January 2024, the UK-based fashion brand HERA unveiled an innovative integrated platform dedicated to the resale of Second-hand clothing. This initiative marks a significant stride in the brand’s journey towards circular fashion, emphasizing the durability and quality of its products. Unlike many of its peers, HERA chose to develop its own reselling platform rather than leveraging existing third-party sites. This strategic move underscores the brand’s commitment to sustainability and allows it to maintain control over the resale environment, ensuring that its circularity objectives are met.
Market Concentration & Characteristics
The UK Second-Hand Apparel market demonstrates a moderately concentrated structure with a few dominant digital platforms driving the majority of transactions. It is characterized by strong competition among resale-focused companies and traditional marketplaces that increasingly integrate pre-owned fashion. Market leaders leverage technology, authentication services, and seamless logistics to strengthen consumer trust, while smaller players rely on niche offerings and localized community engagement. It reflects a balance between affordability-driven purchases and premium resale categories, appealing to both price-sensitive and style-conscious consumers. The market also shows high adaptability, with platforms expanding services, improving user experience, and aligning with sustainability goals to capture a wider audience.
Report Coverage
The research report offers an in-depth analysis based onType, Sector, Target Population, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily with rising consumer preference for sustainable and affordable fashion.
- Digital platforms will continue to dominate growth through improved technology and user experience.
- Luxury resale categories will gain stronger traction with advanced authentication systems.
- Younger generations will drive adoption through cultural influence and social media engagement.
- Traditional thrift stores will adapt by integrating online channels and expanding community presence.
- Logistics and reverse supply chain systems will evolve to handle increasing resale volumes.
- Partnerships between mainstream retailers and resale platforms will strengthen market penetration.
- Rural regions will witness faster adoption with improving internet access and delivery networks.
- Consumer awareness of environmental impact will further reinforce second-hand purchasing behavior.
- Continuous innovation in resale models such as subscriptions and rentals will diversify market opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Consumer Shift Toward Sustainability and Circular Fashion
Increasing awareness of environmental issues and the desire to reduce textile waste are motivating UK consumers, especially younger generations, to choose second-hand apparel as a sustainable alternative to fast fashion.
Digital Platforms and Resale Marketplaces Driving Accessibility
The proliferation of user-friendly online resale platforms and mobile apps has made buying and selling second-hand clothing more convenient, trustworthy, and accessible, expanding the market to a wider demographic.
Price Sensitivity and Economic Factors Encouraging Demand
Economic uncertainty, inflation, and rising living costs are prompting consumers to seek affordable fashion options, making second-hand apparel an attractive choice for budget-conscious shoppers.
Fashion Diversity, Vintage Appeal, and Rapid Style Turnover
The desire for unique, vintage, and luxury items, as well as the ability to frequently refresh wardrobes without overspending, is fueling demand for second-hand apparel among style-conscious consumers.
Integration of Second-Hand Fashion into Mainstream Retail Channels
Major retailers and brands are incorporating second-hand sections into their stores and online platforms, reducing stigma and increasing the visibility and acceptance of pre-owned fashion among mainstream shoppers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for UK Second-Hand Apparel market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the UK Second-Hand Apparel Market projected to grow between 2025 and 2032?
Which UK Second-Hand Apparel market segment held the largest share in 2023?
What are the primary factors fueling the growth of the UK Second-Hand Apparel market?
Who are the leading companies in the UK Second-Hand Apparel Market?
Which region commanded the largest share of the UK Second-Hand Apparel market in 2023?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Dresses and Tops
- 1.2.2 Shirts and T-shirts
- 1.2.3 Sweaters, Coats, and Jackets
- 1.2.4 Jeans and Pants
- 1.2.5 Other
- 1.3 By Sector
- 1.3.1 Resale
- 1.3.2 Traditional Thrift Stores & Donations
- 1.4 By Sales Channel
- 1.4.1 Online Retailers
- 1.4.2 Departmental Stores
- 1.4.3 Multi-brand Stores
- 1.4.4 Independent Small Stores
- 1.4.5 Wholesalers or Distributors
- 1.4.6 Hypermarkets or Supermarkets
- 1.4.7 Other Sales Channels
- 1.5 By Target Population
- 1.5.1 Men
- 1.5.2 Women
- 1.5.3 Kids
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3,101.89 million → 2032: USD 8,064.07 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Second-Hand Apparel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Second-Hand Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Second-Hand Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Second-Hand Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Second-Hand Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Second-Hand Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UK Second-Hand Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Second-Hand Apparel Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3,101.89 million → 2032: USD 8,064.07 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Second-Hand Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dresses and Tops
- 12.3.7.2 Shirts and T-shirts
- 12.3.7.3 Sweaters, Coats, and Jackets
- 12.3.7.4 Jeans and Pants
- 12.3.7.5 Other
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Sector - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Resale
- 12.4.7.2 Traditional Thrift Stores & Donations
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Online Retailers
- 12.5.7.2 Departmental Stores
- 12.5.7.3 Multi-brand Stores
- 12.5.7.4 Independent Small Stores
- 12.5.7.5 Wholesalers or Distributors
- 12.5.7.6 Hypermarkets or Supermarkets
- 12.5.7.7 Other Sales Channels
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Target Population - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Men
- 12.6.7.2 Women
- 12.6.7.3 Kids
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 UK Second-Hand Apparel Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 UK Second-Hand Apparel Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 UK Second-Hand Apparel Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Vinted
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 eBay
- 17.4 Depop
- 17.5 Vestiaire Collective
- 17.6 Amazon
- 17.7 Etsy
- 17.8 Oxfam
- 17.9 ASOS Marketplace
- 17.10 StockX
- 17.11 Rubylane
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

