
Market Overview
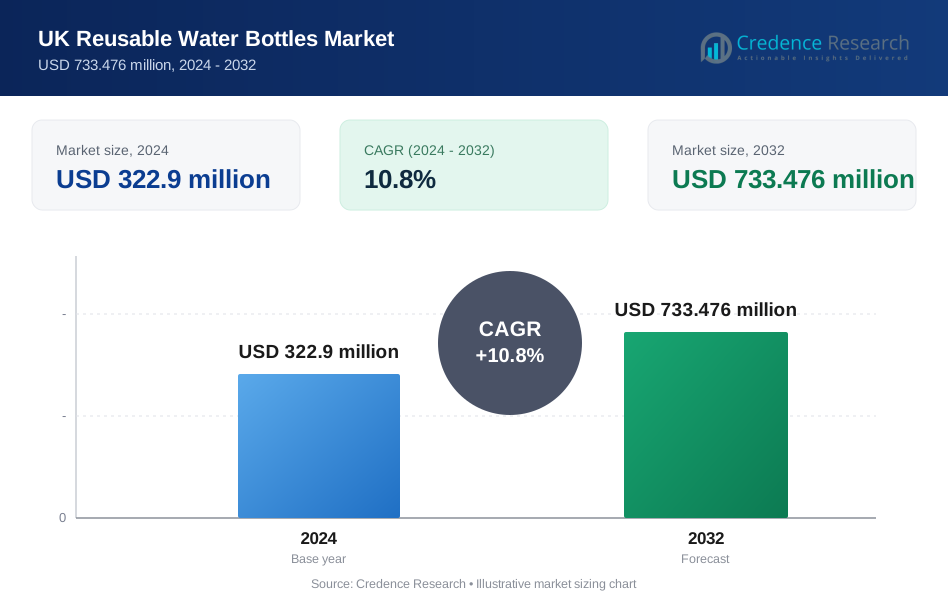
UK Reusable Water Bottle Market size was valued at USD 322.9 million in 2024 and is anticipated to reach USD 733.476 million by 2032, at a CAGR of 10.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Reusable Water Bottle Market Size 2024 | USD 322.9 Million |
| UK Reusable Water Bottle Market, CAGR | 10.8% |
| UK Reusable Water Bottle Market Size 2032 | USD 733.476 Million |
The UK Reusable Water Bottle Market grows on strong drivers such as increasing environmental awareness, rising demand for sustainable and plastic-free alternatives, and a shift toward health-conscious lifestyles. Consumers prioritize durability, safety, and design, prompting brands to innovate with stainless steel, glass, and silicone materials. Trends include the adoption of smart bottles with hydration tracking, thermal insulation, and leak-proof features. Online retail and direct-to-consumer channels expand accessibility, while customization and premium designs attract younger demographics. Corporate initiatives and government campaigns promoting reusable products further reinforce market momentum and long-term growth potential.
The UK Reusable Water Bottle Market demonstrates strong presence across England, Scotland, Wales, and Northern Ireland, with England accounting for the largest market share due to urbanization and higher consumer awareness. Key players such as Tupperware Brands Corporation, SIGG Switzerland AG, CamelBak Products LLC, Klean Kanteen, Contigo, Aquasana Inc., Hydaway, Nalgene, and S’well drive competition through product innovation, sustainable materials, and enhanced distribution networks. It reflects a geographically diverse market shaped by regional preferences and accessibility.
Market Insights
- The UK Reusable Water Bottle Market size was valued at USD 322.9 million in 2024 and is anticipated to reach USD 733.476 million by 2032, growing at a CAGR of 10.8% during the forecast period.
- Rising environmental awareness and preference for sustainable, plastic-free alternatives drive strong consumer adoption.
- Health-conscious lifestyles encourage demand for durable, safe, and ergonomically designed bottles made of stainless steel, glass, and silicone.
- Trends include smart bottles with hydration tracking, thermal insulation, and leak-proof technology to enhance user experience.
- Online retail and direct-to-consumer channels expand accessibility and convenience across urban and regional markets.
- Intense competition among key players like Tupperware, SIGG Switzerland AG, CamelBak, Klean Kanteen, Contigo, Aquasana, Hydaway, Nalgene, and S’well fosters continuous product innovation and premium design offerings.
- Regional growth varies, with England holding the largest market share due to urbanization and higher consumer awareness, while Scotland, Wales, and Northern Ireland show steady adoption driven by accessibility and local initiatives.

Market Drivers
Increasing Consumer Awareness of Environmental Sustainability and Plastic Waste Reduction
The UK Reusable Water Bottle Market benefits from growing consumer awareness of environmental issues and the hazards of single-use plastics. Consumers actively seek alternatives that reduce waste and promote eco-friendly lifestyles. It drives demand for bottles made from stainless steel, glass, and BPA-free plastics. Brands respond by highlighting product durability, recyclability, and low environmental impact. Campaigns by environmental organizations reinforce adoption, emphasizing the long-term benefits of reusable bottles. This heightened consciousness motivates households, offices, and educational institutions to transition from disposable options to sustainable choices. Retailers report stronger sales for products marketed with clear sustainability credentials.
- For instance, Chilly’s Bottles reported preventing over 167 million single-use plastic bottles from entering circulation by 2023 through the sale of its reusable bottles, demonstrating measurable environmental impact and consumer-driven adoption.
Rising Health and Fitness Trends Encouraging Hydration and Daily Water Consumption
Health-conscious consumers increasingly focus on hydration and fitness routines, supporting the UK Reusable Water Bottle Market. It aligns with lifestyle trends emphasizing wellness, exercise, and on-the-go hydration. Manufacturers introduce features like insulated bottles, ergonomic designs, and leak-proof technology to meet consumer expectations. Fitness centers, corporate wellness programs, and outdoor activity enthusiasts promote usage. Product innovations include tracking hydration intake and temperature retention. High engagement through social media and influencer endorsements reinforces consumer adoption. Brands gain competitive advantage by combining health functionality with sustainable materials.
- For instance, Hydro Flask reported selling over 4.2 million insulated bottles globally in 2023, with a significant share driven by fitness enthusiasts who prioritize temperature retention during workouts and outdoor activities, underscoring the link between hydration habits and reusable bottle adoption.
Expansion of Retail Channels and E-Commerce Platforms Enhancing Product Accessibility
Retail growth and online platforms play a significant role in expanding the UK Reusable Water Bottle Market. It allows consumers to access diverse styles, capacities, and customizations easily. E-commerce websites provide detailed product information, customer reviews, and convenient delivery options. Specialty retailers and large supermarket chains expand shelf presence to capture mainstream audiences. Partnerships with lifestyle and sports brands strengthen market visibility. Subscription-based and direct-to-consumer models encourage repeat purchases. Digital tools and promotions further increase brand engagement and consumer loyalty.
Innovation in Product Design and Materials Driving Consumer Interest and Brand Differentiation
Innovation in materials and design drives differentiation in the UK Reusable Water Bottle Market. It stimulates demand through functional features like lightweight construction, temperature retention, and modular components. Companies invest in plant-based plastics, recycled metals, and antimicrobial coatings. Customization options and aesthetic designs cater to lifestyle preferences. Market players highlight technological achievements in durability and safety standards. Awards and certifications for sustainable design reinforce brand credibility. Continuous innovation sustains consumer interest and supports long-term market growth.
Market Trends
Growing Popularity of Smart and Technology-Integrated Water Bottles
The UK Reusable Water Bottle Market witness’s strong adoption of smart and technology-enhanced products. It combines hydration tracking, temperature monitoring, and connectivity features to meet consumer demands for functional convenience. Brands introduce Bluetooth-enabled bottles that sync with mobile applications to record water intake. Fitness enthusiasts and office professionals increasingly prefer these innovations to maintain daily hydration goals. Manufacturers emphasize battery efficiency, durability, and leak-proof designs. Consumer reviews highlight ease of use and enhanced health benefits, reinforcing market acceptance. Retailers report higher engagement with smart bottle collections in both online and offline channels.
- For instance, HidrateSpark announced in 2023 that it had sold over 2 million smart bottles worldwide, each equipped with Bluetooth connectivity and an LED sensor that tracks water intake through a mobile app, highlighting the measurable growth of technology-integrated hydration solutions.
Expansion of Customized and Personalized Water Bottle Offerings
Personalization drives consumer engagement in the UK Reusable Water Bottle Market. It encourages brands to offer bespoke designs, color options, and engraved logos for corporate or individual use. Companies deploy advanced printing and etching techniques to ensure durability and aesthetic appeal. Customized bottles appeal to gifting, promotional campaigns, and lifestyle branding. Consumers respond positively to unique and exclusive options, increasing brand loyalty. E-commerce platforms facilitate easy selection and order customization. Retailers capitalize on personalization trends to differentiate offerings in a competitive market.
- For instance, S’well reported producing over 500,000 customized bottles in 2023 for corporate gifting and promotional campaigns, with demand led by engraved logos and limited-edition designs, reflecting the growing influence of personalization in consumer purchasing decisions.
Rising Adoption of Eco-Friendly and Recycled Materials
Sustainability trends dominate the UK Reusable Water Bottle Market. It motivates manufacturers to use stainless steel, recycled plastics, bamboo, and glass to minimize environmental impact. Companies highlight durability, non-toxicity, and recyclability in product promotion. Consumers increasingly prioritize brands that demonstrate responsible sourcing and production practices. Campaigns by environmental organizations reinforce sustainable consumption patterns. Packaging and supply chain transparency further enhance market credibility. The emphasis on eco-conscious materials strengthens consumer trust and long-term adoption.
Integration of Lifestyle and Fashion Elements to Enhance Appeal
Lifestyle-focused designs influence the UK Reusable Water Bottle Market, blending functionality with fashion. It encourages brands to offer sleek, color-coordinated, and ergonomically designed bottles that complement daily routines. Collaborations with lifestyle influencers and fashion brands increase visibility and aspirational value. Bottles with modular lids, carrying straps, and compact sizes attract urban and active consumers. Product differentiation relies on innovative shapes, finishes, and limited-edition releases. Retailers highlight style alongside performance in marketing campaigns. Consumer demand reflects preference for products that serve both practical and aesthetic purposes.
Market Challenges Analysis
Intense Competition and Price Sensitivity Affecting Market Penetration
The UK Reusable Water Bottle Market faces challenges from intense competition among established brands and new entrants. It pressures manufacturers to differentiate products while maintaining affordability. Low-cost alternatives and generic options increase price sensitivity among consumers. Retailers struggle to balance quality, innovation, and competitive pricing. Brand loyalty remains fragile when performance and aesthetics do not meet expectations. Limited marketing budgets restrict smaller players from achieving wide visibility. Companies must strategically position products to capture discerning and cost-conscious buyers.
Supply Chain Constraints and Material Sourcing Limitations
Supply chain and material sourcing challenges impact the UK Reusable Water Bottle Market. It relies on high-quality stainless steel, BPA-free plastics, and sustainable materials that are sometimes scarce or costly. Fluctuations in raw material availability increase production lead times and operational costs. Transportation delays and import dependencies affect timely delivery to retailers and consumers. Regulatory compliance for materials and safety standards adds complexity. Manufacturers must implement effective inventory and logistics management to mitigate disruptions. Consumer trust depends on consistent product availability and adherence to quality benchmarks.
Market Opportunities
Rising Consumer Awareness and Adoption of Sustainable Lifestyles Driving Market Expansion
The UK Reusable Water Bottle Market benefits from growing consumer awareness of environmental sustainability and plastic waste reduction. It encourages households and workplaces to shift from single-use bottles to durable alternatives. Brands can capitalize on increasing demand for eco-friendly materials, innovative designs, and customizable features. Educational campaigns by environmental organizations further stimulate interest and adoption. Corporate partnerships promoting sustainability initiatives expand reach to broader audiences. Retailers gain opportunities to introduce loyalty programs and subscription models. Product innovation aligned with health-conscious and eco-conscious trends strengthens market appeal.
Technological Advancements and Product Diversification Creating New Growth Avenues
Technological innovation offers significant opportunities in the UK Reusable Water Bottle Market. It drives the development of smart bottles with hydration tracking, temperature control, and app connectivity. Companies can explore advanced materials like antimicrobial coatings and lightweight metals to enhance usability and durability. Collaborations with fitness and wellness brands open new distribution channels and customer segments. Seasonal and limited-edition designs encourage repeat purchases and brand engagement. Expansion into corporate gifting, promotional merchandise, and travel accessories broadens market penetration. Continuous product differentiation ensures long-term competitiveness and consumer loyalty.
Market Segmentation Analysis:
By Material
The UK Reusable Water Bottle Market is segmented by material, including plastic, stainless steel, glass, silicone, and others. Plastic bottles maintain strong demand due to their lightweight nature and affordability, appealing to students and travelers. Stainless steel bottles attract consumers seeking durability, thermal insulation, and long-term value. Glass bottles target health-conscious buyers who prioritize purity and chemical-free hydration, often favored in home and office settings. Silicone bottles offer flexibility and portability, catering to outdoor enthusiasts and fitness users. Other materials, including bamboo composites and hybrid blends, address niche preferences for eco-friendly and innovative designs. Each material segment reflects consumer priorities for safety, usability, and sustainability, influencing brand strategies and product development.
- For instance, Nalgene reported producing over 2 million BPA-free plastic bottles in 2023, specifically targeting students and outdoor users with durable, lightweight designs.
By Distribution Channel
The UK Reusable Water Bottle Market distributes products through supermarkets and hypermarkets, specialty stores, convenience stores, and online channels. Supermarkets and hypermarkets provide widespread availability and exposure, enabling impulse purchases and bulk sales. Specialty stores focus on premium, eco-friendly, and innovative designs, offering expert guidance to informed buyers. Convenience stores cater to immediate needs and on-the-go consumers, particularly in urban locations. Online channels dominate growth by providing extensive assortments, product comparisons, and direct-to-consumer access across the country. E-commerce platforms enhance market penetration into Tier II and Tier III cities, supported by fast delivery and flexible return policies. Each distribution channel shapes consumer engagement, brand visibility, and purchasing behavior, making strategic channel management essential for sustained growth.
- For instance, Tesco reported selling over 1.5 million reusable water bottles across its UK stores in 2023, with strong demand for stainless steel and BPA-free plastic models, demonstrating the significant role of large retail chains in driving market accessibility.
Segments:
Based on Material:
- Plastic
- Stainless Steel
- Glass
- Silicone
- Others
Based on Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Stores
- Convenience Stores
- Online
Based on the Geography:
- England
- Scotland
- Wales
- Northern Ireland
Regional Analysis
England
England commands the largest share of the UK Reusable Water Bottle Market, holding 45% of the overall market. It leads due to high urban population density, strong environmental awareness, and widespread retail infrastructure. Consumers increasingly prefer reusable options in workplaces, educational institutions, and fitness centers, driving consistent adoption. Brands actively target metropolitan areas such as London, Manchester, and Birmingham through premium product launches and extensive retail presence. Corporate wellness programs and government campaigns promoting sustainability further stimulate demand. The proliferation of online retail platforms also enhances accessibility, allowing consumers to compare products, read reviews, and make informed purchases. England’s dominance highlights its critical role in shaping market trends and influencing brand strategies nationwide.
Scotland
Scotland holds 20% of the UK Reusable Water Bottle Market, supported by rising environmental consciousness and outdoor lifestyle preferences. Residents demonstrate strong adoption of eco-friendly hydration solutions, particularly in cities like Edinburgh and Glasgow. Retail channels, including specialty stores and supermarkets, actively stock reusable bottles, while outdoor and sports retailers target consumers engaged in hiking, cycling, and water sports. Local initiatives promoting zero-waste lifestyles and school programs encouraging sustainable habits contribute to market growth. The presence of environmentally responsible manufacturers and distributors further reinforces consumer trust. Scotland’s steady market share reflects a combination of lifestyle-driven consumption and proactive regional policies supporting sustainability.
Wales
Wales accounts for 15% of the UK Reusable Water Bottle Market, driven by rising awareness of plastic pollution and health-conscious consumption. Urban centers such as Cardiff and Swansea exhibit higher adoption rates, influenced by active participation in environmental campaigns and community sustainability projects. Retailers, including supermarkets and online platforms, expand distribution to meet growing demand for convenient and durable reusable bottles. Fitness centers, educational institutions, and workplaces increasingly encourage sustainable hydration practices. Brands capitalize on localized marketing efforts and collaborations with regional organizations to enhance visibility. Wales’ market growth reflects both consumer commitment to sustainability and targeted regional strategies.
Northern Ireland
Northern Ireland represents 10% of the UK Reusable Water Bottle Market, with growth driven by rising interest in eco-friendly lifestyles and urban retail expansion. Consumers in Belfast and Derry actively choose reusable bottles for personal, professional, and recreational use. Retail penetration, particularly through online stores and specialty outlets, facilitates product accessibility. Environmental awareness campaigns in schools and communities promote behavioral changes, encouraging sustainable consumption patterns. Smaller local brands and distributors play a vital role in catering to regional preferences while supporting national sustainability initiatives. Northern Ireland’s market share emphasizes the increasing relevance of environmentally responsible products across all UK regions.
Key Player Analysis
- S’well
- SIGG Switzerland AG, GmbH
- Nalgene
- Hydaway
- CamelBak Products, LLC
- Contigo
- Tupperware Brands Corporation
- Klean Kanteen
- Aquasana Inc.
Competitive Analysis
The UK Reusable Water Bottle Market players such as S’well, SIGG Switzerland AG, GmbH, Nalgene, Hydaway, CamelBak Products, LLC, Contigo, Tupperware Brands Corporation, Klean Kanteen, and Aquasana Inc. The UK Reusable Water Bottle Market experiences intense competition driven by product innovation, sustainability, and expanding consumer access. It requires continuous improvement in materials, design, and functionality to meet evolving consumer preferences. Brands compete on durability, temperature retention, ergonomic design, and eco-friendly credentials to maintain market relevance. The market emphasizes the introduction of BPA-free, stainless steel, glass, and collapsible bottles that enhance convenience and portability for daily use and outdoor activities. Technological integration, such as smart caps, tracking hydration, and filtration systems, further differentiates offerings. Distribution strategy plays a critical role, with online platforms, specialty stores, and large retail chains serving as key channels for growth. Strong focus on environmental responsibility, including recyclable materials and closed-loop programs, drives brand perception and customer loyalty. Competitive intensity encourages continual development of premium features, user-friendly designs, and sustainable solutions, ensuring the market remains dynamic and responsive to consumer demand.
Recent Developments
- In March 2025, the global reusable water bottle market size was estimated at USD 10.17 billion in 2025, with continuous growth driven by environmental awareness, health concerns about single-use plastics, and technological advances such as smart hydration tracking, UV sterilization, and temperature regulation.
- In March 2025, CamelBak has expanded its Thrive Collection with two new reusable bottle models-Thrive Flip Straw and Thrive Chug. These bottles feature leak-proof caps, durable designs, and are made with vacuum stainless steel or Tritan Renew plastic.
- In June 2025, Pyrex has launched a unique glass water bottle that stands out from brands like Stanley, Owala, and Yeti. The bottles feature color-changing designs when filled with cold water, adding a fun visual element.
- In February 2023, SIGG Switzerland AG took part in the ABN AMRO Open tennis tournament to provide all players with reusable drinking bottles which took place at Rotterdam Ahoy in the Dutch city of Rotterdam.
Market Concentration & Characteristics
The UK Reusable Water Bottle Market demonstrates a moderately fragmented structure with several established brands and emerging players competing across material types, designs, and price points. It exhibits high product differentiation, driven by features such as insulation, spill-proof caps, collapsibility, and eco-friendly materials. Market concentration varies by distribution channel, with supermarkets and hypermarkets hosting a broader range of mass-market options, while specialty stores and online platforms offer premium and innovative designs. Consumer preference emphasizes durability, sustainability, and convenience, encouraging companies to adopt environmentally responsible materials such as stainless steel, glass, and BPA-free plastics. Regional consumption patterns influence product availability, with urban areas showing higher adoption of premium and technologically advanced bottles. The market reflects rapid innovation cycles, where new designs and features attract brand loyalty and repeat purchases. Competitive pressure compels companies to maintain strong branding, invest in marketing initiatives, and enhance customer engagement. It relies heavily on both offline retail presence and expanding e-commerce penetration to reach diverse demographic segments.
Report Coverage
The research report offers an in-depth analysis based on Material, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK Reusable Water Bottle Market will continue expanding due to growing environmental awareness.
- Consumers will increasingly prefer bottles made from sustainable and recyclable materials.
- Innovation in thermal insulation and leak-proof designs will drive product differentiation.
- Online retail channels will capture larger market share through convenience and variety.
- Urban adoption of premium and technologically enhanced bottles will accelerate.
- Brands will invest in personalization and customizable designs to attract younger consumers.
- Integration of smart features, such as hydration tracking, will gain traction.
- Corporate and institutional partnerships will promote bulk adoption in workplaces and schools.
- Marketing strategies will focus on health, wellness, and eco-conscious messaging.
- The market will witness consolidation as key players strengthen their portfolios and distribution networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for UK Reusable Water Bottle Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the UK Reusable Water Bottle Market projected to grow between 2025 and 2032?
Which UK Reusable Water Bottle Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the UK Reusable Water Bottle Market?
Who are the leading companies in the UK Reusable Water Bottle Market?
Which region commanded the largest share of the UK Reusable Water Bottle Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 322.9 million → 2032: USD 733.476 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Reusable Water Bottles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Reusable Water Bottles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Reusable Water Bottles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Reusable Water Bottles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Reusable Water Bottles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Reusable Water Bottles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UK Reusable Water Bottles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Reusable Water Bottles Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 322.9 million → 2032: USD 733.476 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Reusable Water Bottles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 UK Reusable Water Bottles Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 UK Reusable Water Bottles Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 UK Reusable Water Bottles Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
