
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| United States Corrugated Packaging Market Size 2023 | USD 211,788.96 Million |
| United States Corrugated Packaging Market, CAGR | 3.92% |
| United States Corrugated Packaging Market Size 2032 | USD 288,068.9 Million |
Market Overview
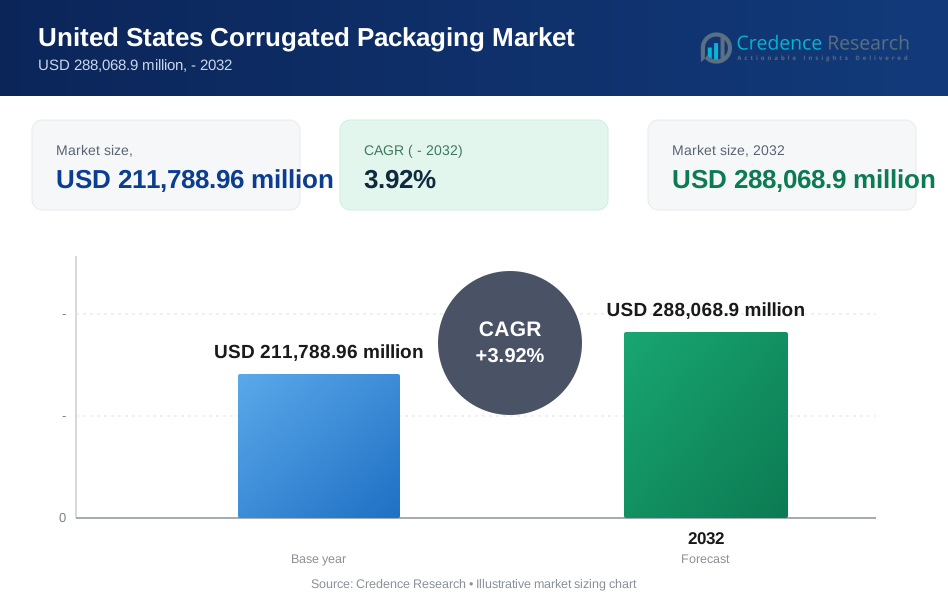
The United States Corrugated Packaging market is projected to grow from USD 211,788.96 million in 2023 to an estimated USD 288,068.9 million by 2032, with a compound annual growth rate (CAGR) of 3.92% from 2024 to 2032. This growth trajectory is fueled by several factors, including the increasing demand for sustainable and eco-friendly packaging solutions. As consumers become more environmentally conscious, there is a growing preference for corrugated packaging, which is recyclable and biodegradable. Additionally, the rise of e-commerce and online shopping has led to a surge in demand for corrugated boxes for shipping and delivery purposes. The convenience and cost-effectiveness of corrugated packaging further contribute to its widespread adoption across various industries such as food and beverage, electronics, and retail.
Market drivers and trends in the United States Corrugated Packaging market are influenced by evolving consumer preferences and technological advancements. One notable driver is the growing trend of customization and personalization in packaging solutions. Companies are increasingly investing in digital printing technologies to offer tailored packaging designs and branding solutions to enhance product visibility and appeal. Moreover, the integration of smart packaging features, such as QR codes and RFID tags, enables better tracking and tracing of products throughout the supply chain, enhancing efficiency and security. Furthermore, the shift towards lightweight and durable packaging materials to minimize shipping costs and reduce environmental impact is driving innovation in the corrugated packaging industry.
Geographical analysis reveals that the United States Corrugated Packaging market is dominated by key players such as International Paper Company, WestRock Company, Georgia-Pacific LLC, and Packaging Corporation of America. These companies hold significant market shares and are actively involved in strategic initiatives such as mergers and acquisitions, product innovations, and geographic expansions to strengthen their foothold in the market. Additionally, regional factors such as population growth, urbanization, and industrial development influence the demand for corrugated packaging across different states. As the market continues to evolve, collaboration between key players and industry stakeholders is essential to address emerging challenges and capitalize on growth opportunities in the United States Corrugated Packaging market.
Market Drivers
E-commerce Boom and Demand for Sustainable Packaging Solutions:
The exponential growth of e-commerce platforms has significantly impacted the demand for corrugated packaging in the United States. As consumers increasingly turn to online shopping for convenience and accessibility, the need for durable and secure packaging materials has surged. For instance, it’s estimated that in 2023, over 90% of internet users in the United States made at least one purchase online. Corrugated packaging, renowned for its strength and versatility, has emerged as the packaging material of choice for shipping and delivering goods purchased online. Moreover, the heightened awareness of environmental sustainability has further propelled the adoption of corrugated packaging. With its recyclability and biodegradability, corrugated packaging aligns with eco-conscious consumer preferences, driving its widespread usage across various industries.
Customization and Personalization Trends:
The rising trend of customization and personalization in packaging solutions has reshaped the landscape of the corrugated packaging market. Companies are increasingly leveraging digital printing technologies to offer tailor-made packaging designs that reflect their brand identity and resonate with their target audience. As an example, a recent study found that nearly 80% of consumers are more likely to purchase from a brand that offers personalized experiences. Customized corrugated packaging not only enhances brand visibility but also fosters consumer engagement and loyalty. Furthermore, advancements in printing technologies enable cost-effective short print runs, allowing businesses to adapt quickly to changing market demands and consumer preferences. As customization continues to gain momentum, corrugated packaging manufacturers are poised to capitalize on this trend by offering innovative and flexible packaging solutions.
Focus on Lightweight and Durable Packaging Materials:
In an era marked by sustainability concerns and cost optimization strategies, there is a growing emphasis on lightweight and durable packaging materials. For instance, the transportation sector has seen a significant reduction in fuel consumption and carbon emissions due to the use of lightweight corrugated packaging. Corrugated packaging, characterized by its lightweight yet robust structure, addresses these dual imperatives effectively. Its inherent strength-to-weight ratio not only ensures product protection during transit but also reduces shipping costs and carbon emissions. Moreover, advancements in corrugated board manufacturing techniques have led to the development of high-performance materials that offer enhanced strength and durability while minimizing material usage. As businesses strive to minimize their environmental footprint and streamline their logistics operations, the demand for lightweight and durable corrugated packaging is poised to escalate further.
Integration of Smart Packaging Technologies:
The integration of smart packaging technologies is revolutionizing the corrugated packaging landscape, offering unprecedented opportunities for innovation and efficiency. Smart packaging features, such as QR codes, RFID tags, and NFC sensors, enable real-time tracking and tracing of products throughout the supply chain. By providing valuable insights into product location, condition, and authenticity, smart packaging enhances transparency, security, and consumer trust. Moreover, smart packaging facilitates interactive brand experiences, enabling consumers to access product information, promotions, and loyalty rewards directly from the packaging. As businesses increasingly recognize the transformative potential of smart packaging, investments in research and development are expected to drive the proliferation of intelligent corrugated packaging solutions in the United States market.
Market Trends
Sustainable Packaging Solutions:
One of the prominent trends in the corrugated packaging market is the increasing focus on sustainability. For instance, a recent survey showed that nearly 70% of consumers in the United States consider the environmental impact of product packaging before making a purchase. With growing environmental concerns, consumers are demanding eco-friendly packaging options. Corrugated packaging, being recyclable and biodegradable, aligns well with this trend. Manufacturers are investing in sustainable practices, such as using recycled fibers and water-based inks, to reduce the environmental impact of their packaging solutions. Furthermore, initiatives such as the Sustainable Packaging Coalition's How2Recycle label are driving awareness and encouraging consumers to recycle corrugated packaging effectively.
E-commerce Packaging Optimization:
The exponential growth of e-commerce has led to a surge in demand for corrugated packaging tailored for online shipments. Packaging optimization is a key trend as companies seek to minimize shipping costs while ensuring product protection. As an example, it’s estimated that the average e-commerce package contains about 40% empty space. Customized corrugated packaging solutions, including right-sized boxes and innovative cushioning materials, are being developed to optimize space utilization and reduce material waste. Additionally, e-commerce retailers are exploring sustainable packaging alternatives, such as corrugated mailers and padded envelopes, to enhance customer experience and reduce packaging waste.
Digital Printing Technology:
Digital printing technology is revolutionizing the corrugated packaging industry by offering cost-effective customization and personalization options. With digital printing, companies can create vibrant, high-quality graphics and designs on corrugated packaging, enhancing brand visibility and consumer engagement. For instance, it’s estimated that digital printing can reduce lead times by up to 50% compared to traditional printing methods. Short print runs and rapid prototyping capabilities enable businesses to respond quickly to market trends and customer preferences. Moreover, digital printing reduces lead times and production costs compared to traditional printing methods, making it an attractive option for corrugated packaging manufacturers.
Smart Packaging Integration:
The integration of smart packaging technologies is gaining momentum in the corrugated packaging market, enabling enhanced functionality and connectivity. RFID tags, NFC sensors, and QR codes are being incorporated into corrugated packaging to enable real-time tracking, authentication, and interactive consumer experiences. Smart packaging solutions provide valuable data insights into product lifecycle management, supply chain optimization, and consumer behavior, driving operational efficiencies and brand differentiation. As the Internet of Things (IoT) ecosystem expands, the adoption of smart packaging in the United States is expected to accelerate, offering new opportunities for innovation and value creation.
Health and Safety Considerations:
In light of the COVID-19 pandemic, health and safety considerations have become paramount in the packaging industry. Corrugated packaging materials are inherently hygienic and provide a protective barrier against contaminants, making them ideal for packaging food, pharmaceuticals, and other essential goods. Manufacturers are implementing stringent hygiene protocols and investing in antimicrobial coatings to ensure product safety and compliance with regulatory standards. Additionally, tamper-evident and secure packaging solutions are being developed to safeguard products from tampering and counterfeiting risks.
Collaborative Supply Chain Partnerships:
Collaborative partnerships across the corrugated packaging supply chain are fostering innovation and driving market growth. From raw material suppliers to packaging manufacturers and end-users, stakeholders are collaborating to develop sustainable, efficient, and cost-effective packaging solutions. Joint research and development initiatives, shared best practices, and supply chain transparency initiatives are enabling continuous improvement and value creation. By leveraging collective expertise and resources, stakeholders in the United States Corrugated Packaging market are poised to address evolving market dynamics and customer requirements effectively.
Market Restraints and Challenges
Rising Raw Material Costs:
Fluctuations in raw material costs, particularly those of paper and cardboard, present a significant challenge for corrugated packaging manufacturers. Volatility in pulp prices, influenced by factors such as supply-demand dynamics, currency fluctuations, and regulatory changes, directly impacts production costs and profit margins. Moreover, the increasing demand for sustainably sourced fibers and recycled content adds complexity to the supply chain and may further exacerbate cost pressures. To mitigate the impact of rising raw material costs, manufacturers must adopt efficient procurement strategies, invest in alternative fiber sources, and optimize production processes to enhance cost competitiveness.
Competitive Pressure and Industry Consolidation:
The corrugated packaging market in the United States is characterized by intense competition and industry consolidation, posing challenges for smaller players and new entrants. Large packaging conglomerates dominate the market, leveraging economies of scale, advanced technology, and extensive distribution networks to gain market share and pricing power. As a result, smaller manufacturers face challenges in competing on price, innovation, and service quality. Furthermore, industry consolidation through mergers and acquisitions may lead to reduced competition, limiting choice and innovation in the market. To navigate competitive pressures, smaller players must focus on niche markets, differentiate their offerings through innovation or specialization, and explore strategic partnerships to enhance competitiveness.
Regulatory Compliance and Environmental Regulations:
Regulatory compliance and evolving environmental regulations present compliance challenges for corrugated packaging manufacturers. Stringent regulations governing packaging materials, recycling requirements, and sustainability standards impose additional compliance costs and operational complexities. Compliance with regulations such as Extended Producer Responsibility (EPR) schemes and packaging waste directives necessitates investment in recycling infrastructure, waste management systems, and product stewardship initiatives. Moreover, increasing public and regulatory scrutiny of packaging waste and plastic pollution requires proactive measures to minimize environmental impact and promote circularity in the packaging value chain. Corrugated packaging manufacturers must stay abreast of regulatory developments, invest in sustainable practices, and collaborate with industry stakeholders to address environmental challenges effectively.
Technological Disruption and Digital Transformation:
Technological disruption and digital transformation are reshaping the corrugated packaging landscape, posing challenges for traditional manufacturers. Automation, robotics, and digitalization are revolutionizing production processes, enhancing efficiency, and reducing labor costs. However, the adoption of advanced technologies requires significant capital investment, workforce upskilling, and organizational change management. Moreover, the proliferation of e-commerce and online retail channels necessitates rapid adaptation to evolving customer preferences, packaging requirements, and supply chain dynamics. Corrugated packaging manufacturers must embrace digital transformation initiatives, invest in technology infrastructure, and cultivate a culture of innovation to remain competitive in the digital age.
Market Segmentation Analysis
By Product
Corrugated packaging leads the market segment due to its versatility, strength, and eco-friendly characteristics, finding wide applications in shipping, transportation, and retail packaging across various industries. Folding boxboard packaging addresses premium and lightweight packaging needs, especially in sectors like cosmetics, pharmaceuticals, and consumer goods. With its smooth surface, folding boxboard enables high-quality printing and branding, making it well-suited for retail packaging solutions.
By Printing Technique
Lithography printing remains a preferred option for high-volume, high-quality printing on corrugated packaging, offering exceptional color reproduction and image clarity, ideal for branded packaging and promotional materials. Flexography printing, on the other hand, is widely utilized for medium to large print runs due to its cost-effectiveness and rapid production speeds. With its ability to print on various substrates, including corrugated board, flexography ensures good ink adhesion and vibrant colors. Meanwhile, digital printing technology is increasingly embraced in the corrugated packaging market for its flexibility, customization capabilities, and quick turnaround times, facilitating on-demand printing, variable data printing, and short print runs to meet personalized packaging needs and just-in-time production requirements.
By End-User
Corrugated packaging serves diverse end-user segments, including Food & Beverages, where it ensures safe, hygienic, and sustainable packaging for fresh produce, beverages, and processed foods. In the Medical sector, corrugated packaging provides sterile packaging for pharmaceuticals and medical devices, ensuring product integrity and regulatory compliance. Agriculture relies on corrugated packaging for the safe transportation of fresh produce and flowers, while the Industrial segment utilizes custom-designed corrugated containers and pallets for shipping and protecting heavy-duty goods, machinery, and electronics. These varied applications highlight the versatility and reliability of corrugated packaging across different industries.
Segments
Based on Product
- Corrugated Packaging
- Folding Boxboard
Based on Printing Technique
- Lithography
- Flexography
- Digital Printing
Based on End-User
- Food & Beverages
- Medical
- Agriculture
- Industrial
Regional Analysis
West Coast (25%):
The West Coast region of the United States commands a significant share of the corrugated packaging market, accounting for approximately 25% of the total market share. This is attributed to the region's robust manufacturing sector, including technology, aerospace, and agriculture, which drives demand for packaging solutions for shipping and distribution. Additionally, the presence of major metropolitan areas such as Los Angeles and San Francisco fuels consumption of corrugated packaging for retail and e-commerce purposes. Moreover, the region's emphasis on sustainability and eco-conscious consumer base further boosts demand for recyclable and biodegradable corrugated packaging solutions.
Northeast (20%):
The Northeast region accounts for approximately 20% of the total market share in the United States Corrugated Packaging market. This region is characterized by a strong presence of consumer goods industries, including retail, electronics, and healthcare, which drive demand for high-quality, custom-designed corrugated packaging solutions. Major metropolitan areas such as New York City and Philadelphia serve as key markets for corrugated packaging, catering to the diverse needs of urban consumers and businesses. Additionally, the region's focus on sustainability and stringent environmental regulations further propels demand for eco-friendly corrugated packaging materials.
South (25%):
The South region holds a significant market share of approximately 25% in the United States Corrugated Packaging market. This is driven by the region's thriving manufacturing and distribution sectors, including aerospace, automotive, and consumer goods industries. Cities like Houston, Atlanta, and Miami serve as major logistics and distribution centers, driving demand for corrugated packaging for shipping and storage purposes. Moreover, the region's growing population and urbanization trends contribute to increased consumption of corrugated packaging for retail and e-commerce applications.
Key players
- International Paper Company
- WestRock Company
- Georgia-Pacific LLC
- Packaging Corporation of America
- Pratt Industries, Inc.
- DS Smith Plc
- PCA Corrugated and Display, LLC
- KapStone Paper and Packaging Corporation
- Smurfit Kappa Group
- Cascades Inc.
Competitive Analysis
Competitive analysis of the United States Corrugated Packaging market reveals intense competition among key players vying for market share and differentiation. Established players such as International Paper Company and WestRock Company dominate the market with their extensive product portfolios, global presence, and strong distribution networks. However, smaller players like Pratt Industries and DS Smith leverage innovation and sustainability to carve out niche segments. Market consolidation through mergers and acquisitions remains a prominent strategy to strengthen market position and expand geographic reach. Additionally, investments in digital printing technology and smart packaging solutions are driving competitive differentiation and market innovation among corrugated packaging manufacturers.
Recent Developments
In March 2024, DS Smith introduced its DryPack seafood box in North America, displacing non-recyclable expanded polystyrene (EPS) foam boxes. DryPack, a leak-proof, water-resistant, and recyclable box, maintains fish freshness below 40 degrees Fahrenheit (4 degrees Celsius) for over 40 hours in cold chain operations when packed with ice. Notably, DryPack is the sole containerboard seafood box endorsed for air freight by the International Air Transport Association, facilitating safe fresh fish shipments for seafood processors.
In December 2023, DS Smith, a sustainable packaging provider, finalized the implementation of its steam recycling technology, reducing energy consumption by 20% at its Columbia, South Carolina, corrugated packaging facility. This advanced technology enhances productivity by minimizing maintenance downtime, thus accelerating production output.
In February 2022, McKinley Packaging revealed plans to construct a new DFW plant in Lancaster, responding to the surge in demand for corrugated boxes driven by e-commerce growth. After evaluating locations in Louisiana and Oklahoma, McKinley Packaging selected southern Dallas for its new facility.
In February 2022, CBRE announced the establishment of a 500,000-square-foot cardboard box factory in Lancaster, Texas, on behalf of McKinley Packaging. With the exponential rise in e-commerce and direct delivery services, the facility will focus on manufacturing cardboard boxes to meet the escalating demand in the region.
In February 2022, Menasha Packaging, a US-based packaging and merchandising firm, reached an agreement to acquire the assets of Color-Box, a business unit of integrated packaging supplier Georgia-Pacific. Color-Box specializes in manufacturing high graphic corrugated cardboard boxes for e-commerce applications in the United States.
Market Concentration and Characteristics
The United States Corrugated Packaging market exhibits a moderate level of market concentration, characterized by the presence of several large multinational corporations alongside numerous smaller and regional players. Key market players such as International Paper Company, WestRock Company, and Georgia-Pacific LLC dominate a significant portion of the market share, leveraging their extensive product portfolios, global distribution networks, and advanced manufacturing capabilities. Despite the dominance of major players, the market remains dynamic and competitive, with constant innovation, technological advancements, and strategic acquisitions driving growth and differentiation. Additionally, the market is characterized by a growing emphasis on sustainability, with corrugated packaging manufacturers increasingly investing in eco-friendly materials and production processes to meet evolving consumer preferences and regulatory standards.
Report Coverage
The research report offers an in-depth analysis based on Product, Printing Technique and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The future of the United States Corrugated Packaging market will witness increased focus on sustainable innovation, with manufacturers investing in eco-friendly materials, recycling technologies, and circular economy initiatives to minimize environmental impact and meet evolving consumer demands for sustainable packaging solutions.
- The corrugated packaging industry is poised for digital transformation, with the adoption of advanced technologies such as digital printing, automation, and data analytics enabling personalized packaging, efficient production processes, and enhanced supply chain visibility, driving operational efficiency and customer engagement.
- The continued expansion of e-commerce and online retail channels will drive sustained demand for corrugated packaging, as businesses strive to optimize packaging solutions for efficient shipping, minimize environmental footprint, and enhance customer experience through innovative packaging designs and customization options.
- Smart packaging technologies, including RFID tags, NFC sensors, and QR codes, will be increasingly integrated into corrugated packaging solutions, enabling real-time tracking, authentication, and interactive consumer experiences, thereby enhancing supply chain visibility, product safety, and consumer engagement.
- The trend towards customization and personalization in packaging will continue to gain momentum, with corrugated packaging manufacturers leveraging digital printing technologies and innovative design capabilities to offer tailored packaging solutions that reflect brand identity, resonate with consumers, and drive brand loyalty.
- Regulatory compliance and sustainability mandates will shape the future landscape of the corrugated packaging market, with manufacturers focusing on adherence to stringent regulations, certification standards, and eco-labeling requirements to demonstrate commitment to environmental stewardship and gain competitive advantage.
- Collaborative partnerships across the corrugated packaging value chain will foster innovation, knowledge sharing, and supply chain optimization, with stakeholders collaborating on research and development initiatives, sustainability initiatives, and circular economy projects to address industry challenges and drive collective growth.
- The United States Corrugated Packaging market will increasingly participate in the global marketplace, with manufacturers exploring international expansion opportunities, strategic alliances, and market diversification strategies to tap into emerging markets, leverage economies of scale, and mitigate geopolitical risks.
- Consumer education and awareness initiatives will play a crucial role in shaping the future of the corrugated packaging market, with manufacturers, retailers, and industry associations collaborating to promote recycling, sustainable packaging practices, and environmental stewardship among consumers, driving demand for eco-friendly packaging solutions.
- The United States Corrugated Packaging market will demonstrate resilience and adaptability in the face of evolving market dynamics, disruptive technologies, and global challenges, with manufacturers embracing innovation, agility, and continuous improvement to stay ahead of the curve and capitalize on emerging opportunities for growth and differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the United States Corrugated Packaging market in 2023, 2032, and its Compound Annual Growth Rate (CAGR)?
What factors are driving the growth of the United States Corrugated Packaging market?
How does customization impact the corrugated packaging industry?
What role does smart packaging technology play in corrugated packaging?
What are the major challenges faced by corrugated packaging manufacturers?
How does regional analysis affect the United States Corrugated Packaging market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 United States Corrugated Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global United States Corrugated Packaging Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 211,788.96 million → 2032: USD 288,068.9 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 United States Corrugated Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. United States Corrugated Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 United States Corrugated Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 United States Corrugated Packaging Market Drivers
- 3.3 United States Corrugated Packaging Market Restraints & Challenges
- 3.4 United States Corrugated Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 United States Corrugated Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 United States Corrugated Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, United States Corrugated Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 United States Corrugated Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. United States Corrugated Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the United States Corrugated Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 United States Corrugated Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 United States Corrugated Packaging Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 United States Corrugated Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in United States Corrugated Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New United States Corrugated Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global United States Corrugated Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America United States Corrugated Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe United States Corrugated Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific United States Corrugated Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America United States Corrugated Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East United States Corrugated Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa United States Corrugated Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. United States Corrugated Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
