
Market Overview:
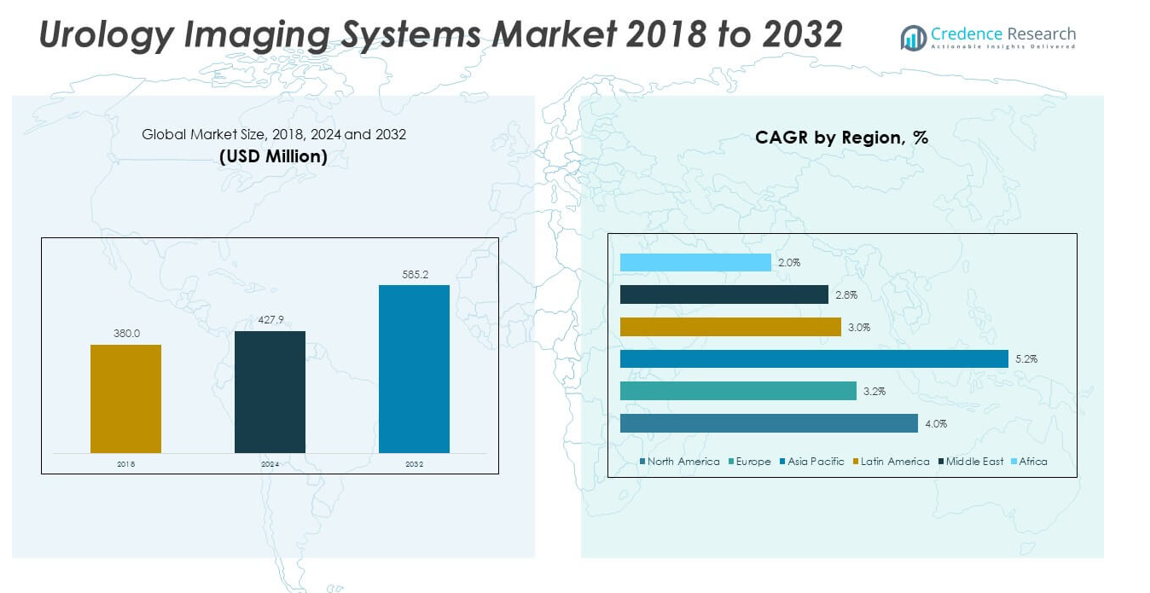
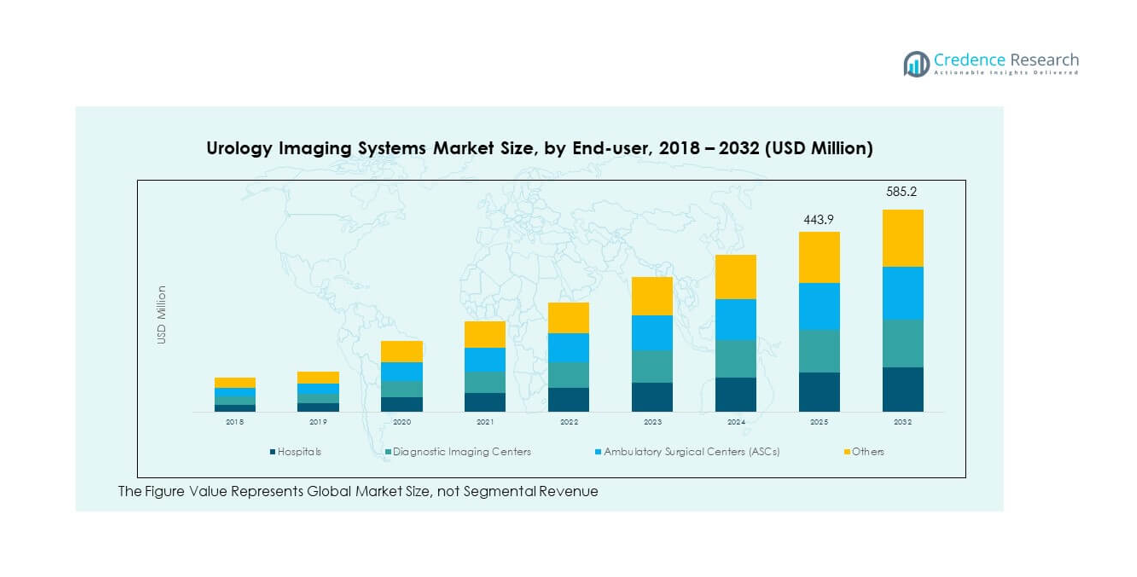
The Urology Imaging Systems Market size was valued at USD 380.0 million in 2018 to USD 427.9 million in 2024 and is anticipated to reach USD 585.2 million by 2032, at a CAGR of 4.0% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Urology Imaging Systems Market Size 2024 | USD 427.9 million |
| Urology Imaging Systems Market, CAGR | 4% |
| Urology Imaging Systems Market Size 2032 | USD 585.2 million |
The growth of the urology imaging systems market is driven by increasing incidences of urological disorders, rising geriatric populations, and technological advancements that enhance diagnostic precision. The adoption of minimally invasive procedures supported by advanced imaging modalities is fueling demand. Furthermore, growing awareness about early disease detection and the integration of AI-powered solutions to improve accuracy and workflow efficiency are accelerating adoption. Rising healthcare expenditures and government initiatives to modernize diagnostic infrastructure further strengthen market expansion across developed and developing economies.
Regionally, North America dominates the urology imaging systems market due to advanced healthcare infrastructure, early technology adoption, and high prevalence of urological conditions. Europe follows closely, driven by strong clinical adoption and supportive reimbursement frameworks. Asia-Pacific is emerging as a high-growth region, supported by rising healthcare investments, expanding patient populations, and increasing access to advanced diagnostic systems in countries such as China and India. Meanwhile, Latin America and the Middle East & Africa are witnessing steady growth, driven by improving healthcare facilities and the gradual integration of modern imaging technologies.
Market Insights:
- The Urology Imaging Systems Market was valued at USD 427.9 million in 2024 and is projected to reach USD 585.2 million by 2032, growing at a CAGR of 0%.
- Rising prevalence of urological disorders and growing geriatric populations are driving demand for advanced diagnostic imaging solutions.
- Increasing preference for minimally invasive procedures strengthens adoption of systems that enhance precision and patient outcomes.
- High costs of advanced imaging systems and limited accessibility in developing regions act as key restraints to market expansion.
- North America leads the market in 2024 due to strong healthcare infrastructure, while Asia Pacific emerges as the fastest-growing region.
- Europe maintains steady growth supported by advanced hospital networks and clinical expertise, though adoption is slower compared to Asia Pacific.
- Latin America, Middle East, and Africa show gradual adoption, driven by healthcare modernization but restrained by affordability challenges.
Market Drivers:
Rising incidence of urological disorders and expanding patient pool worldwide
The prevalence of kidney stones, prostate cancer, bladder disorders, and urinary tract infections is steadily growing, creating consistent demand for advanced imaging solutions. The Urology Imaging Systems Market benefits from this trend as healthcare professionals rely on precision-based diagnostic equipment to manage complex cases effectively. An expanding patient pool in both developed and emerging countries supports continuous adoption of imaging technologies. Governments and health organizations are emphasizing early detection, strengthening the use of advanced diagnostic tools. Aging demographics contribute significantly, with elderly patients at higher risk of urological complications. It gains momentum from growing public awareness about the benefits of timely screening. Clinical requirements for minimally invasive procedures also reinforce the integration of specialized imaging systems. This demand aligns with broader healthcare goals of improved outcomes and reduced hospital stays.
- For example, Siemens Healthineers announced that it has delivered more than 55,555 CT scanners worldwide since 1974, with its SOMATOM portfolio playing a critical role in advancing diagnostic imaging and supporting precision care across multiple clinical applications.
Rapid technological advancements improving diagnostic precision and care delivery
Continuous innovation in imaging technologies has transformed the diagnostic approach in urology. Digital imaging systems, AI-enabled diagnostics, and 3D visualization are enhancing accuracy in complex procedures. The Urology Imaging Systems Market captures this momentum by offering advanced solutions for routine and specialized applications. It evolves with software upgrades, integration of robotics, and real-time analytics that enable greater precision. Hospitals adopt advanced imaging tools to minimize errors and support tailored treatment pathways. Integration with surgical platforms further enhances their utility in minimally invasive procedures. Healthcare providers recognize that new imaging systems improve workflow efficiency and clinical outcomes. It strengthens demand as innovation accelerates adoption among both public and private healthcare sectors. The focus on technological excellence secures a competitive edge for manufacturers.
Growing emphasis on minimally invasive procedures and patient-centric healthcare
Healthcare systems are shifting toward procedures that minimize recovery times, reduce surgical risks, and improve patient comfort. The Urology Imaging Systems Market aligns with this transition by enabling minimally invasive interventions through enhanced imaging support. It contributes to accurate navigation during procedures, supporting quicker recovery and reduced complication rates. Patient preferences increasingly favor hospitals and clinics that invest in these advanced technologies. Physicians also advocate for tools that simplify complex interventions with higher safety margins. The emphasis on quality of care strengthens demand across global healthcare settings. Hospitals and specialty centers consider imaging systems critical for offering advanced urological services. This trend reflects a broader transformation in the healthcare ecosystem where patient-centric approaches guide technology adoption. It ensures rising relevance across diverse applications.
- For instance, GE Healthcare’s OEC 3D mobile C-arm delivers high-quality intraoperative 2D and 3D imaging that supports minimally invasive urology surgeries, enhancing surgical precision, improving workflow efficiency, and enabling better patient recovery outcomes.
Rising healthcare investments and supportive government initiatives globally
Healthcare infrastructure worldwide is expanding rapidly, with governments prioritizing modernization of diagnostic facilities. The Urology Imaging Systems Market gains from these investments as authorities allocate resources toward advanced medical technologies. It benefits from initiatives designed to improve access to high-quality care in both urban and rural areas. Private sector players contribute through partnerships, acquisitions, and product launches to strengthen their global presence. Strong policy frameworks supporting diagnostic innovation improve adoption in developed economies. Developing countries also allocate greater budgets for specialized equipment, widening the reach of modern imaging solutions. Hospitals and clinics find opportunities to integrate these systems into routine practice. It drives demand as institutions focus on strengthening diagnostic accuracy and clinical outcomes. The emphasis on structured healthcare reforms reinforces the market’s future expansion.
Market Trends:
Integration of artificial intelligence and advanced software in imaging workflows
Artificial intelligence has emerged as a defining trend in medical imaging, enabling faster interpretation of complex data sets. The Urology Imaging Systems Market incorporates AI tools that improve workflow efficiency, diagnostic speed, and accuracy. It offers predictive insights and pattern recognition capabilities, empowering physicians with advanced decision-making support. AI-based solutions assist in real-time adjustments during surgical and diagnostic procedures. Hospitals adopt these technologies to reduce error rates and enhance patient outcomes. This trend also reduces the burden on radiologists by streamlining repetitive tasks. The integration of AI with urology imaging ensures that healthcare providers can deliver tailored treatment pathways. It positions vendors to develop differentiated solutions that align with precision medicine. Growing reliance on AI tools continues to reshape the future of diagnostic imaging.
Growing use of hybrid imaging solutions for comprehensive diagnostics
Healthcare providers increasingly demand hybrid imaging systems that combine multiple modalities into a single platform. The Urology Imaging Systems Market benefits from this shift as hospitals seek versatile solutions for broader diagnostic applications. It supports clinicians in obtaining multi-dimensional views, improving diagnosis and treatment planning. Hybrid solutions integrate ultrasound, MRI, and CT-based imaging, allowing efficient assessment of complex conditions. Hospitals prefer these systems because they reduce the need for multiple procedures. Patients also gain from quicker and more accurate results. The trend reflects a move toward consolidation of imaging technologies within healthcare facilities. It enables hospitals to optimize resource use while providing advanced diagnostic capabilities. Growing reliance on hybrid platforms highlights the market’s focus on comprehensive care.
- For example, Philips Healthcare’s Vereos Digital PET/CT, the world’s first fully digital PET/CT solution, delivers enhanced lesion detectability and diagnostic confidence, significantly advancing multi-modality imaging in both oncology and urology care.
Rising demand for portable and mobile imaging solutions in varied healthcare settings
Portability and accessibility are becoming major factors influencing technology adoption in healthcare. The Urology Imaging Systems Market is witnessing a shift toward compact and mobile device that support point-of-care applications. It enables healthcare providers to extend diagnostic services to underserved areas. Portable imaging units are particularly relevant in rural and remote healthcare facilities. Hospitals also integrate mobile devices for quicker diagnostics in emergency and outpatient settings. The preference for systems that combine accuracy with convenience continues to grow. Manufacturers are responding with lightweight, user-friendly models. It creates opportunities for wider deployment across diverse clinical environments. The focus on mobility reflects the industry’s shift toward decentralized and patient-centered care.
Increasing focus on sustainability and eco-friendly medical imaging solutions
Healthcare institutions are adopting greener practices, and imaging technologies are part of this transition. The Urology Imaging Systems Market adapts by developing eco-friendly solutions that minimize energy consumption and waste generation. It reflects growing demand for sustainable products in advanced medical technology sectors. Manufacturers are investing in systems designed to reduce radiation exposure without compromising accuracy. Hospitals also prioritize equipment that aligns with global environmental standards. The shift toward eco-conscious solutions strengthen market differentiation strategies. Patients and healthcare organizations support technologies that combine performance with environmental responsibility. It positions eco-friendly imaging systems as a key factor in procurement decisions. The trend highlights how sustainability is reshaping the competitive landscape.
- For example, Canon Medical’s Aquilion ONE system, equipped with a 320-row detector, enables comprehensive volumetric imaging in a single rotation, supporting accurate assessment of kidney stones, prostate tumors, and urinary tract disorders in the Urology Imaging Systems Market. Its PUREViSION optics enhance efficiency and deliver superior image quality, strengthening its role in advanced urology diagnostics
Market Challenges Analysis:
High cost of advanced imaging systems and limited accessibility in developing regions
Advanced imaging systems require substantial investment, which restricts adoption in cost-sensitive healthcare markets. The Urology Imaging Systems Market faces this challenge as hospitals in low-resource settings struggle to allocate sufficient budgets. It remains a barrier to adoption despite clear clinical benefits. Developing economies often rely on outdated equipment due to financial constraints. Healthcare providers must balance patient needs with budget realities. Limited access to financial assistance and weak reimbursement frameworks add complexity. The disparity between developed and developing markets creates uneven adoption patterns. It highlights the importance of innovative pricing and financing models to ensure broader accessibility.
Complex regulatory landscape and shortage of skilled professionals in diagnostic imaging
Regulatory compliance requirements remain stringent for advanced medical devices. The Urology Imaging Systems Market must address this challenge while introducing innovative products. It often leads to longer approval timelines and higher compliance costs for manufacturers. The shortage of trained healthcare professionals capable of operating advanced systems compounds the problem. Hospitals face delays in deployment due to inadequate training resources. The gap in expertise hinders clinical efficiency and system utilization. Manufacturers are compelled to invest in training and support programs for customers. It reinforces the importance of addressing workforce and regulatory challenges to ensure steady adoption.
Market Opportunities:
Expanding applications in precision medicine and personalized treatment pathways
The global healthcare sector is moving toward precision medicine, creating opportunities for imaging technologies. The Urology Imaging Systems Market aligns with this shift by enabling personalized treatment approaches. It supports accurate diagnostics, real-time monitoring, and tailored therapy planning. Physicians adopt these systems to refine treatment outcomes based on individual patient data. Hospitals use them to strengthen their precision healthcare initiatives. The trend also aligns with rising demand for individualized care solutions. It positions imaging systems as critical enablers of patient-centric healthcare. Vendors gain opportunities by integrating advanced analytics to support personalized diagnostics and therapies.
Growing potential in emerging markets with healthcare infrastructure expansion
Emerging economies are expanding healthcare facilities rapidly, creating significant opportunities for modern imaging solutions. The Urology Imaging Systems Market benefits as governments invest in upgrading diagnostic infrastructure. It provides growth prospects in regions where access to advanced care is improving steadily. Hospitals in Asia-Pacific, Latin America, and Africa adopt new systems to meet growing patient demands. Rising middle-class populations and improved insurance coverage increase adoption rates. Vendors recognize these markets as key to future expansion strategies. It ensures long-term opportunities for manufacturers that adapt to regional needs. Healthcare reforms and private investments further strengthen the growth potential in these regions.
Market Segmentation Analysis:
The Urology Imaging Systems Market is segmented by product, application, and end user, reflecting its diverse role in modern healthcare.
By product, ultrasound systems account for widespread use due to their affordability, non-invasive nature, and portability, making them highly preferred for real-time diagnostics. Conventional radiology systems such as X-ray and fluoroscopy remain relevant for routine imaging, while computed tomography (CT) scanners are vital for advanced visualization of complex urological conditions. Magnetic resonance imaging (MRI) systems deliver high-resolution detail, particularly in soft tissue assessment, while other emerging imaging technologies introduce innovation that expands precision and workflow efficiency.
- For example, Exact Imaging’s ExactVu micro-ultrasound system operates at 29 MHz and delivers approximately 300% higher resolution than conventional ultrasound, enabling real-time visualization of prostate lesions with around 70-micron detail, making it highly applicable within the Urology Imaging Systems Market.
By application, diagnostic imaging dominates the landscape as early detection and accurate assessment of urological disorders remain top clinical priorities. Interventional imaging is expanding rapidly, driven by minimally invasive procedures where guidance during treatment is critical.
- For instance, the Artemis 3D ultrasound–MRI fusion biopsy system, deployed at UC Irvine Health, combines real-time ultrasound with pre-acquired MRI to generate an interactive 3D prostate map, improving lesion targeting and biopsy accuracy in the Urology Imaging Systems Market.
By end user, hospitals hold the largest share owing to their advanced infrastructure and ability to integrate multiple modalities. Diagnostic imaging centers are significant contributors, focusing on specialized imaging services to meet growing demand. Ambulatory surgical centers (ASCs) are gaining traction due to their cost efficiency and convenience for patients seeking faster interventions. Others, including research institutes and specialty clinics, provide additional avenues for adoption. It demonstrates adaptability across diverse healthcare ecosystems, reinforcing its importance in enhancing diagnostic accuracy and improving patient outcomes.
Segmentation:
By Product / Imaging Modality
- Ultrasound Systems
- Conventional Radiology Systems (X-ray, Fluoroscopy)
- Computed Tomography (CT) Scanners
- Magnetic Resonance Imaging (MRI) Systems
- Other Emerging Imaging Technologies
By Application
- Diagnostic Imaging
- Interventional Imaging
By End User
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers (ASCs)
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Urology Imaging Systems Market size was valued at USD 153.3 million in 2018 to USD 170.8 million in 2024 and is anticipated to reach USD 233.2 million by 2032, at a CAGR of 4.0% during the forecast period. North America accounted for 39.9% share of the global market in 2024. The region leads the market due to advanced healthcare infrastructure, strong adoption of minimally invasive procedures, and high prevalence of urological disorders. The Urology Imaging Systems Market here benefits from early integration of innovative modalities, including AI-enabled and robotic-assisted imaging platforms. It grows with favorable reimbursement structures and strong clinical emphasis on precision diagnostics. Leading manufacturers prioritize this region for new product launches and partnerships with hospitals. Research institutions in the U.S. and Canada also drive clinical adoption through trials and validation studies. It secures its position as the dominant regional contributor, reflecting strong patient demand and technology readiness.
Europe
The Europe Urology Imaging Systems Market size was valued at USD 88.2 million in 2018 to USD 94.9 million in 2024 and is anticipated to reach USD 121.6 million by 2032, at a CAGR of 3.2% during the forecast period. Europe represented 22.1% share of the global market in 2024. The region benefits from established healthcare systems and steady demand for diagnostic imaging. The Urology Imaging Systems Market here gains from supportive regulatory frameworks and widespread clinical expertise. It is shaped by growing awareness of early detection and preventive healthcare measures. Germany, France, and the UK lead adoption due to strong hospital networks and technological investments. Eastern Europe shows rising adoption rates, driven by healthcare modernization. Manufacturers strengthen their presence through local collaborations and distribution networks. It continues to maintain steady growth, although slower than North America and Asia Pacific due to mature adoption levels.
Asia Pacific
The Asia Pacific Urology Imaging Systems Market size was valued at USD 93.7 million in 2018 to USD 110.1 million in 2024 and is anticipated to reach USD 165.6 million by 2032, at a CAGR of 5.2% during the forecast period. Asia Pacific contributed 25.7% share of the global market in 2024. The region emerges as the fastest-growing due to expanding healthcare infrastructure, increasing healthcare expenditure, and rising patient populations. The Urology Imaging Systems Market in Asia Pacific benefits from strong demand in China, India, and Japan, where large patient pools drive diagnostic requirements. It gains momentum from government investments in healthcare modernization and accessibility initiatives. Rising middle-class populations increase demand for advanced and affordable diagnostic services. Local manufacturers and global companies both expand aggressively to tap into unmet demand. It strengthens its position as the most dynamic growth hub, offering long-term opportunities for technology adoption and patient-centered solutions.
Latin America
The Latin America Urology Imaging Systems Market size was valued at USD 22.0 million in 2018 to USD 24.6 million in 2024 and is anticipated to reach USD 30.9 million by 2032, at a CAGR of 3.0% during the forecast period. Latin America accounted for 5.7% share of the global market in 2024. The region demonstrates steady adoption of imaging systems, particularly in Brazil and Mexico. The Urology Imaging Systems Market in Latin America benefits from improving healthcare infrastructure and gradual adoption of minimally invasive procedures. It grows with public and private investments, though economic disparities slow uniform adoption. Hospitals in urban areas show stronger demand for advanced modalities, while rural areas face access challenges. Vendors expand presence through partnerships with local distributors and healthcare providers. It maintains gradual growth, supported by rising awareness of diagnostic imaging in urology care.
Middle East
The Middle East Urology Imaging Systems Market size was valued at USD 15.6 million in 2018 to USD 16.5 million in 2024 and is anticipated to reach USD 20.5 million by 2032, at a CAGR of 2.8% during the forecast period. The Middle East represented 3.9% share of the global market in 2024. The region benefits from rising investments in healthcare modernization, particularly in GCC countries. The Urology Imaging Systems Market here grows with demand from private healthcare networks and specialty hospitals. It is influenced by medical tourism in hubs such as the UAE and Saudi Arabia. Advanced hospitals integrate imaging systems to expand minimally invasive care options. Limited access across less-developed economies restrains widespread adoption. Vendors focus on premium segments where purchasing power is high. It sustains moderate growth, largely driven by regional healthcare reforms and technology adoption in urban centers.
Africa
The Africa Urology Imaging Systems Market size was valued at USD 7.2 million in 2018 to USD 11.0 million in 2024 and is anticipated to reach USD 13.3 million by 2032, at a CAGR of 2.0% during the forecast period. Africa held 2.6% share of the global market in 2024. The region experiences limited penetration due to underdeveloped healthcare infrastructure and economic constraints. The Urology Imaging Systems Market in Africa grows at a slower pace, largely supported by South Africa and Egypt. It remains dependent on international aid and government-led healthcare programs to improve diagnostic facilities. High costs restrict the adoption of advanced imaging systems across most countries. Vendors target key hospitals and specialty centers with premium solutions. It shows potential for growth with gradual reforms and increased focus on healthcare investments. Patient demand is rising, though affordability challenges persist across the region.
Key Player Analysis:
- Philips Healthcare
- GE Healthcare
- Siemens Healthineers
- Olympus Corporation
- Guerbet
- Exact Imaging
- Dornier MedTech
- Karl Storz
- Hitachi Healthcare
- Esaote
- Samsung Medison
- Canon Medical Systems
- Mindray Medical
- Stryker
Competitive Analysis:
The Urology Imaging Systems Market is characterized by intense competition among global leaders and specialized regional players. Major companies such as Philips Healthcare, GE Healthcare, Siemens Healthineers, and Olympus Corporation dominate through broad product portfolios and advanced imaging technologies. It strengthens through innovation in ultrasound, CT, MRI, and fluoroscopy systems tailored for urological applications. Mid-sized players including Dornier MedTech, Exact Imaging, and Esaote focus on niche strengths to capture targeted segments. Partnerships, acquisitions, and product launches remain central strategies to expand geographic reach and clinical adoption. The competitive landscape emphasizes technological integration with AI, real-time visualization, and minimally invasive support systems. It maintains a balance between global corporations investing in R&D and smaller companies addressing cost-sensitive markets with flexible solutions.
Recent Developments:
- In August 2025, Royal Philips announced the FDA 510(k) clearance of its latest UroNav system for image-guided navigation in prostate cancer treatment. The updated platform integrates advanced annotation workflow and MRI/ultrasound fusion technology, allowing clinicians to deliver focal therapy procedures with greater precision.
- In July 2025, Philips Healthcare achieved FDA 510(k) clearance for its latest UroNav image-guided navigation system, enhancing prostate cancer care with a new advanced annotation workflow. The platform unifies imaging, biopsy pathology, treatment planning, and 3D guidance using MR-US fusion, enabling clinicians to deliver more precise, minimally invasive focal therapies.
- In June 2025, GE Healthcare launched the bkActiv S ultrasound imaging system, designed to support nonsurgical urologic procedures such as prostate diagnostics and biopsies. The system features prostate volume assist powered by AI for one-click prostate measurements and TruFocus imaging optimization.
- In September 2024, Koelis entered a partnership with DeepHealth to integrate DeepHealth’s AI-powered Prostate software into the Koelis Trinity 3D Ultrasound Platform. This collaboration streamlines prostate MRI interpretation and fusion biopsy guidance, enabling clinicians to leverage AI-enhanced imaging with the Trinity platform.
Market Concentration & Characteristics
The Urology Imaging Systems Market reflects a moderately consolidated structure, with a few multinational corporations holding significant market share while regional firms cater to specific healthcare needs. It exhibits strong barriers to entry due to high capital requirements, strict regulatory compliance, and demand for advanced clinical validation. Competition is shaped by product differentiation, innovation speed, and brand reputation. It demonstrates a mix of mature adoption in developed economies and emerging demand in fast-growing regions, creating a dual growth dynamic for manufacturers. It continues to attract investments in AI-driven platforms and portable imaging technologies. Strategic collaborations between global leaders and local healthcare providers strengthen accessibility and broaden market penetration.
Report Coverage:
The research report offers an in-depth analysis based on product, application, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Urology Imaging Systems Market will advance through stronger integration of AI and machine learning to improve diagnostic precision.
- Demand will rise for portable and point-of-care imaging solutions to serve outpatient and rural healthcare settings.
- Hospitals will continue to prioritize imaging systems that support minimally invasive procedures and faster patient recovery.
- Innovation in hybrid imaging modalities will enhance clinical efficiency by combining multiple diagnostic capabilities.
- Emerging economies will drive growth through expanding healthcare infrastructure and wider patient access to advanced diagnostics.
- Vendors will focus on eco-friendly imaging technologies to align with global sustainability goals.
- Strategic partnerships between global manufacturers and regional distributors will strengthen market penetration.
- Training programs and skill development initiatives will be essential to address workforce gaps in advanced imaging usage.
- Regulatory harmonization will influence product approvals and accelerate time-to-market for new technologies.
- Growing investment in precision medicine will reinforce the role of imaging systems in personalized treatment planning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Urological Disorders and Aging Population
The increasing prevalence of kidney stones, prostate cancer, bladder disorders, and urinary tract infections, coupled with a growing geriatric population, is driving demand for advanced urology imaging systems to support early detection and effective management.
Technological Advancements in Imaging Modalities
Continuous innovation in digital imaging, AI-enabled diagnostics, and hybrid imaging solutions is enhancing diagnostic precision and workflow efficiency, encouraging hospitals and clinics to upgrade to newer, more capable systems.
Shift Toward Minimally Invasive Procedures
The growing preference for minimally invasive urological interventions is fueling adoption of imaging systems that provide real-time, high-resolution visualization, enabling safer procedures and faster patient recovery.
Healthcare Infrastructure Expansion and Government Initiatives
Rising healthcare investments and supportive government policies aimed at modernizing diagnostic infrastructure, especially in emerging markets, are broadening access to advanced imaging technologies and accelerating market growth.
Integration of Artificial Intelligence and Advanced Software
The adoption of AI-powered imaging solutions is improving diagnostic accuracy, reducing interpretation times, and supporting personalized treatment planning, making these systems increasingly attractive to healthcare providers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Urology Imaging Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Urology Imaging Systems Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Urology Imaging Systems Market?
Who are the leading companies in the Urology Imaging Systems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Diagnostic Imaging Centers
- 1.2.3 Ambulatory Surgical Centers (ASCs)
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Diagnostic Imaging
- 1.3.2 Interventional Imaging
- 1.4 By Product / Imaging Modality
- 1.4.1 Ultrasound Systems
- 1.4.2 Conventional Radiology Systems (X-ray, Fluoroscopy)
- 1.4.3 Computed Tomography (CT) Scanners
- 1.4.4 Magnetic Resonance Imaging (MRI) Systems
- 1.4.5 Other Emerging Imaging Technologies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 427.9 million → 2032: USD 585.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Urology Imaging Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Urology Imaging Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Urology Imaging Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Urology Imaging Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Urology Imaging Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Urology Imaging Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Urology Imaging Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Urology Imaging Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 427.9 million → 2032: USD 585.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Urology Imaging Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Diagnostic Imaging Centers
- 12.3.7.3 Ambulatory Surgical Centers (ASCs)
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diagnostic Imaging
- 12.4.7.2 Interventional Imaging
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product / Imaging Modality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ultrasound Systems
- 12.5.7.2 Conventional Radiology Systems (X-ray, Fluoroscopy)
- 12.5.7.3 Computed Tomography (CT) Scanners
- 12.5.7.4 Magnetic Resonance Imaging (MRI) Systems
- 12.5.7.5 Other Emerging Imaging Technologies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Urology Imaging Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Urology Imaging Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Urology Imaging Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Urology Imaging Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Philips Healthcare
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE Healthcare
- 18.4 Siemens Healthineers
- 18.5 Olympus Corporation
- 18.6 Canon Medical Systems
- 18.7 Samsung Medison
- 18.8 Exact Imaging
- 18.9 Dornier MedTech
- 18.10 Esaote
- 18.11 Hitachi Healthcare
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

