
Market Overview
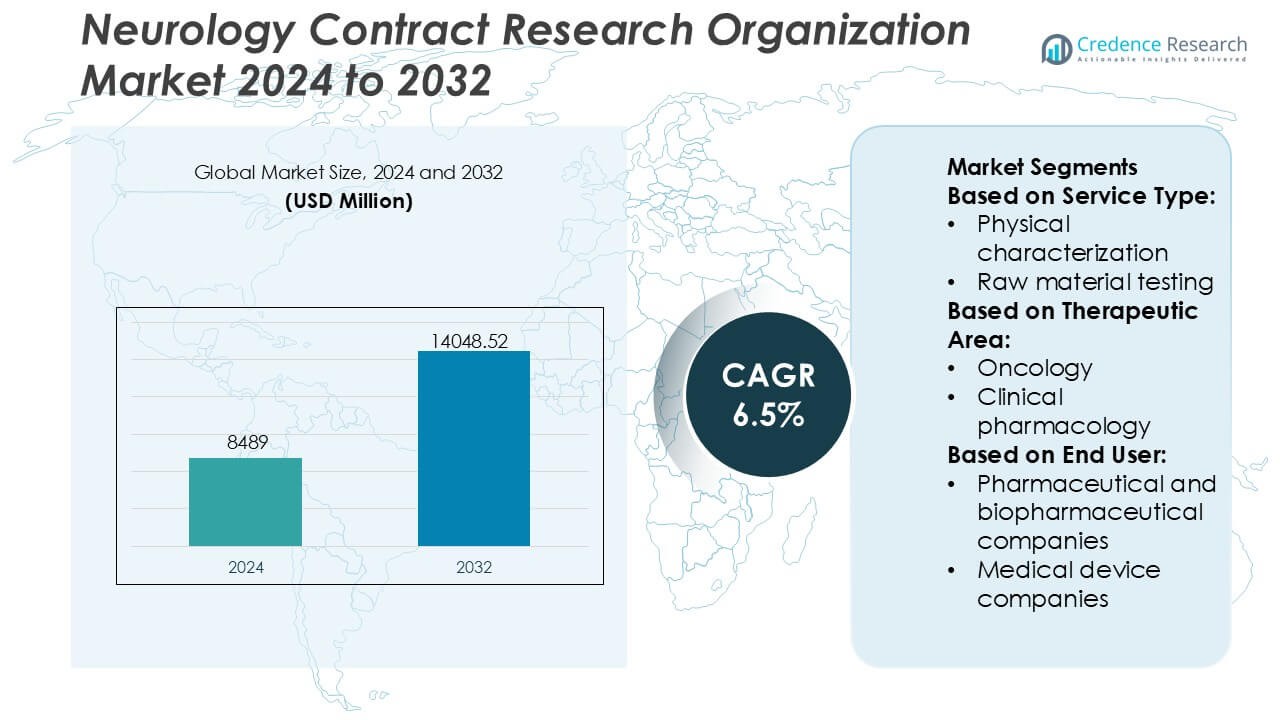
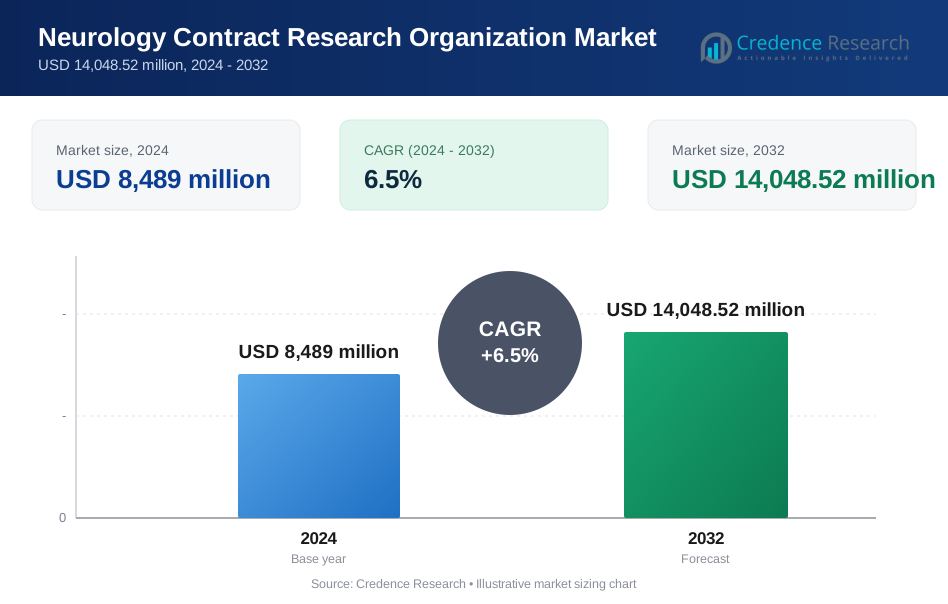
Neurology Contract Research Organization Market size was valued USD 8489 million in 2024 and is anticipated to reach USD 14048.52 million by 2032, at a CAGR of 6.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Neurology Contract Research Organization Market Size 2024 | USD 8489 Million |
| Neurology Contract Research Organization Market , CAGR | 6.5% |
| Neurology Contract Research Organization Market Size 2032 | USD 14048.52 Million |
The Neurology Contract Research Organization market is led by a group of well-established global players that compete through deep neuroscience expertise, integrated service portfolios, and strong global trial execution capabilities. These organizations focus on managing complex neurology studies involving advanced imaging, biomarker-driven endpoints, and long-term follow-up requirements. Competitive positioning depends on scientific specialization, regulatory proficiency, patient recruitment efficiency, and adoption of digital and decentralized trial technologies. Strategic collaborations with pharmaceutical sponsors and academic research centers further strengthen market presence. North America emerges as the leading region with an exact 41% market share, supported by advanced clinical research infrastructure, high neurological disease prevalence, strong R&D investment, and early adoption of innovative trial methodologies, reinforcing its dominance in neurology-focused clinical research outsourcing.
Market Insights
- The Neurology Contract Research Organization Market was valued at USD 8,489 million in 2024 and is projected to reach USD 14,048.52 million by 2032, expanding at a CAGR of 6.5%, driven by rising outsourcing of complex neurology trials.
- Market growth is supported by increasing neurological disease prevalence and demand for specialized services such as advanced neuroimaging, biomarker-based endpoints, and long-duration clinical studies.
- Key trends include growing adoption of decentralized and hybrid trial models, digital biomarkers, and data analytics to enhance patient recruitment, monitoring, and trial efficiency.
- Competitive dynamics center on scientific specialization, integrated service portfolios, regulatory expertise, and strategic collaborations with pharmaceutical sponsors and academic institutions.
- North America leads with an exact 41% market share, supported by advanced research infrastructure and high R&D investment, while service segments related to clinical development and biomarker-driven studies hold dominant shares due to trial complexity.
Market Segmentation Analysis:
By Service Type
By service type, early phase development services emerge as the dominant sub-segment, accounting for an estimated 34% market share in the neurology contract research organization market. This leadership reflects growing outsourcing of first-in-human studies, dose-escalation trials, and early safety assessments for complex neurological compounds. High protocol complexity, stringent regulatory requirements, and the need for specialized neuroimaging, biomarker analysis, and adaptive trial designs drive demand. Sponsors increasingly rely on CRO expertise to shorten development timelines, manage risk, and optimize early decision-making before advancing costly late-stage neurology programs.
- For instance, Boston Scientific Corporation advanced early-phase neuromodulation research through clinical programs supporting its Vercise Deep Brain Stimulation platform, which uses leads with 8 independent contacts and supports stimulation precision at sub-millimeter resolution, with early clinical studies enrolling more than 100 patients to validate safety, targeting accuracy, and device-controlled dose optimization during initial development phases.
By Therapeutic Area
By therapeutic area, neurology itself represents the dominant sub-segment with an estimated 38% market share, driven by rising prevalence of neurodegenerative and neuropsychiatric disorders such as Alzheimer’s disease, Parkinson’s disease, epilepsy, and multiple sclerosis. Drug development in neurology faces high failure rates and complex endpoints, increasing reliance on CROs with deep disease-area expertise. Demand is further supported by growth in gene therapies, biologics, and CNS-targeted small molecules requiring advanced clinical pharmacology, imaging endpoints, and long-duration trials. These factors sustain strong outsourcing across discovery, preclinical, and early clinical neurology programs.
- For instance, MicroVention Inc., a subsidiary of Terumo Corporation, has advanced neurovascular innovation through its LVIS EVO™ stent system. The device features a high-density, braided nitinol structure composed of 16 wires with Drawn Filled Tube (DFT) technology, which includes a platinum core for full-length radiopacity.
By End User
By end user, pharmaceutical and biopharmaceutical companies dominate the market, holding an estimated 69% share, reflecting their extensive pipelines in central nervous system therapeutics. These organizations outsource neurology research to control costs, access specialized scientific capabilities, and manage fluctuating R&D workloads. Increasing focus on rare neurological diseases, precision medicine, and accelerated development pathways strengthens CRO engagement across multiple development stages. While medical device companies and academic institutes contribute to demand through investigator-initiated studies and device trials, large biopharmaceutical sponsors remain the primary drivers of contract research spending in neurology.
Key Growth Drivers
Rising Neurological Disease Burden and Complex Trial Demand
The growing prevalence of neurological disorders such as Alzheimer’s disease, Parkinson’s disease, multiple sclerosis, epilepsy, and rare neurogenetic conditions significantly increases demand for specialized clinical research services. Neurology trials require complex protocols, long study durations, cognitive and functional endpoints, and advanced imaging and biomarker integration. Pharmaceutical and biotechnology companies increasingly rely on neurology-focused CROs to manage these complexities, ensure protocol compliance, and improve patient recruitment and retention. This rising clinical complexity directly drives outsourcing to CROs with dedicated neurological expertise and therapeutic depth.
- For instance, Abbott has demonstrated advanced neurological research capabilities through clinical programs supporting its Proclaim XR spinal cord stimulation system, which delivers targeted neuromodulation using a battery designed to last up to 10 years and supports stimulation waveforms with pulse widths as low as 30 microseconds, with multicenter studies enrolling more than 200 patients to evaluate long-term safety, functional improvement, and device performance in chronic neurological pain management.
Outsourcing Shift Among Pharma and Biotech Sponsors
Pharmaceutical and biopharmaceutical companies continue to expand outsourcing strategies to control costs, accelerate development timelines, and access specialized capabilities. Neurology drug development involves high failure rates and substantial regulatory scrutiny, prompting sponsors to partner with CROs that offer integrated preclinical, clinical, and regulatory services. CROs provide scalable infrastructure, global trial networks, and experienced neuroscience teams that reduce operational risk. This strategic shift toward full-service and functional outsourcing models strongly supports sustained demand growth in the neurology CRO market.
- For instance, Nexstim has strengthened outsourced neurology research through its Navigated Brain Stimulation (NBS) System, which delivers transcranial magnetic stimulation with targeting accuracy below 2 millimeters using individual MRI-based navigation, and has been validated across more than 6,000 patients in clinical and research settings, generating over 120 peer-reviewed publications that support its use in motor mapping, language mapping, and early-phase neurological therapy evaluation.
Advancements in Neuroimaging and Biomarker-Based Research
Rapid adoption of advanced neuroimaging techniques, digital biomarkers, and molecular diagnostics strengthens the role of specialized CROs. Modalities such as functional MRI, PET imaging, EEG analytics, and cerebrospinal fluid biomarkers improve disease stratification and endpoint sensitivity. Neurology CROs increasingly support protocol design, data interpretation, and centralized imaging analysis. These capabilities enhance trial precision and reduce variability, making CRO partnerships essential for sponsors developing disease-modifying neurological therapies and accelerating innovation across the research pipeline.
Key Trends & Opportunities
Expansion of Decentralized and Hybrid Neurology Trials
Decentralized and hybrid clinical trial models are gaining traction in neurology research due to mobility limitations among patients and long follow-up requirements. Remote cognitive assessments, wearable neurological monitoring devices, and tele-neurology visits improve patient participation and data continuity. CROs are investing in digital trial platforms and home-based data collection to support these models. This trend creates opportunities for CROs to differentiate through technology-enabled services while improving enrollment diversity and reducing trial disruption risks.
- For instance, Penumbra, Inc. has advanced technology-enabled neurovascular care through the Penumbra System®, a mechanical thrombectomy platform engineered for the rapid removal of blood clots in acute ischemic stroke. The system features high-performance aspiration catheters, such as the RED® 72, which can reach 132 cm in usable length to navigate complex intracranial anatomy.
Growing Focus on Rare and Orphan Neurological Disorders
Increased research activity in rare neurological and neurodevelopmental disorders presents significant opportunities for specialized CROs. Orphan drug incentives, accelerated regulatory pathways, and targeted therapies drive sponsor investment in niche indications. Neurology CROs with rare-disease expertise support small patient population trials, adaptive study designs, and global site coordination. This trend favors CROs capable of managing regulatory complexity and specialized endpoints, enabling sponsors to advance innovative therapies for underserved patient groups.
- For instance, Johnson & Johnson, through its Janssen Pharmaceutical Companies in collaboration with Legend Biotech, has advanced clinical research for CARVYKTI® (ciltacabtagene autoleucel), a CAR-T cell therapy for relapsed or refractory multiple myeloma. While primarily a hematologic treatment, the program has generated critical neurologic safety datasets from trials such as CARTITUDE-4, which enrolled more than 400 treated patients.
Key Challenges
High Trial Failure Rates and Scientific Uncertainty
Neurology drug development faces persistently high attrition rates due to incomplete disease understanding, heterogeneous patient populations, and limited predictive preclinical models. These challenges increase operational risk for CROs managing late-stage trials. Protocol amendments, extended timelines, and endpoint variability strain resources and margins. CROs must continuously invest in scientific expertise, adaptive trial design capabilities, and early risk mitigation strategies to manage uncertainty while maintaining sponsor confidence and operational efficiency.
Patient Recruitment and Retention Constraints
Recruiting and retaining neurological patients remains a major operational challenge due to cognitive impairment, disease progression, caregiver dependence, and geographic limitations. Lengthy trial durations and burdensome assessments further complicate participation. CROs must deploy targeted recruitment strategies, patient-centric trial designs, and digital engagement tools to address these barriers. Failure to manage enrollment timelines can delay development programs, increase costs, and reduce overall trial success rates in neurology research.
Regional Analysis
North America
North America dominates the Neurology Contract Research Organization market with an exact 41% market share, supported by a mature pharmaceutical ecosystem, high neurological disease prevalence, and strong clinical trial funding. The region benefits from advanced research infrastructure, early adoption of innovative trial methodologies, and widespread use of neuroimaging and biomarker-driven studies. The United States leads regional demand due to a high concentration of biopharmaceutical sponsors and specialized neurology CROs offering integrated preclinical and clinical services. Favorable regulatory pathways, strong patient registries, and robust academic–industry collaborations further strengthen North America’s leadership in neurology-focused clinical research outsourcing.
Europe
Europe holds an exact 28% market share, driven by strong government support for neuroscience research, well-established regulatory frameworks, and extensive cross-border clinical trial networks. Countries such as Germany, the United Kingdom, France, and the Nordic nations play a central role due to their advanced healthcare systems and high participation in multinational neurology trials. The region shows increasing focus on rare neurological disorders, aging-related diseases, and real-world evidence generation. European CROs benefit from harmonized clinical standards and access to diverse patient populations, making the region attractive for complex neurology studies and late-phase development programs.
Asia-Pacific
Asia-Pacific accounts for an exact 21% market share and represents the fastest-growing regional segment in the neurology CRO market. Growth is driven by expanding pharmaceutical manufacturing, rising neurological disease burden, and increasing clinical trial activity in China, Japan, South Korea, and India. Cost-effective trial execution, large patient pools, and improving regulatory transparency enhance the region’s appeal for global sponsors. Governments actively promote clinical research through infrastructure investment and policy reforms. CROs in Asia-Pacific increasingly support early-phase studies and global multicenter trials, strengthening the region’s strategic importance in neurology research.
Latin America
Latin America captures an exact 6% market share, supported by growing clinical research capabilities and increasing participation in international neurology trials. Countries such as Brazil, Mexico, and Argentina offer favorable patient recruitment conditions and lower operational costs compared to developed markets. The region benefits from improving regulatory frameworks and expanding investigator networks. Although infrastructure variability remains, CROs leverage Latin America for patient enrollment acceleration and diversity in neurology studies. Rising awareness of neurological disorders and expanding pharmaceutical investment continue to support gradual market expansion across the region.
Middle East & Africa
The Middle East & Africa region holds an exact 4% market share, reflecting its emerging status in neurology-focused clinical research. Growth is driven by increasing healthcare investment, expansion of clinical trial regulations, and rising interest from global sponsors seeking new patient populations. Countries in the Gulf Cooperation Council lead regional activity due to improved research infrastructure and hospital modernization. In Africa, participation remains limited but gradually expands through international partnerships. While challenges persist, long-term opportunities exist as governments prioritize neurological disease management and clinical research capacity building.
Market Segmentations:
By Service Type:
- Physical characterization
- Raw material testing
By Therapeutic Area:
- Oncology
- Clinical pharmacology
By End User:
- Pharmaceutical and biopharmaceutical companies
- Medical device companies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Neurology Contract Research Organization market players such as Boston Scientific Corporation, MicroVention Inc. (Terumo Corporation), Abbott, Nexstim, Penumbra, Inc., Johnson & Johnson Services Inc., Stryker, MicroPort Scientific Corporation, Codman Neuro (Integra LifeSciences), Medtronic. The Neurology Contract Research Organization market is highly competitive, driven by increasing outsourcing of complex neuroscience clinical trials and the growing demand for specialized therapeutic expertise. Competition centers on the ability to manage intricate study designs, long trial durations, and neurologically specific endpoints while maintaining regulatory compliance across regions. Market participants differentiate through advanced neuroimaging support, biomarker integration, digital and decentralized trial capabilities, and strong patient recruitment networks. Strategic collaborations with pharmaceutical sponsors and academic institutions strengthen scientific depth and execution quality. Ongoing investments in data analytics, artificial intelligence, and real-world evidence generation further intensify competition. Overall, success in this market depends on operational scalability, scientific specialization, and the ability to deliver high-quality, efficient neurology-focused research outcomes.
Key Player Analysis
- Boston Scientific Corporation
- MicroVention Inc. (Terumo Corporation)
- Abbott
- Nexstim
- Penumbra, Inc.
- Johnson & Johnson Services Inc.
- Stryker
- MicroPort Scientific Corporation
- Codman Neuro (Integra LifeSciences)
- Medtronic
Recent Developments
- In May 2025, Questex's Fierce Biotech announced finalists for the 2nd Annual Fierce CRO Awards, highlighting Contract Research Organizations' vital role in drug development, trial management (like Phastar, MMS, CTI), and improving patient outcomes through better research, with winners like MMS celebrated in June for Client Service, emphasizing innovation in areas like data and global ops.
- In May 2025, Julius Clinical (Netherlands) and Peachtree BioResearch Solutions (US) merged to form a comprehensive, global Contract Research Organization (CRO) with enhanced capabilities, especially in Central Nervous System (CNS) research, combining their strengths in Phase I-III studies and expanding into cardio-metabolic, renal, and rare diseases for greater scientific and operational reach across North America and Europe.
- In May 2025, Everest Group recognized Fortrea as a "Leader" in their annual Pharmacovigilance (PV) Operations PEAK Matrix Assessment, highlighting their strong capabilities in managing drug safety and adverse event reporting for the life sciences industry. This placement on the PEAK Matrix signifies Fortrea's significant market impact and vision in delivering robust pharmacovigilance services, alongside other major players like IQVIA and Accenture, noted in the Everest Group report.
- In February 2025, Medtronic has received U.S. FDA approval for the world's first Adaptive Deep Brain Stimulation (DBS) system for individuals with Parkinson's disease. This technology uses real-time brain signals to adjust stimulation levels based on the patient's needs, offering a more personalized and responsive treatment approach.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Therapeutic Area, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Neurology-focused CRO demand will increase as sponsors advance complex and long-duration neuroscience clinical programs.
- Outsourcing partnerships will expand as pharmaceutical and biotechnology companies seek specialized neurological expertise.
- Adoption of decentralized and hybrid trial models will accelerate to improve patient access and retention.
- Advanced neuroimaging, digital biomarkers, and cognitive assessment tools will become standard components of neurology trials.
- Artificial intelligence and data analytics will play a larger role in patient stratification and endpoint optimization.
- Research activity in rare and orphan neurological disorders will continue to grow due to regulatory incentives.
- Global multicenter trials will increase, driving demand for CROs with strong cross-regional execution capabilities.
- Real-world evidence integration will support post-approval studies and long-term neurological outcome assessment.
- Regulatory complexity will encourage early CRO involvement in trial design and development strategy.
- Investment in patient-centric trial approaches will remain critical to improving enrollment efficiency and study success rates.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Neurological Disease Burden and Complex Trial Demand
The increasing prevalence of neurological disorders such as Alzheimer's, Parkinson's, and multiple sclerosis is driving demand for specialized clinical research services. These trials require complex protocols, advanced imaging, and biomarker integration, making CROs with neurological expertise essential for successful study execution.
Outsourcing Shift Among Pharma and Biotech Sponsors
Pharmaceutical and biopharmaceutical companies are expanding outsourcing to control costs, accelerate timelines, and access specialized capabilities. The complexity and high failure rates of neurology drug development make CRO partnerships critical for risk management and operational efficiency.
Advancements in Neuroimaging and Biomarker-Based Research
Rapid adoption of advanced neuroimaging, digital biomarkers, and molecular diagnostics is increasing the need for CROs that can support protocol design, data interpretation, and centralized imaging analysis, enhancing trial precision and supporting innovative neurological therapies.
Expansion of Decentralized and Hybrid Neurology Trials
Decentralized and hybrid trial models are gaining traction due to patient mobility limitations and long follow-up requirements in neurology. CROs investing in digital platforms and remote monitoring are better positioned to improve patient recruitment, retention, and data continuity.
Growing Focus on Rare and Orphan Neurological Disorders
Research activity in rare and orphan neurological diseases is rising, supported by regulatory incentives and targeted therapies. CROs with expertise in rare disease trials and adaptive study designs are increasingly sought after to manage small patient populations and complex regulatory requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Neurology Contract Research Organization Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Neurology Contract Research Organization Market projected to grow between 2024 and 2032?
Which Neurology Contract Research Organization Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Neurology Contract Research Organization Market?
Who are the leading companies in the Neurology Contract Research Organization Market?
Which region commanded the largest share of the Neurology Contract Research Organization Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Pharmaceutical and Biopharmaceutical Companies
- 1.2.2 Medical Device Companies
- 1.2.3 Academic and Research Institutes
- 1.3 By Service Type
- 1.3.1 Early Phase Development Services
- 1.3.2 Physical Characterization
- 1.3.3 Raw Material Testing
- 1.3.4 Clinical Development
- 1.3.5 Biomarker-Driven Studies
- 1.4 By Therapeutic Area
- 1.4.1 Neurology
- 1.4.2 Oncology
- 1.4.3 Clinical Pharmacology
- 1.4.4 Neurodegenerative Disorders
- 1.4.5 Neuropsychiatric Disorders
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,489 million → 2032: USD 14,048.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Neurology Contract Research Organization Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Neurology Contract Research Organization Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Neurology Contract Research Organization Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Neurology Contract Research Organization Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Neurology Contract Research Organization Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Neurology Contract Research Organization Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Neurology Contract Research Organization Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Neurology Contract Research Organization Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,489 million → 2032: USD 14,048.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Neurology Contract Research Organization Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceutical and Biopharmaceutical Companies
- 12.3.7.2 Medical Device Companies
- 12.3.7.3 Academic and Research Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Early Phase Development Services
- 12.4.7.2 Physical Characterization
- 12.4.7.3 Raw Material Testing
- 12.4.7.4 Clinical Development
- 12.4.7.5 Biomarker-Driven Studies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Therapeutic Area - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Neurology
- 12.5.7.2 Oncology
- 12.5.7.3 Clinical Pharmacology
- 12.5.7.4 Neurodegenerative Disorders
- 12.5.7.5 Neuropsychiatric Disorders
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Neurology Contract Research Organization End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Neurology Contract Research Organization Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Neurology Contract Research Organization Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Neurology Contract Research Organization Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Boston Scientific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 MicroVention Inc. (Terumo Corporation)
- 18.4 Abbott
- 18.5 Nexstim
- 18.6 Penumbra, Inc.
- 18.7 Johnson & Johnson Services Inc.
- 18.8 Stryker
- 18.9 MicroPort Scientific Corporation
- 18.10 Codman Neuro (Integra LifeSciences)
- 18.11 Medtronic
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

